XPO Beats As LTL Margins And Volumes Accelerate, Raising Its Outlook Into A Stock Investors Had Soured On
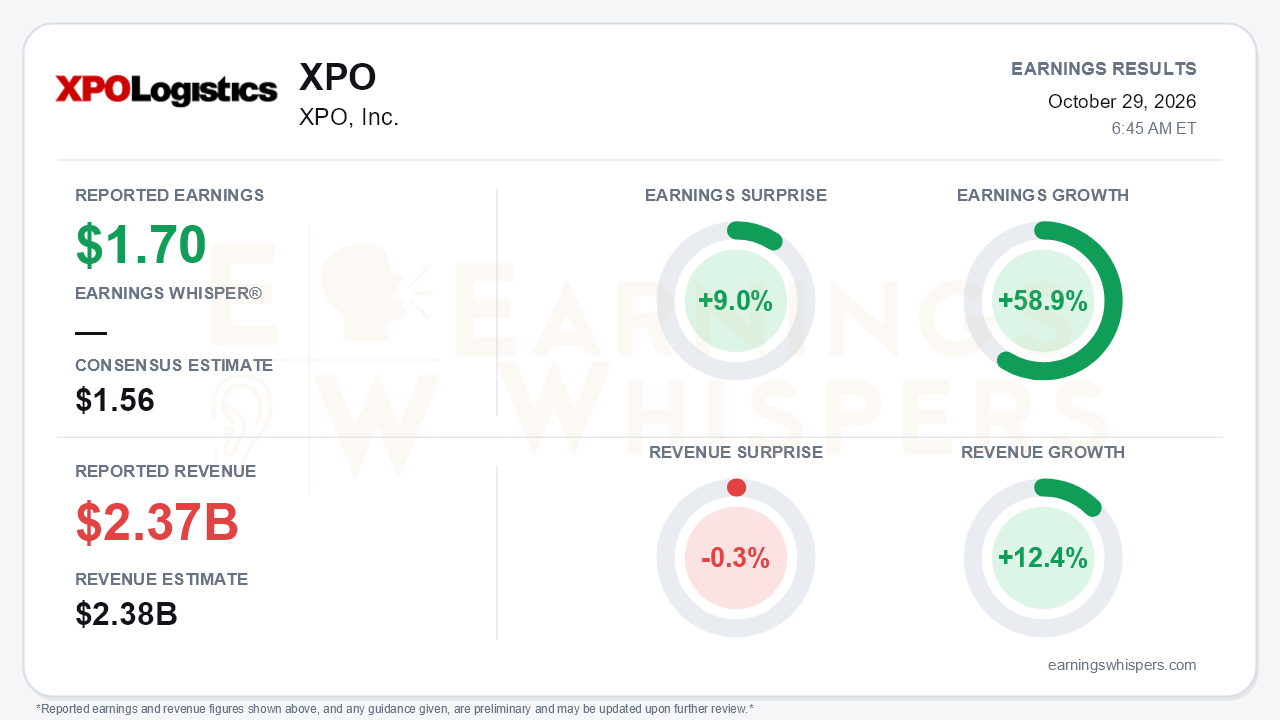
XPO delivered the kind of operating-leverage quarter its LTL turnaround thesis depends on. Adjusted EPS of $1.70 beat the $1.56 consensus by 9.0% and grew 58.9% year over year. Management said growth in both adjusted EBITDA and adjusted EPS accelerated. Revenue of $2.373 billion rose 12.4% but came in 0.3% short of the $2.38 billion consensus. That small top-line miss matters less than what happened to margins and volume. North American LTL posted a record $293 million of adjusted operating income, up 35%. Its adjusted operating ratio improved 260 basis points to 80.1%, beating the company's own sub-81% guide. Management also raised its full-year margin target for the third consecutive quarter.
The quality of the beat holds up well, though the headline revenue growth deserves scrutiny. LTL revenue rose 17.4%, but fuel surcharge revenue jumped 66.5% to $323 million. Excluding fuel, LTL revenue grew 8.5%. The fuel windfall was largely offset on the cost side, where segment fuel and operating expenses rose 29.3%. The real driver was volume plus price discipline. Shipments per day rose 5.8%, tonnage per day rose 5.0%, and yield excluding fuel rose 3.6%. Insurance and claims fell 33% in the segment, consistent with the sub-0.2% damage claims ratio management highlighted. On a GAAP basis, diluted EPS more than doubled to $1.53 from $0.68. That comparison is flattered by a $35 million Con-way environmental charge in the prior-year quarter, worth $0.23 per share. The adjusted comparison is therefore the cleaner read.
The call showed a business whose volume trend has inflected sharply. Shipments per day grew roughly 3% in Q1 and 2.8% in Q2, then 5.8% in Q3 and about mid-7% in October. Tonnage followed a similar arc, from essentially flat in Q1 to mid-6% in October, and management expects further acceleration in Q4. The full-year LTL operating ratio improvement target moved from 100-150 basis points last winter to at least 200 in Q2 and now 250-plus. Fourth-quarter OR is guided below 82%, versus a typical seasonal level near 83%. Free cash flow guidance has climbed to roughly $800 million, from an initial plan of 50% growth. Net leverage fell to 1.9x, and buybacks stepped up to $150 million in the quarter.
Bears still have legitimate ammunition, and it centers on price and cost. Yield excluding fuel slowed to 3.6% from 4.4% in Q2. Management attributed the slowdown to shorter length of haul and heavier truckload-conversion freight. The data support that explanation: average haul fell to 854.7 miles from 866.7, and weight per shipment slipped 0.7%. But mix-driven yield dilution is exactly what skeptics watch for when an LTL carrier chases share. Management's rebuttal is that October yield ex-fuel was up 5% with revenue per shipment up 4%, and that Q4 pricing will accelerate. On costs, LTL salaries, wages and benefits rose 11.1%, up from about 7% growth in Q2. Roughly 3 points of that came from incentive compensation and about 4 points from wage and benefit inflation. Management says the incentive comp resets into 2027 and is worth more than 100 basis points of OR tailwind. Tightening driver hiring, rising truckload rates and an unexecuted European sale with no timeline remain open risks. Europe itself is improving: adjusted EBITDA growth of 9% in Q2 and 26% in Q3 is expected to reach about 40% in Q4.
The market setup is more complicated than the surprise implies. Investors had turned noticeably more cautious heading into the print. Earnings Whispers sentiment fell from 0.27 after the July report to -0.08, a meaningful swing from mildly positive to slightly negative. Shares closed at $181.69 the day before the report, 12.5% below the $207.73 open following the prior release. That left the stock 7.4% under its 200-day moving average of $196.13. It also sat 15.5% below the August 13 high of $215 and just 6.6% above the September 21 low of $170.45. The trend readings are mixed, with price and AVWAP trends negative while momentum has turned positive.
That gap is the central tension. Fundamentals improved through the quarter, with volume, margin guidance and cash flow all moving higher, while the stock moved the other way. The pullback suggests investors were pricing in freight-cycle or pricing risk that this report largely did not validate, with the yield slowdown the notable exception.
The bottom line is that XPO turned in a high-quality beat built on accelerating volume, structural margin gains and rising cash generation, and it raised its outlook again. The 0.3% revenue miss and the Q3 yield slowdown are worth monitoring but look explainable by mix. With sentiment deflated and shares well off their highs, the burden now shifts to Q4 execution on pricing re-acceleration and the sub-82% OR guide.
Read our earnings preview for XPO, Inc.: https://www.earningswhispers.com/article/XPO/21156
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 7 hours | |
| 10 hours | |
| 11 hours | |
| 12 hours | |
| 12 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-24 | |
| Sep-21 | |
| Sep-10 |
