Proto Labs Beats And Raises Again As Growth Hits 14%, But Gross Margin Slippage And A Softer Q4 Guide Cloud The Leverage Story
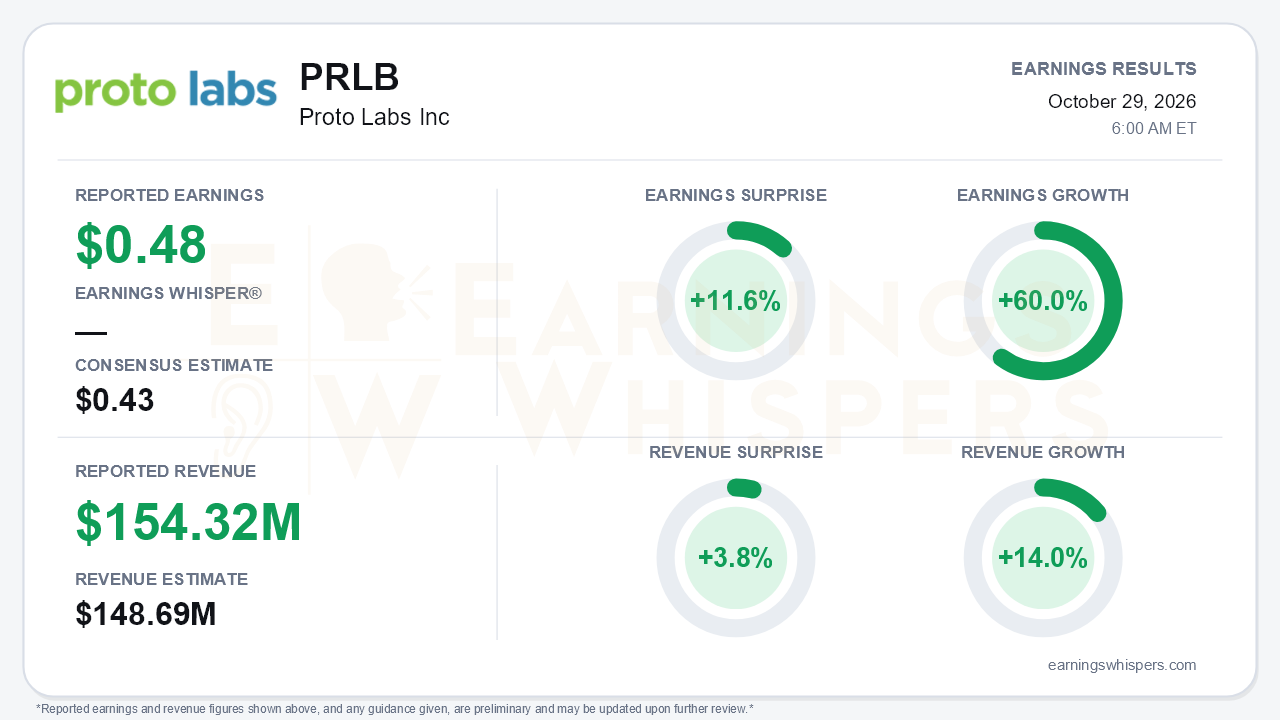
Proto Labs (NYSE: PRLB) delivered the kind of top-line acceleration bulls have waited years for. GAAP earnings of $0.48 per share beat the $0.43 consensus by 11.6% and grew 60.0% year over year. Revenue reached a record $154.32 million, up 14.0% and 3.8% ahead of the $148.69 million consensus. Non-GAAP EPS was $0.63, up from $0.47.
Management raised full-year 2026 revenue growth guidance for the second straight quarter, to 10%-11% from 8%-10%. The original outlook was 6%-8%. Management now expects 2026 to be the company's first year of double-digit organic growth since 2018.
The central tension is that revenue is accelerating while gross margin is moving the other way. The fourth-quarter outlook also implies that much of the third quarter's earnings power will not repeat.
The quality of the beat deserves scrutiny. The earnings upside came from operating expense leverage, not from the production floor:
- **Operating expenses:** Marketing and sales spending was essentially flat year over year at $24.5 million, and R&D rose only modestly. Adjusted opex fell to 32.6% of revenue from 34.8% in Q2 and 35.9% a year ago.
- **Operating income:** GAAP operating margin expanded to 9.4% from 6.5%. Non-GAAP operating margin reached 11.9%, and adjusted EBITDA rose 23.8% to $26.2 million.
- **Gross margin:** Non-GAAP gross margin fell to 44.5%, down 230 basis points from Q2's 46.8% and 140 basis points from a year ago. GAAP gross margin also slipped, to 44.5% from 45.3%.
Management attributed the gross-margin decline to:
- roughly 100 basis points of expensed machine upgrades;
- about 90 basis points of contract labor;
- higher raw material costs.
Part of this looks like the cost of keeping up with volume. Even so, it is a meaningful step down in a quarter when revenue grew faster than at any point this year.
The growth itself was genuinely broad. Constant-currency revenue rose 14.2%, up from 10.2% in Q2 and 8.7% in Q1.
- **CNC machining:** up 16.7%, with factory CNC up 22%.
- **Injection molding:** up 12.6%, sustaining Q2's acceleration from just 3.5% in Q1.
- **3D printing:** swung to 11.5% growth from a 2.7% decline in Q2. U.S. MJF revenue is up more than 40% year to date, and capacity is being added.
- **Europe:** grew 12.2% in constant currency, after a 3.4% decline in Q1 and an 8.1% drop in Q4 2025. Management still described the unprofitable European operation's turnaround as a longer-term effort.
There were soft spots beneath the surface:
- Sheet metal fell 4.6% amid broad end-market weakness.
- Network revenue grew only 3%, with softer U.S. network demand.
- Revenue per customer contact rose 16.6%, but customer contacts were down year over year at 20,777. Management noted the count has risen sequentially for three straight quarters.
The practical read is that growth is coming from deeper spending by existing customers more than from a broadening customer base.
The forward-looking picture is where the setup gets more complicated than the beat implies.
- **Q4 revenue:** guided to $143-$151 million, implying roughly 8% growth at the midpoint versus 14% in Q3.
- **Q4 earnings:** non-GAAP EPS guided to $0.46-$0.54 and GAAP EPS to $0.28-$0.36, both well below Q3 actuals. Gross margin is expected to be flat to slightly down, and SG&A should rise as a share of revenue.
- **2027:** management expects opex growth to track much closer to revenue growth and is aiming only to hold gross margin. That signals the operating leverage behind this year's earnings growth is largely played out.
- **Policy risk:** FY27 defense budget and continuing-resolution uncertainty adds another variable.
On the positive side, management pointed to several initiatives:
- a new Chief Operations Officer, Sam Ramahi;
- an enterprise AI rollout;
- the newly staffed India capability center;
- an MIT partnership;
- expanded ProDesk capabilities.
Tone on the call was notably more expansive, with management framing re-industrialization and physical AI as long-term demand drivers.
Cash generation remains solid. Operating cash flow was $22.8 million, and cash and investments reached $175 million with no debt. However, capital spending has more than doubled year to date, to $15.5 million, and buybacks have slowed sharply, to about $10 million from $36.7 million a year ago.
Investor sentiment remained positive heading into the report but weakened noticeably, falling from 0.38 to 0.22. That suggests some enthusiasm had already cooled.
The stock has still been treated well:
- At $90.91, shares are 13.6% above the opening price after the July report.
- They sit about 24.7% above the 200-day moving average and 23.7% above the inter-earnings low of $73.47, set on that July report day.
- They are 9.1% below the 52-week high of $99.96 reached on October 6.
Momentum and AVWAP trend readings remain positive, while price trend and sequential growth are neutral. That is consistent with a stock that rallied hard and then stalled. With shares already well off their lows, the market is likely to weigh the Q4 deceleration and margin pressure as heavily as the raised annual guide.
The bottom line is that Proto Labs proved its growth recovery is real and broad-based, with acceleration across CNC, molding, 3D printing and Europe. Still, the earnings story is shifting from margin expansion to execution. Bears have legitimate ammunition in the falling gross margin, the implied Q4 slowdown and management's admission that 2027 leverage will be limited. Bulls can point to two consecutive guidance raises and a cash-rich balance sheet. The next leg likely depends on whether volume growth can be sustained without further erosion in gross margin.
Read our earnings preview for Proto Labs Inc: https://www.earningswhispers.com/article/PRLB/21121
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| 13 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-09 | |
| Sep-23 | |
| Sep-04 | |
| Aug-24 | |
| Aug-13 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-10 | |
| Jul-10 |
