DT Midstream Beats And Raises Guidance As Its Contracted Backlog Grows, But Quarterly EBITDA Keeps Slipping
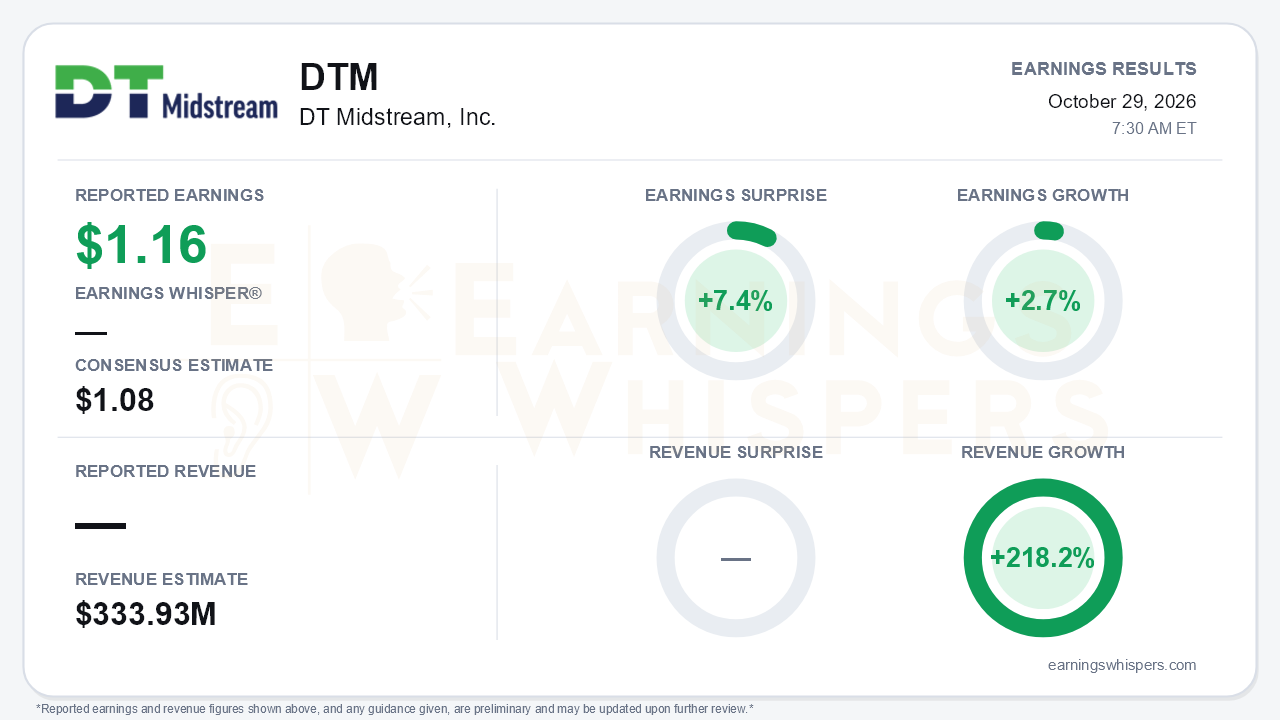
DT Midstream (NYSE: DTM) delivered third-quarter earnings of $1.16 per share, beating the $1.08 consensus estimate by 7.4%. Earnings grew 2.7% year over year. Reported and Operating Earnings were identical, at $118 million, with no adjustments. Management raised its 2026 Adjusted EBITDA guidance midpoint, lifted distributable cash flow guidance, cut growth capex and committed another roughly $0.4 billion of growth projects. That is a clean beat-and-raise on paper. The central tension is that DTM's long-dated, contracted growth story keeps strengthening while its near-term run rate keeps drifting lower. The fourth quarter is guided down again.
The quality of the EPS beat deserves scrutiny. Net income rose $6 million from the second quarter, but Adjusted EBITDA fell to $301 million from $305 million in Q2 and $308 million in Q1. The difference came largely below the operating line. Income tax expense dropped to $41 million from $53 million, and interest expense eased by $2 million. The segments show where the softness sits:
- **Pipeline:** Adjusted EBITDA edged up to $202 million from $200 million.
- **Gathering:** Adjusted EBITDA fell to $99 million from $105 million.
The headline distributable cash flow figure also needs context. It jumped to $270 million from $174 million, but cash interest expense was just $2 million versus $77 million in Q2, which suggests payment timing. Distributions from equity method investees also rose to $64 million from $40 million. Investors should look to the full-year DCF guide rather than the quarterly spike.
The call explained the gathering weakness:
- **Northeast gathering volumes:** fell to 1.25 Bcf/d from 1.38 Bcf/d in Q2 and 1.42 Bcf/d in Q1.
- **Haynesville volumes:** eased to 2.17 Bcf/d from a record 2.2 Bcf/d.
Management pointed to weak prompt natural gas prices driving Northeast producer curtailments into Q4. It also flagged Stonewall offline capacity and expenses, along with downstream outages, as reasons fourth-quarter EBITDA will come in below Q3. The new range of $1.185-$1.225 billion, against $914 million earned through September, implies Q4 EBITDA of roughly $271-$311 million. The guidance raise therefore rests on year-to-date outperformance, not on an improving exit rate. Management noted that volumes remain above minimum volume commitments, which limits the downside, but bears have legitimate ammunition on near-term momentum.
The forward-looking story is where the quarter shone. Committed capital reached about $2.4 billion, roughly 70% of the five-year backlog, up from about $1.6 billion at the end of 2025. Committed 2027 capital has climbed steadily:
- Q4 2025: about $430 million
- Q1: about $440 million
- Q2: about $560 million
- Q3: about $610 million
Three projects reached final investment decision:
- **MIST Southbound Phase 1:** about 300 MMcf/d and a 20% increase in Midwestern capacity, backed by 20-year negotiated-rate contracts.
- **Midwestern lateral:** a pipeline to a 900 MW Indiana power plant. Together with MIST, the Midwestern investment totals $275-$325 million.
- **Guardian Phase 2 modernization:** $130-$150 million.
FERC approved the Guardian rate settlement, allowing recovery of Phase 1 modernization from mid-2027. The project queue broadened further with:
- the Millennium Ramapo open season;
- Haynesville expansions;
- Guardian G4;
- a Washington 10 storage opportunity;
- talks to convert Nexus short-term capacity into long-term commitments.
The 2026 growth capex cut to $375-$425 million, attributed to capital efficiency, improves year-end leverage to about 2.8x on-balance sheet. Management's tone was notably more confident, including discussion of a MIST Phase 2. Risks it acknowledged include political debate over the pace of data center development and permitting-reform uncertainty around the midterms.
The market has not been rewarding the backlog build. Shares have fallen 6.3% since opening at $133.24 after the July report and sit 7.4% below their 200-day moving average. The stock entered the report about 10% below its August 3 inter-earnings high of $138.89 and 7.7% above its October 15 low of $115.92. Investor sentiment improved modestly, from 0.15 to 0.18, and remains mildly positive rather than enthusiastic. Earnings Whispers trend readings lean negative on price and AVWAP, with sequential growth the notable positive.
The bottom line is that DTM's quarter strengthened the multi-year case while leaving the near-term picture soft. Contracted growth, higher guidance, lower capex and better leverage support a credible growth story stretching toward 2029-2031. However, the EPS beat leaned on a lower tax bill, and quarterly EBITDA has declined three straight times with Q4 guided lower on Northeast curtailments and Stonewall issues. With the stock trading below its long-term average, investors appear to want evidence that gathering volumes have stabilized before giving full credit to the backlog.
Read our earnings preview for DT Midstream, Inc.: https://www.earningswhispers.com/article/DTM/21062
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-15 | |
| Oct-12 | |
| Sep-30 | |
| Sep-21 | |
| Aug-26 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-16 | |
| Jun-24 |
