Pediatrix Beats And Lifts Its EBITDA Floor As Volumes Recover, But The Pricing Tailwind Has Run Out
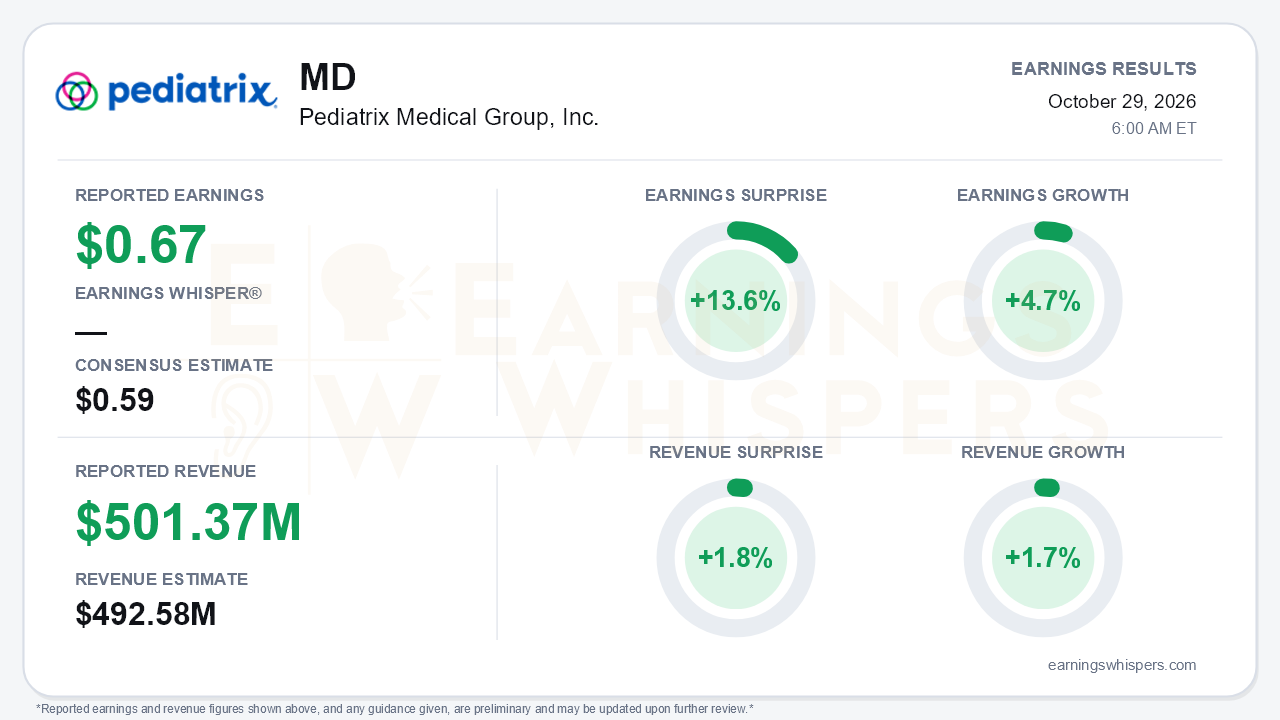
Pediatrix Medical Group (NYSE: MD) delivered a clean beat in the third quarter. Earnings were $0.67 per share against a $0.59 consensus, a 13.6% surprise. Revenue of $501.37 million topped the $492.58 million estimate by 1.8%. Earnings grew 4.7% year over year and revenue rose 1.7%, both modest figures. The central tension is that the drivers behind Pediatrix's 2026 earnings recovery are changing hands. The revenue-cycle collections tailwind that powered same-unit pricing has now been lapped, and patient volumes have stepped in just as that support disappeared. Management had enough confidence to lift the low end of full-year adjusted EBITDA guidance to $290-$300 million from $280-$300 million, raising the midpoint by $5 million.
The quality of the beat deserves some scrutiny, partly because the per-share figures diverge. GAAP EPS was $0.59, down from $0.84. That comparison is distorted by a $20.9 million gain on divested businesses in the year-ago quarter. The company's own adjusted EPS was $0.72 versus $0.67, which differs from the normalized $0.67 Earnings Whispers uses for the consensus comparison. More telling is that adjusted EBITDA slipped to $85.5 million from $87.3 million a year ago, and operating income fell to $65.2 million from $68.1 million. Practice salaries and benefits rose 2.8%, outpacing revenue growth. Per-share results are being flattered by a sharply lower share count: 79.7 million diluted shares versus 85.6 million. Operating cash flow of $117.7 million trailed the $138.1 million of a year earlier.
The call explained what is changing beneath the headline. Same-unit pricing growth has collapsed from roughly 7% in the fourth quarter of 2025 to 4% in each of the first two quarters, and then to just 0.3%. Lapping the collections benefit alone cost more than 100 basis points. Same-unit revenue growth decelerated in a straight line, from 4% to about 3% to 2% to 0.6%. The year-over-year payer-mix improvement roughly halved, from 135 basis points to 70 basis points.
The offset is volume. Same-unit volume swung to +0.3% from -2% in the second quarter, led by maternal-fetal medicine. NICU days were essentially flat after a 3% decline last quarter. Management described the remaining pricing components as sustainable: payer mix, hospital administrative fees and acuity. Clinical salary inflation remains contained at roughly 3% to 3.5%. Sequentially, the story is clearly improving. Adjusted EBITDA climbed from $58 million in Q1 to $76 million in Q2 to $85 million in Q3, ahead of internal expectations.
Capital deployment is the other live catalyst. Pediatrix spent about $83 million repurchasing roughly 3 million shares in the quarter. That brings cumulative buybacks to 10 million shares since August 2025 at an average near $23, below where the stock now trades. Net debt fell to $266 million and leverage dipped below 1x. Management signaled appetite for larger acquisitions in adjacent women's and children's businesses. The 2027 obstetric coding changes could open opportunities, though management declined to size them.
Bears have legitimate ammunition. The raised guidance implies fourth-quarter EBITDA of $70-$80 million, below the third quarter's $85 million, which management framed as cushion for volume and pricing variability. Several risks are building:
- Federal Medicaid changes are squeezing hospital budgets, which could cap increases in administrative fees and subsidies.
- The No Surprises Act arbitration rules are under review, though out-of-network exposure is about 5% or less.
- An ACA subsidy lapse could still erode payer mix with a delay.
Management offered no 2027 commentary.
The market had largely anticipated an improving story. Shares have risen 22.7% since the open after the August report, to $28.91. That leaves them about 21.5% above the 200-day moving average and just 3.8% below a 52-week high of $30.05 set on October 26. The stock entered the report near the top of its inter-earnings range. Investor sentiment remained positive but softened slightly, from 0.14 to 0.12, suggesting enthusiasm has not kept pace with the price. The Earnings Whispers price, sequential-growth and AVWAP trend readings are positive, consistent with that run-up.
The bottom line is that Pediatrix proved it can grow EBITDA sequentially without the collections windfall: volumes recovered, costs stayed disciplined and the guidance floor moved higher. Underlying revenue growth, however, is now barely positive, year-over-year EBITDA dipped, and the fourth-quarter outlook steps down. With shares near their highs, the next leg likely depends on sustained volume gains and well-deployed capital rather than pricing.
Read our earnings preview for Pediatrix Medical Group, Inc.: https://www.earningswhispers.com/article/MD/21104
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 12 hours | |
| 13 hours | |
| Oct-21 | |
| Oct-20 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-15 | |
| Jul-14 | |
| Jun-03 | |
| May-05 | |
| May-05 | |
| Apr-20 | |
| Mar-26 |
