RPC Beats On Adjusted Earnings And Expands Margins Again, But A $74.5 Million Pintail Write-Down Exposes The Weak Link
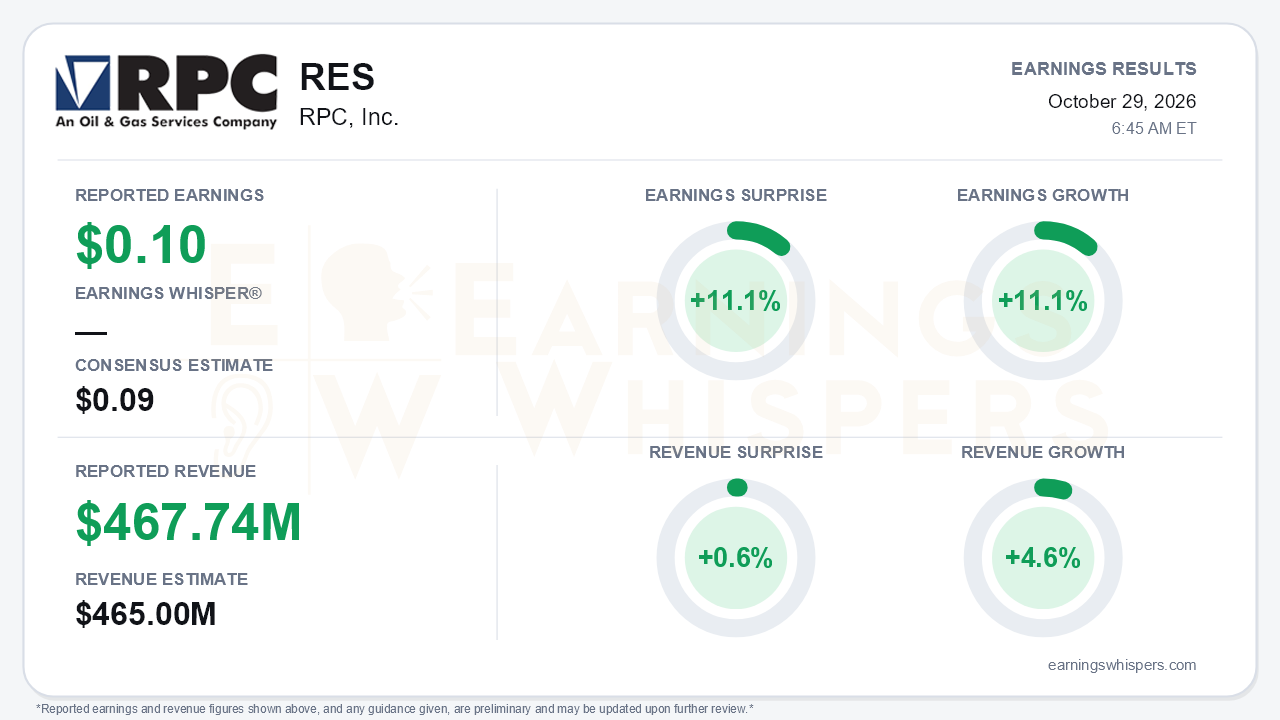
RPC, Inc. delivered a clean adjusted beat for the September quarter. Adjusted earnings were $0.10 per share against the $0.09 consensus, an 11.1% surprise. Revenue of $467.74 million edged past the $465.0 million estimate by 0.6%. Adjusted EPS grew 11.1% year over year and revenue grew 4.6%. The GAAP picture is very different. A $74.5 million non-cash impairment on Pintail, the wireline business RPC acquired in 2025, swung the company to a net loss of $41.9 million, or $0.20 per share, from net income of $12.1 million in the June quarter. That is the central tension. The core oilfield services portfolio is gaining traction, while the company's most recent acquisition is being formally marked down.
The quality of the beat deserves some scrutiny. Adjusted EBITDA rose 8% sequentially to $71.5 million, and margin expanded 100 basis points to 15.3%. That marks a third straight quarter of sequential improvement, up from 12.9% in the fourth quarter of 2025.
Not all of the lift came from operations, however. Combined segment operating income rose about $2.6 million sequentially. Adjusted operating income rose nearly $6 million, also helped by:
- higher gains on asset dispositions ($3.5 million versus $1.4 million);
- lower corporate expenses ($7.9 million versus $9.2 million).
Viewed year over year, the recovery looks less dramatic. Adjusted EBITDA margin is essentially flat with the 15.2% posted a year ago. Support Services revenue and operating income both remain below year-ago levels. The 4.6% year-over-year revenue gain is also far slower than the nine-month comparison, which includes acquired Pintail revenue in the base period for only part of 2025. Much of this year's progress is a climb back from a weak trough rather than a breakout.
The operating story beneath the headline is genuinely improving in Cudd Pressure Control's service lines:
- Coiled tubing revenue jumped 20% sequentially after a 6% gain in the second quarter, helped by large-diameter 2-7/8-inch upgrades. A third reel trailer upgrade was delivered, and two more units can be converted.
- Snubbing grew 12% as a big-bore unit completed its first full quarter on regulatory-driven cavern storage inspections. Management described that work as carrying multi-year visibility.
- Pressure pumping turned positive at +3% after declining 1% in the second quarter, on slightly better pricing. Management noted that industry spare frac capacity is meaningfully lower than several quarters ago.
- Patterson Rental Tools grew 7%.
The weak spots are concentrated. Wireline revenue fell 8% after dropping 16% in the prior quarter, with mid-single-digit EBITDA margins. Its share of the revenue mix has shrunk to 17.5% from 24.1% in the fourth quarter of 2025. Downhole tools also slipped 2% after a 10% gain in the second quarter.
Management's tone shifted noticeably. On the first-quarter call, it described activity as cautious and not broad-based. This quarter, it called itself optimistic and "net positive" on 2027, and said customers expect a more muted fourth-quarter holiday slowdown. Management still expects normal fourth-quarter seasonality after what it called an exceptionally strong third-quarter job and equipment mix, so the third quarter likely flatters the run rate. It also declined to reactivate idle frac fleets without materially better pricing. That discipline protects returns but limits near-term upside.
Bears have legitimate ammunition on cash generation:
- Free cash flow was roughly $1 million in the quarter and just $5.0 million year to date, versus $21.7 million in the first nine months of 2025.
- Receivables climbed to $387 million from $328 million at year-end, and inventory rose as the company stockpiled components in short supply.
- Cash fell to $177 million, although RPC has no revolver borrowings.
- The 2026 capital spending guide was trimmed to $155-175 million from $170-190 million. Management attributed the cut to delivery slippage into 2027, not cancellations, so that spending is deferred rather than saved.
Newly flagged risks include labor tightness, as data centers compete for workers, and broader inflation in labor, trucking and fuel. CEO Ben Palmer's retirement by the end of 2026 adds a leadership transition. The release also explicitly warns that further Pintail impairments are possible if pricing weakness persists. One modest offset is that the write-down reduces depreciation and amortization by about $3 million per quarter.
The market setup is more complicated than the surprise implies. Shares closed at $6.73 the day before the report, up 25.3% since the open following the July release. That price sat 5.5% above the 200-day moving average and just 1.2% below the inter-earnings high of $6.81, set that same day. The stock therefore entered earnings near the top of its range, having already priced in much of the improvement. Investor sentiment remained positive but weakened, slipping from 0.21 to 0.12. That suggests enthusiasm was cooling even as the shares rallied. The Earnings Whispers trend readings are mixed, with AVWAP positive while price, momentum and sequential growth are neutral.
The bottom line is that RPC's core service lines are improving in ways that support management's newfound optimism on 2027. Coiled tubing, snubbing and stabilizing pressure pumping are leading that improvement. Against that, the Pintail impairment confirms that the company's largest recent acquisition is underperforming, and free cash flow remains negligible. A seasonal fourth quarter also looms after an unusually favorable mix. With the stock near its quarterly high and sentiment softening, the next leg likely depends on whether 2027 activity and pricing materialize as management expects.
Read our earnings preview for RPC, Inc.: https://www.earningswhispers.com/article/RES/21124
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-12 | |
| Aug-10 | |
| Jul-30 | |
| Jul-30 | |
| Jul-07 | |
| Jun-23 | |
| May-07 | |
| Apr-29 | |
| Apr-28 | |
| Apr-28 | |
| Mar-18 |
