Perella Weinberg's Q3 Surge Validates The Back-Half Recovery, But A $55 Million Pull-Forward Clouds Q4
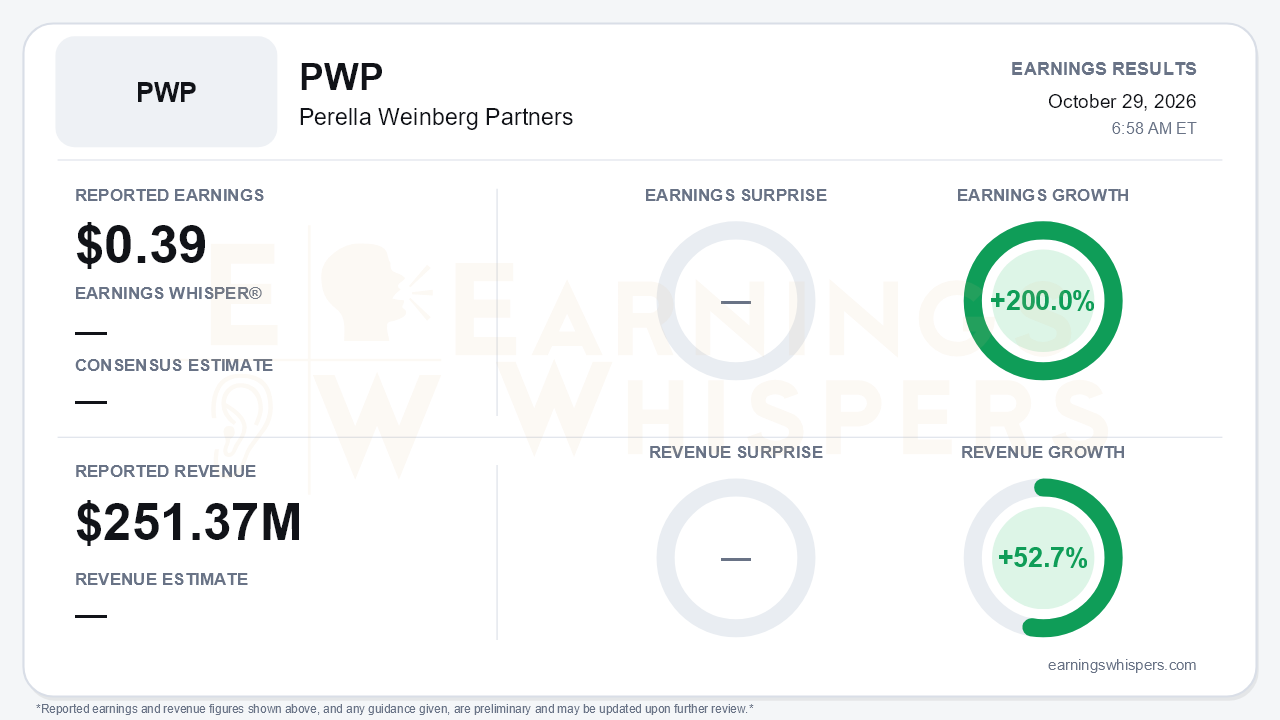
Perella Weinberg Partners (NASDAQ: PWP) delivered the back-half rebound management had been promising all year. Adjusted earnings came in at $0.39 per share, up 200.0% from $0.13 a year ago, on revenue of $251.37 million, up 52.7% year over year and 61% from the second quarter. The trajectory is the story. Revenue went from a 30% decline in Q1 to a roughly flat Q2 (+1%) to a 53% jump in Q3. Year-to-date revenue swung from down 17% at the half to up 5% at $557 million. The central tension is the source of the quarter's strength. About $55 million of Q3 revenue came from closings expected in early Q4 that landed early, so the quarter borrowed from the next one.
The quality of the beat deserves scrutiny, but it holds up better than the pull-forward alone suggests. Strip out the $55 million and revenue would have been roughly $196 million. That is still up nearly 20% year over year and well above the $157 million reported in Q2. The bigger revenue base also showed real operating leverage:
- The adjusted compensation ratio fell to 63% (62.5% on the call) from 67% a year ago, bringing the year-to-date ratio to the firm's 67% target, down from 71% at the half and 79% in Q1.
- Adjusted non-compensation expense was essentially flat at $37.0 million.
- Adjusted operating margin more than doubled to 22.8% from 10.6%.
GAAP results were less flattering but still sharply better. Diluted EPS was $0.21 versus $0.08. GAAP compensation carried $10.5 million of business-realignment costs tied to this year's headcount reductions, plus new acquisition-related incentives from the Devon Park and Gleacher Shacklock deals. Management estimates about $28 million of total realignment costs through year-end. The legacy public-company transaction incentives will be fully expensed by the end of 2026, which should narrow the GAAP/adjusted gap over time. The year-to-date adjusted figures include an $11.5 million RSU vesting tax benefit. The quarter itself was taxed at a 29% adjusted rate, so Q3 was not a tax-driven result.
The call preserved a credible growth story beyond the current quarter. M&A revenue nearly doubled year over year, with strength across consumer, industrials, energy and financial institutions. M&A is up more than 40% year to date. The leading indicators also strengthened:
- Announced-and-pending backlog is about three times last year's level, up from about 2.5 times in Q2.
- Gross backlog under engagement letters is up 40%.
- Fee-paying clients rose 50%.
- Fee events above $5 million increased about 80%.
The talent build adds a capacity argument. PWP has added 14 partners and 13 managing directors year to date, versus five partners last year. Gleacher Shacklock closed September 1 and has already produced six announced UK transactions. Management sounded more confident about 2027 visibility, including an expected recovery in energy M&A. On guidance, it reaffirmed a single-digit full-year decline in non-compensation expense rather than raising the outlook.
Bears have legitimate ammunition, and most of it points at the next two quarters:
- **Pull-forward:** At $55 million, it dwarfs the roughly $10 million pulled in during Q1 and the $18.5 million in Q4 2025. That leaves Q4 with a tougher setup.
- **Deal slippage:** One large pipeline deal reportedly slipped from late 2026 into early 2027.
- **Restructuring:** Restructuring and liability-management revenue is running below a record 2025, even though the Q2 call highlighted ten announced deals and heavy maturity walls.
- **Rates:** Management expects a higher-rate environment, which could weigh on sponsor activity and widen valuation gaps.
- **Capital return:** Buybacks have been limited to fund acquisitions. Cash of $150 million is up from $116 million at Q2 but well below the $256 million at year-end 2025.
PWP still has no debt. It has returned $88 million to equity holders this year and declared a $0.07 quarterly dividend. Management also addressed press speculation about a sale, saying it never initiated a sale process.
On the market side, the stock opened at $19.71 the day after the July report, comfortably above its 200-day moving average of $17.50. That context matters because the quarter's strength was largely signposted. Management had guided investors to a back-half-weighted year, so Q3 confirmed the plan rather than surprising it. Year-to-date share retirements were largely net settlement at an average of $19.85, with only modest open-market repurchases at $15.73. The near-term question is no longer whether the recovery arrived. It is how much of Q4 was spent early.
The bottom line is that Perella Weinberg turned a long-promised recovery into a genuine inflection: tripled adjusted EPS, a comp ratio back at target, and a backlog that kept building after a record quarter. The headline flatters the run rate because of the $55 million pull-forward. Combined with a slipped large deal and softer restructuring revenue, that makes Q4 a harder comparison. The investment case now rests on whether the expanded backlog, new senior bankers and European footprint can carry the momentum into 2027, rather than on the strength of a single quarter.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Sep-29 | |
| Sep-29 | |
| Sep-21 | |
| Sep-18 | |
| Jul-31 | |
| Jul-31 | |
| Jul-21 | |
| May-21 | |
| May-02 | |
| May-01 |
