BorgWarner's EPS Beat Leans On Taxes And Buybacks While Its Industrial Push Gains Ground And Auto Sales Keep Shrinking
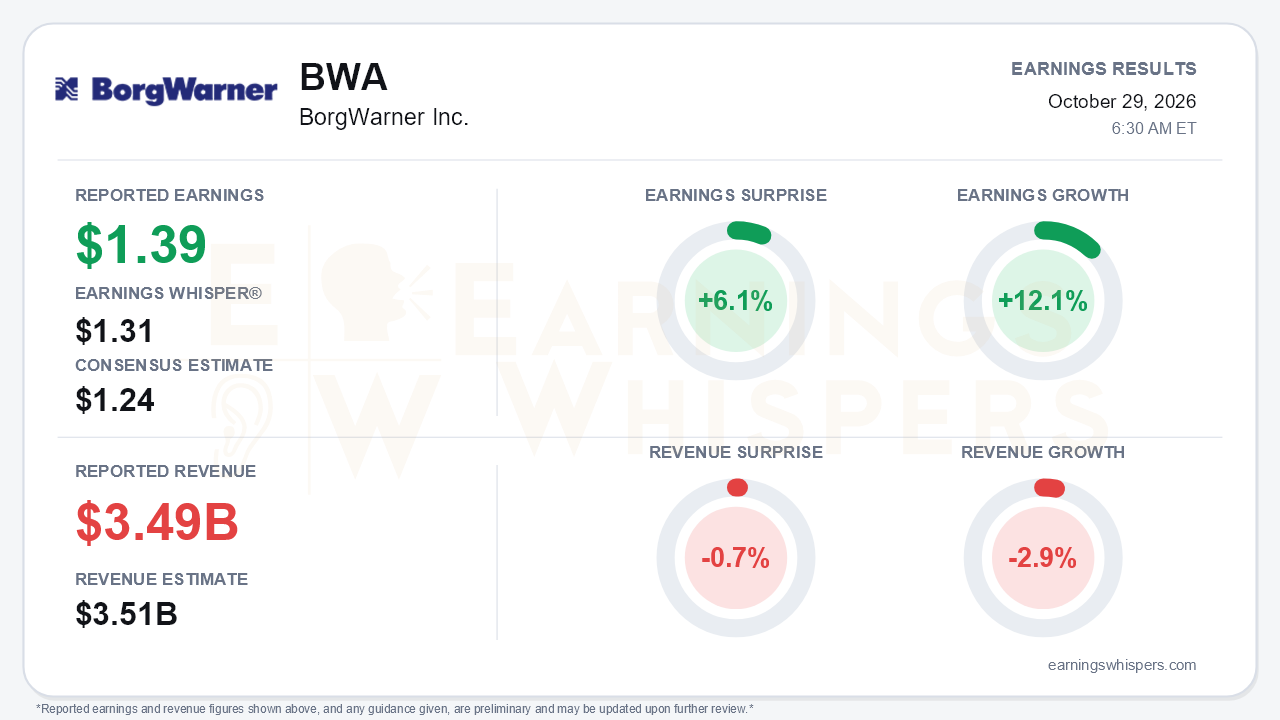
BorgWarner delivered another earnings beat built more on financial engineering than operating growth. Adjusted earnings of $1.39 per share topped the $1.24 consensus and the $1.31 Earnings Whisper number, a 6.1% surprise, and rose 12.1% year over year. Revenue of $3.487 billion missed the $3.51 billion consensus by 0.7% and fell 2.9%. Management raised full-year adjusted EPS guidance for a second straight quarter. The company attributed both the quarter's EPS growth and the guidance raise to a lower effective tax rate and a smaller share count, not to stronger operations. That is the central tension. The per-share story keeps improving while the auto business underneath it shrinks, and the bull case increasingly rests on a data-center and industrial pivot that has not yet produced a hyperscaler contract.
The quality of the beat deserves scrutiny. Adjusted operating income slipped to $381 million from $385 million, and segment adjusted operating income was essentially flat at $443 million. Adjusted operating margin edged up 20 basis points to 10.9%. That is respectable in a declining market, but expansion has slowed sharply from 100 basis points in Q2 and 50 in Q1. Diluted shares fell to 204.6 million from 216.5 million, and the tax provision dropped despite higher pretax income, which explains most of the per-share gain. GAAP EPS jumped 47.9% to $1.08, largely because the year-ago quarter carried heavier non-comparable charges, including a legal settlement and accelerated depreciation. Free cash flow was $195 million, down from $266 million a year ago and $492 million in Q2. Full-year free cash flow guidance of $900 million to $1.1 billion was held.
Segment results show where the business is moving. Organic sales fell 7.4% in Drivetrain & Morse Systems and 4.4% in Turbos & Thermal, while Battery Energy Systems collapsed 40.9%. PowerDrive Systems grew 19.6% organically, and its loss narrowed to $5 million from $35 million. However, the call noted that the PowerDrive result included a one-time volume recovery. Light-vehicle eProduct sales rose 33% to $630 million, faster than the 23% growth posted for all of 2025. The release reports a 3.1% organic decline, while the call cited a 1.6% decline described as roughly in line with the market. That smaller figure appears to exclude the battery drag. Either way, the quarter lost the market outperformance that North American transfer cases had supplied in Q2.
The guidance pattern repeats the theme. Adjusted EPS guidance rose to $5.20-$5.35 from $5.05-$5.30. Meanwhile, the top end of sales guidance was trimmed to $14.0-$14.2 billion, and the organic outlook fell to down 4% to down 2.5%. China production is now seen down 6% to 8%, worse than the 4% to 7% expected in Q2. Margin guidance of 10.7% to 10.9% was held despite $10-$15 million of industrial R&D spending. Management flagged several risks:
- electronics input-cost inflation that could pressure 2027 incremental margins;
- political delays to data-center program agreements;
- auto affordability and interest-rate headwinds in 2027.
The call preserved a credible growth story on the industrial side. The North Carolina turbine generator plant is complete, with production trials by year-end and UL certification underway. Microgrid inverter samples are now with seven customers, up from four, and quoting has begun with a first major customer. BorgWarner also unveiled an 800V data-center power supply unit and referenced a multi-year silicon carbide supply agreement. Management said it is "more bullish than three months ago." Its preliminary 2027 framework calls for modest auto outgrowth plus $300 million of turbine generator revenue, which management characterized as a move to a growth environment. Bears still have legitimate ammunition. There is no concrete hyperscaler contract, the 2028 turbine generator trajectory was deferred to early 2027, and the battery storage awards management expected this year have not materialized.
The market has grown skeptical. Shares entered the report at $55.93, down 13.4% since the open after the August release. The stock sits 7.6% below its $60.51 200-day moving average and 21.2% below its August 12 inter-earnings high of $70.98. It is just 5.3% above the October 23 low of $53.11. Investor sentiment remained positive but weakened modestly, from 0.33 to 0.27. The Earnings Whispers trend signals lean negative on price, AVWAP, and sequential growth, which fits a stock that has been sold despite rising EPS guidance.
The bottom line is that BorgWarner keeps compounding per-share earnings through buybacks, debt reduction, and a lower tax rate while its core auto revenue erodes and margin gains narrow. The industrial and data-center buildout advanced meaningfully this quarter, but until it converts into signed contracts and the promised $300 million of 2027 revenue, the stock's discount reflects legitimate doubt about growth quality rather than ignorance of the beat.
Read our earnings preview for BorgWarner Inc.: https://www.earningswhispers.com/article/BWA/21042
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| Oct-21 | |
| Oct-15 | |
| Oct-06 | |
| Sep-16 | |
| Sep-14 | |
| Sep-08 | |
| Sep-02 | |
| Aug-25 | |
| Aug-17 |
