Novavax Heads Into Q3 Report Needing Sanofi Launch Evidence To Justify Its Rally
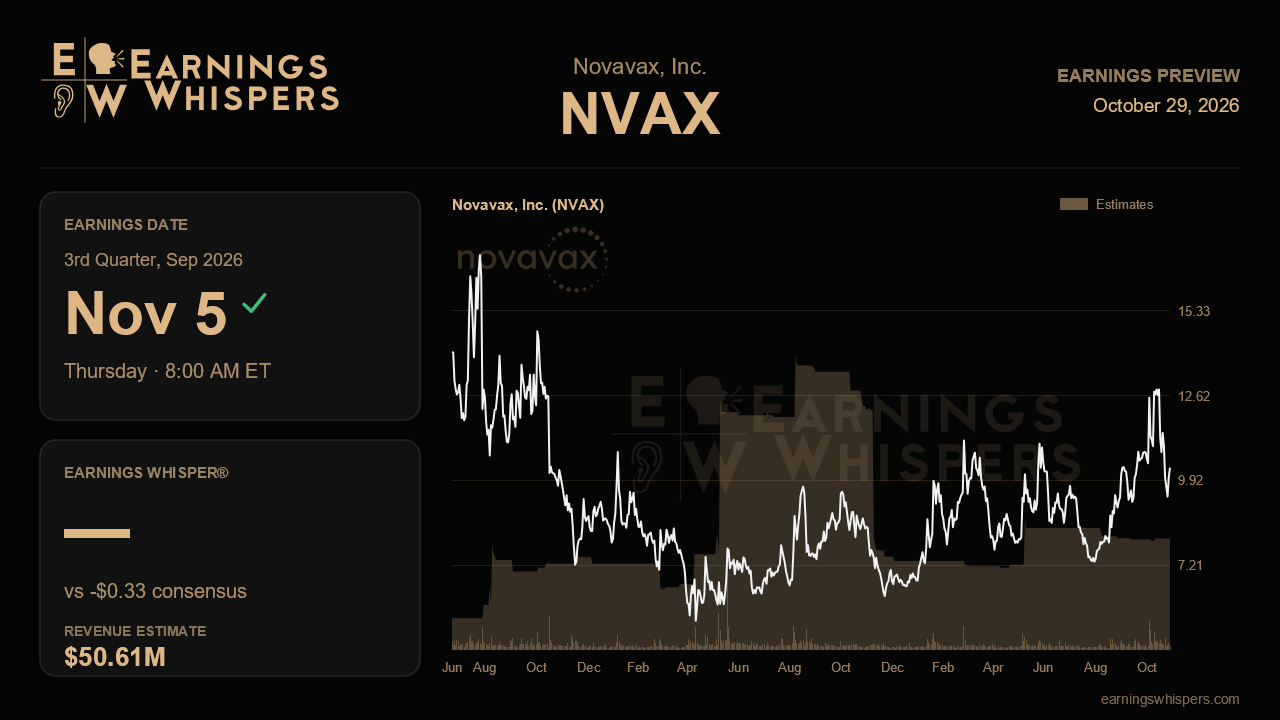
Novavax enters its third-quarter report with a stock that has run well ahead of the hard evidence. Shares have climbed nearly 32% since the company last reported, while the S&P 500 barely moved, yet the most recent conference call offered plenty of strategic optimism and very few numbers. That leaves this release, due before the open on November 5, with a specific job: show that the commercial and partnership story management described is starting to show up in reported results, particularly as the fall respiratory season gets underway under Sanofi's stewardship.
The Street expects a loss of 33 cents per share on revenue of about $50.6 million. That would mark a sharp narrowing from the 62-cent loss a year ago, an improvement of roughly 47%, even as revenue is projected to fall about 28% from $70.4 million. Sequentially, the picture is roughly flat on the bottom line against last quarter's 32-cent loss, with revenue slipping from $56.7 million. In other words, consensus is betting that cost discipline, not top-line growth, carries the quarter. That fits management's framing: R&D and SG&A spending fell 23% year over year early in 2026, and the company tightened its 2028 operating expense target to a range of $150 million to $200 million from a looser below-$200 million marker. A loss in line with or better than forecast would validate that the cost structure is shrinking on schedule toward the profitability goal management now places as early as 2028, a target that itself slipped a year back in 2025.
The bigger question is revenue quality. Management declined last quarter to guide on Sanofi's COVID vaccine sales, saying it could not speak for its partner, so investors are largely flying blind on the single most important commercial driver. What they do know is that Sanofi has signed contracts with all major US retailers, is running direct-to-consumer advertising this fall, and is launching Nuvaxovid in Canada, Germany and the UK. This quarter captures only the front edge of the season, so any commentary on early uptake, retail stocking and international rollout matters as much as the reported figure. Evidence that the US market has stabilized after last year's roughly 20% decline in prescriptions under more restrictive labeling would strengthen the story; signs of continued erosion would challenge it.
Beyond COVID, management pointed to supply sales of Matrix-M and licensing royalties that more than doubled earlier in the year. Sustained growth in those lines would support the argument that the adjuvant platform, including the top-10 pharma oncology collaboration and the Pfizer arrangement worth up to $250 million in milestones per product, is becoming a durable revenue source rather than a one-off. Investors will also want updates on the C. diff program's Phase 1 progress, the timing of the deferred $75 million Sanofi tech-transfer milestone, and whether Sanofi's leadership change and portfolio review have altered its appetite for the COVID-flu combination vaccine, whose Phase 3 start would trigger a $125 million payment.
Sentiment has cooled modestly, sliding to 9.8% bearish from 1.9% bearish ahead of the last report, a notable contrast with the stock's strength. Shares sit at $10.32, comfortably above the 200-day moving average of $9.27 but well off the post-earnings high of $13.39, suggesting some of the summer enthusiasm has already been tested. The trading range since last quarter has also widened, a sign of elevated volatility around partner news.
Ultimately, this report hinges on whether Sanofi's commitment looks as firm in action as management insisted it is in words. Clean cost execution is largely expected; reassurance on the combo program's priority and early signs of a healthier fall launch are what would keep the rally's premise intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| 11 hours | |
| Oct-16 | |
| Oct-16 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-02 |
