Lexicon Heads Into Q3 Needing Proof The Zynquista Refiling Finally Landed On Time
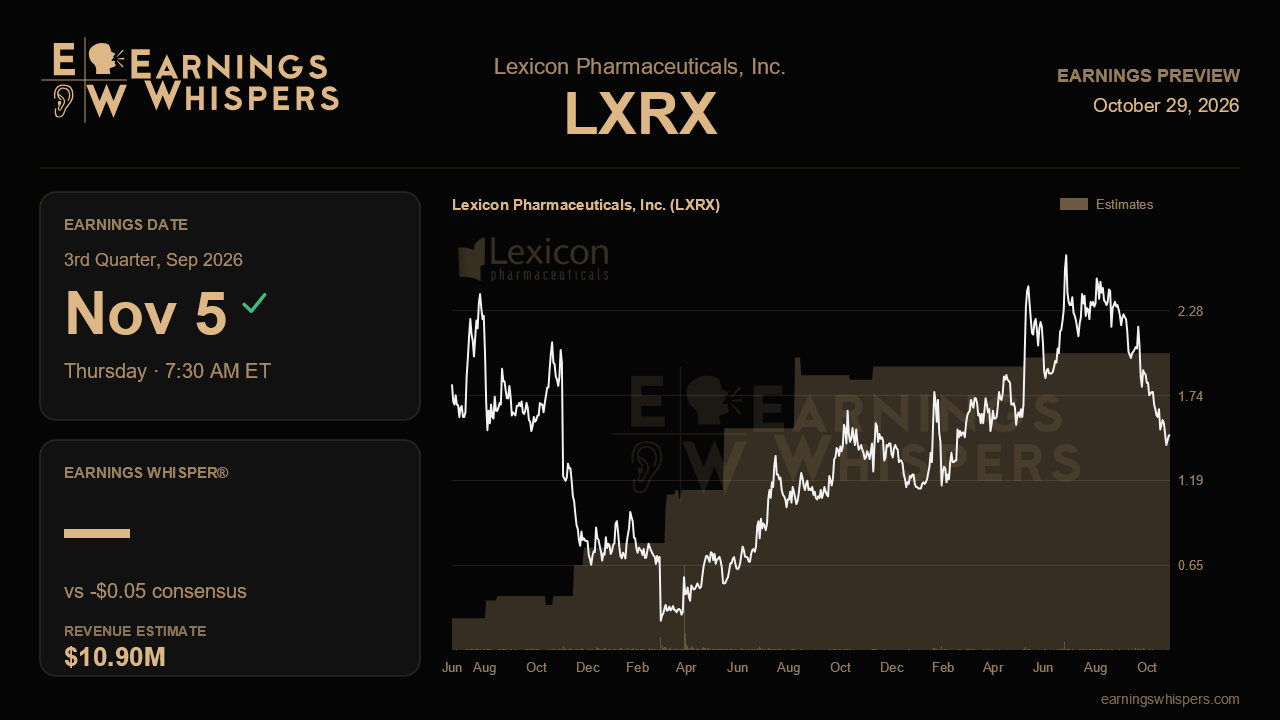
Lexicon Pharmaceuticals reports third-quarter results before the bell on November 5. The numbers matter less than one date. Management told investors last quarter that the Zynquista resubmission for type 1 diabetes would go to the FDA by the end of October 2026. That deadline will have just passed when the company reports. After the filing already slipped from mid-year, a clean confirmation that it went in would go a long way toward repairing credibility. Another delay would undercut the more confident tone management struck in August.
The financial bar is modest. Analysts expect a loss of $0.05 per share on revenue of about $10.9 million. That compares with a $0.04 loss and $14.2 million in revenue a year ago, a 23% decline in sales. The revenue figure deserves a closer look. Last quarter Lexicon booked just $0.7 million, all of it net Impefa sales, because no partner payments landed. The Street's estimate therefore assumes another milestone or licensing payment from Novo Nordisk, whose payments have driven reported revenue swings for over a year. If that payment slips, a headline revenue miss is possible without saying anything about the underlying business. On expenses, management has repeatedly reaffirmed full-year operating spending of $100 million to $110 million. Spending staying inside that range would signal discipline as the company heads into two major readouts.
The August call rested on two programs that both looked less risky than before. Enrollment in Sonata, the hypertrophic cardiomyopathy study, finished well above target, which management said strengthens the trial's statistical power. Top-line data remains slated for the first quarter of 2027. This report is a checkpoint rather than a catalyst for Sonata. Reaffirming that timing would keep the story intact, while any wobble would be a surprise. On Zynquista, the Steno-1 study was expected to reach the drug exposure the FDA requires by the end of August. Diabetic ketoacidosis, a dangerous buildup of blood acids, was running at rates similar to standard care and well below the FDA's benchmark. Confirmation that the exposure target was met, with the safety profile holding, would support a potential approval in the second quarter of 2027. Management blamed the earlier slip on data formatting, because Steno was run by outside investigators and not designed for regulatory filings. That makes execution, not science, the issue to monitor.
There are loose ends. Pilavapidin, the pain candidate once pitched as a partnering opportunity, was barely mentioned last quarter. Any clarity on its status, whether a deal or a quiet deprioritization, would help. Investors should also want an update on LX9851, now in Phase 1 under Novo Nordisk, since partner progress is what generates the milestone revenue the model depends on. The balance sheet is a relative strength. Cash stood at $190.6 million at the end of June, helped by a February raise and a new Hercules loan facility that replaced the older Oxford debt.
The market has not rewarded the improved tone. Shares are down about 24% since the last report while the S&P 500 was roughly flat. At $1.49, the stock trades well below its 200-day moving average of $1.88 and sits near the bottom of its post-earnings range of $1.37 to $2.49. Sentiment remains mildly bearish but slightly less so than heading into the prior report. That suggests skepticism is entrenched rather than deepening.
The sell-off has set a low bar. A confirmed Zynquista filing, an on-schedule Sonata timeline and spending within guidance would validate management's claim that the next 12 months could transform the company. A second resubmission delay would tell investors that management's timelines still cannot be relied on, and no amount of cash on hand would offset that.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 10 hours | |
| Oct-23 | |
| Oct-21 | |
| Sep-28 | |
| Sep-01 | |
| Aug-31 | |
| Aug-24 | |
| Aug-24 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-30 | |
| Jul-27 | |
| Jun-03 |
