CNX Misses A Lofty Whisper As In-Basin Pricing Weakness Undercuts A Rally Built On Buybacks
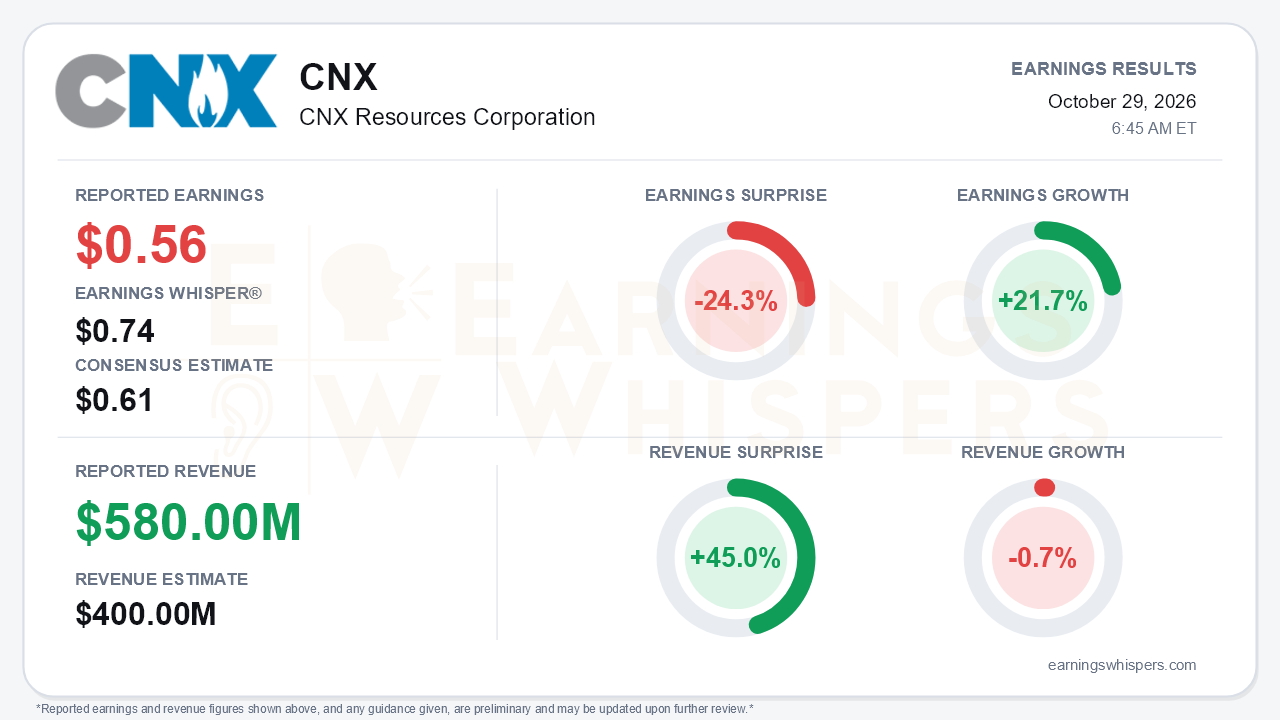
CNX Resources reported third-quarter earnings of $0.56 per share. That fell short of the $0.61 consensus and well below the $0.74 Earnings Whisper number, a 24.3% miss. Revenue of $580.0 million beat the $400.0 million consensus by 45.0%. The underlying comparisons were less flattering than either surprise figure suggests. Earnings grew 21.7% year over year, but revenue slipped 0.7%. The central tension is that the stock ran into the report on enthusiasm, while the call described a business facing weaker local pricing, a softer 2027, and a balance sheet increasingly carrying the weight of the buyback program.
The quality of the quarter deserves scrutiny. The press release offered no figures directly; it pointed investors to prepared remarks, supplemental data, and a presentation. As a result, the call is the main window into what drove the results. The size of the revenue beat stands out against essentially flat year-over-year sales and management's description of deteriorating realized pricing. Investors should be cautious about treating it as evidence of operational outperformance. The more telling figure is the earnings miss against a whisper number that sat roughly 21% above consensus. Expectations had clearly drifted higher than what the quarter delivered.
The call was quieter and more defensive than in recent quarters. Pricing was the main problem. Third-quarter differentials were wider than the Street expected, and roughly two-thirds of CNX's volumes are priced in-basin. Appalachian in-basin gas fell below $1 and at times traded at 50 to 60 cents. The company curtailed some volumes for economic reasons, though under 1 Bcf for the quarter. The macro framing also softened. Last year management discussed a possible second-half 2026 frac crew addition that never materialized. Early this year it pointed to tightening out-year basis. Now it describes 2027 as maintenance mode, with adjustments if conditions degrade. Minor diesel and steel inflation, under 1% of capital, appeared after the prior quarter reported nothing to note. Notably, the second-quarter positives went unmentioned: the 45Z credit, valued at about $40 million a year, and a combined credits-plus-environmental-attribute run rate of about $90 million.
Management still has a story to tell, and it centers on capital allocation and cost discipline. Buybacks stepped up for a second straight quarter, funded with the revolver and framed as growing production per share. Management called repurchases "extremely attractive" and the bar any M&A must clear. Electric frac fleets are containing inflation. Utica infrastructure spending runs about $25 million a year, and the company is targeting all-in capital efficiency of roughly $0.85 to $0.90 per Mcfe. The Deep Utica remains, in management's words, core to the next couple of decades. Long-term demand optimism is intact, and CNX says it is "in the mix" on in-basin direct-sales and data-center supply discussions. Those talks have no timeline, however, and management acknowledged the offers do not yet carry an adequate premium.
Bears have legitimate ammunition. Revolver-funded repurchases during a period of sub-$1 local gas raise leverage just as cash generation is pressured. The CFO transition adds a governance question: Everett Good departed, Ravi Srivastava was promoted, and management declined to comment beyond the 8-K. Consolidation from a large Appalachian merger could also change how peers manage supply in the basin.
The market setup is more complicated than the miss implies. Shares set a 52-week low of $30.78 on October 1, then rallied to an inter-earnings high of $39.00 the day before the report. They entered earnings at $38.05, just 2.4% below that high. The stock was 4.5% above its 200-day moving average and up 8.3% since the opening after the July report. Investor sentiment improved modestly, from 0.21 to 0.28, and remains mildly positive rather than euphoric. A roughly 24% sprint off the lows in four weeks, paired with an elevated whisper number, left little cushion for a quarter like this one.
The bottom line is that CNX delivered year-over-year earnings growth but missed the bar investors had set, and the call shifted the near-term narrative toward basis pain, curtailments, and a maintenance-mode 2027. The buyback and low-cost Utica story remains credible. With the stock entering near the top of its range, though, investors will need evidence that in-basin pricing stabilizes and leverage stays contained before the recent rally looks justified by fundamentals.
Read our earnings preview for CNX Resources Corporation: https://www.earningswhispers.com/article/CNX/21050
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-05 | |
| Sep-25 | |
| Sep-25 | |
| Sep-17 | |
| Aug-12 | |
| Jul-30 | |
| Jul-15 | |
| Jul-15 | |
| Jul-06 | |
| Apr-30 | |
| Apr-23 | |
| Apr-02 |
