AMERISAFE Misses As 'Irrational' Competition Stalls Premium Growth And Erodes Underwriting Margin
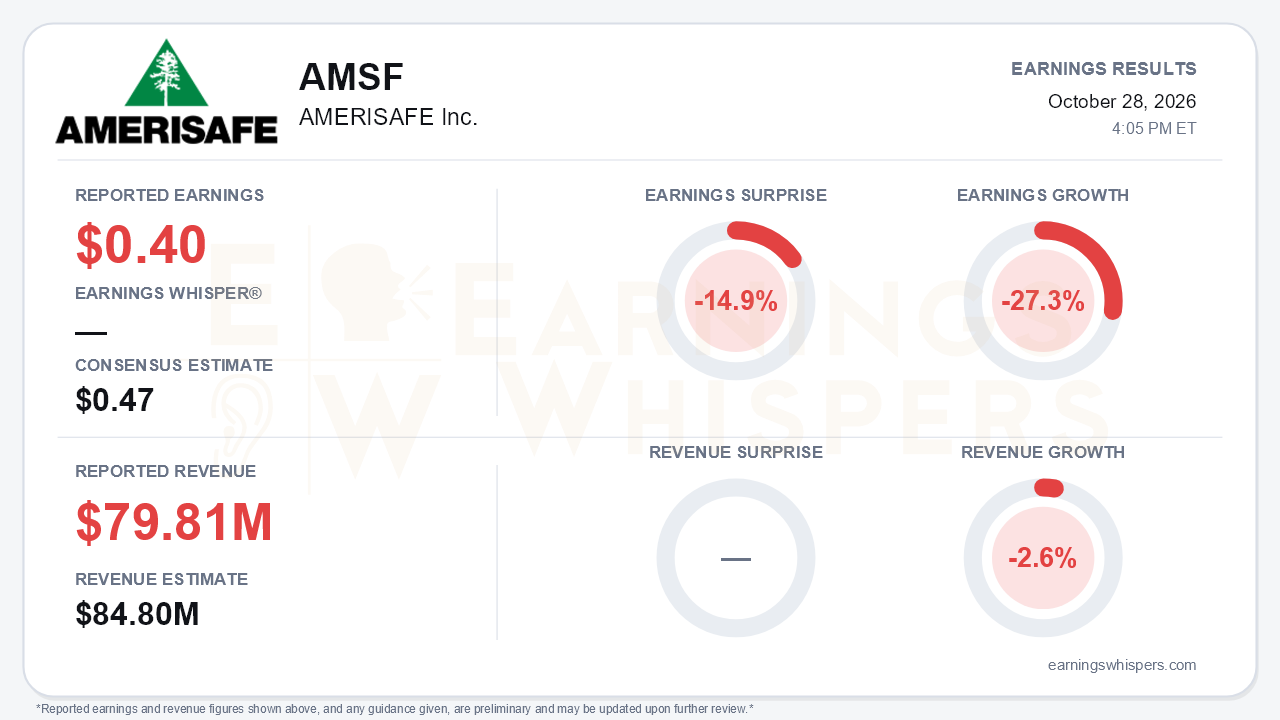
AMERISAFE (NASDAQ: AMSF) missed third-quarter expectations, and the miss looked structural rather than temporary. Operating earnings of $0.40 per share fell 14.9% short of the $0.47 consensus and declined 27.3% from a year ago. Revenue of $79.81 million missed by 5.9% and fell 2.6% year over year. GAAP EPS was $0.39, down from $0.72, a steeper drop because last year's quarter included $4.1 million of unrealized equity gains. The central takeaway is that the growth engine that carried AMERISAFE through 2025 stalled. Management, for the first time in years, called competitor behavior 'irrational.'
Beneath the headline, the deterioration was broad. Gross premiums written fell 4.5% to $76.7 million, ending a streak of nine consecutive quarters of premium growth. The trend over the past year is stark: gross written premium grew 11.7% in Q4'25, 5.6% in Q1 and 7.9% in Q2, then turned negative. Voluntary premium growth slowed to 0.8%, from 10.5% four quarters ago. Payroll audits and related adjustments also turned against the company, reducing premium by $1.6 million versus a $2.5 million benefit a year earlier, as elevated cancellations offset audit gains. On the margin side, the net combined ratio rose to 96.5% from 90.6%. Underwriting profit fell 62.6% to $2.5 million. Three pieces drove it:
- The current accident year loss pick rose a point to 72.0%.
- Favorable reserve development shrank to $6.9 million from $8.9 million.
- The expense ratio climbed to 32.5% on state assessments, compensation and commissions.
The quality of the quarter deserves scrutiny because the trend runs one way. Operating EPS has fallen each quarter, from $0.55 in Q3'25 to $0.50, $0.44 and now $0.40. Reserve releases, the company's longtime earnings cushion, have also drifted lower, from $7.6 million in Q1 to $7.3 million in Q2 and $6.9 million in Q3. Notably, Q3 operating EPS came in below the $0.41 quarterly dividend the board just reaffirmed. Book value per share is down 11.5% year over year to $12.80. Buybacks shrank to just $0.2 million, and the investment portfolio has declined to $753 million from $797 million at year-end.
The call added texture, and most of it was cautionary. Management's description of competition moved from 'steady' in Q4'25 to 'intense' in Q2 to 'irrational' now, citing rival pricing, commissions and policyholder dividends. Renewal retention slipped to 92.3% from above 93%. Other pressures are building:
- Loss-cost declines of roughly 5-6% are expected to persist into 2027 rather than moderate as hoped.
- Wage growth among insureds slowed to 4.1% from 6.1% in Q4'25, which limits audit premium.
- Claims reported are outpacing premium growth amid hospital-driven medical inflation.
- Large losses reached 18 through nine months, versus 7 at midyear.
There are offsets. In-force policy count rose 4% and the 72% loss pick was held. The CEO reaffirmed a mid-single-digit growth expectation, although that sits awkwardly next to year-to-date gross premium growth of 3.0% and a negative third quarter.
The constructive part of the story is the investment portfolio. The tax-equivalent book yield ticked up to 4.0%. New money is being invested about 146 basis points above maturing assets, up from about 91 basis points in Q2, and duration was extended to 4.7 years from 4.2. The A.M. Best rating was affirmed, and management cited year-to-date fixed-cost efficiencies and new-business improvement late in the quarter. Still, net investment income grew only 0.6% because the asset base is shrinking. The unrealized loss on held-to-maturity securities also widened to $23.8 million from $5.6 million. Yield is helping, but not enough to offset an underwriting margin squeeze of this size.
The market had largely anticipated trouble. Shares fell 21.6% from the $32.29 open after the July report to $25.30, and they sit about 18.6% below the 200-day moving average of $31.10. AVWAP readings remain negative. Investor sentiment improved meaningfully, from -0.37 to -0.07, yet it remains slightly negative. That suggests expectations had already reset lower and some investors were looking for stabilization. This report offered little evidence of that, though the steep prior decline means a good portion of the bad news was arguably priced in.
The bottom line is that AMERISAFE's quarter confirmed the soft-market thesis bears have been building. Premium growth turned negative, margins compressed on several fronts at once, and management's own language on competition hardened. Rising investment yields and steady policy-count growth provide some ballast, and the late-quarter uptick in new business is worth watching. Until pricing discipline in the market returns or audit premium recovers, however, the earnings trajectory points lower, and the dividend is no longer comfortably covered by operating earnings.
Read our earnings preview for AMERISAFE Inc.: https://www.earningswhispers.com/article/AMSF/20901
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-20 | |
| Oct-01 | |
| Sep-04 | |
| Aug-31 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-10 | |
| Apr-23 | |
| Apr-22 | |
| Apr-22 | |
| Apr-02 | |
| Feb-26 |
