GFL Environmental Narrowly Misses On EPS, But A Third Guidance Raise And The SECURE Deal Shift Focus To The Take-Private Bid
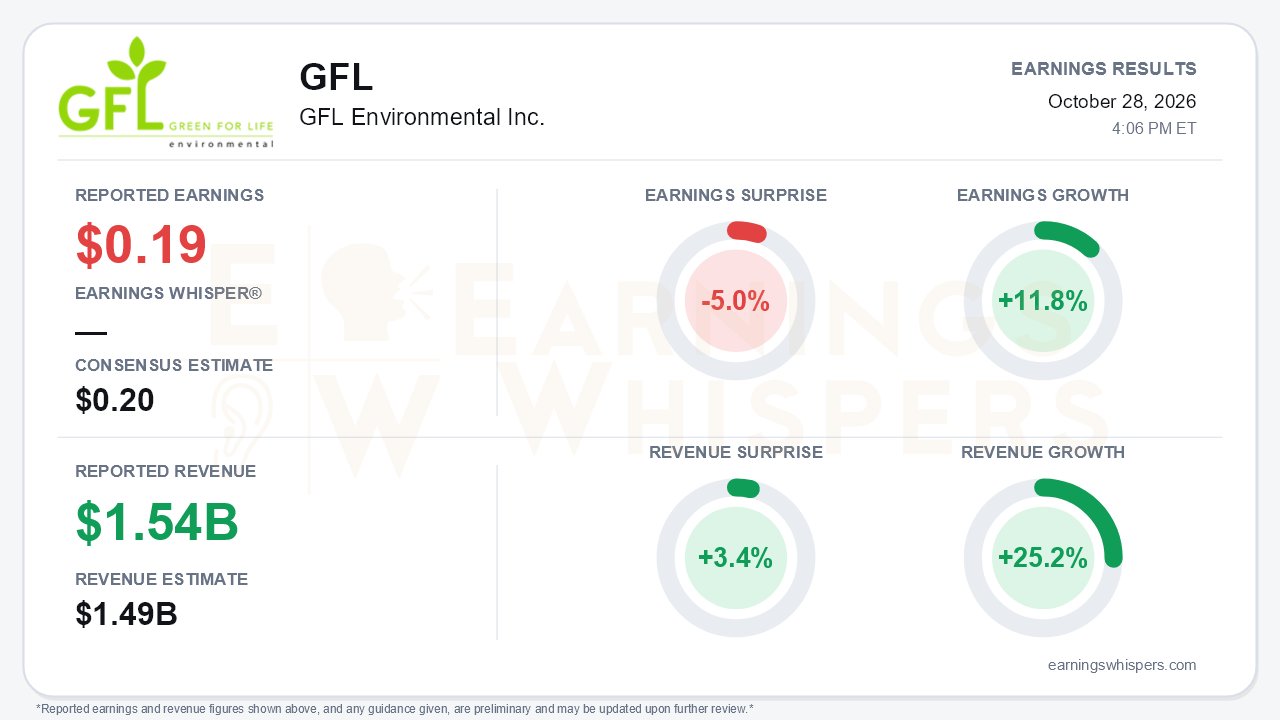
GFL Environmental's third quarter left a small blemish on the earnings line and a much larger story everywhere else. The company reported earnings of $0.19 per share, a 5.0% miss against the $0.20 consensus. Revenue of $1.54 billion beat the $1.49 billion estimate by 3.4%. Earnings grew 11.8% year over year and revenue rose 25.2%.
The press release reports in Canadian dollars, which explains why its figures look different. It shows revenue of C$2.16 billion, up 27.2%, and adjusted EPS of C$0.26 versus C$0.23 a year ago. The modest EPS miss matters less than what management did with the full-year outlook. GFL raised 2026 guidance for the third time this year. It now expects revenue of C$8.055-8.075 billion, adjusted EBITDA of C$2.49-2.495 billion, and adjusted free cash flow of roughly C$1.02 billion. The free cash flow target was C$900 million last quarter and C$835 million when the year began.
The quality of the quarter deserves scrutiny, because the headline growth is heavily acquisition-driven. Acquisitions contributed 18.7 points of third-quarter revenue growth, while organic growth was 7.4%. Most of the guidance raise likewise reflects M&A, chiefly SECURE Waste Infrastructure, plus currency, rather than organic upside. SECURE added about C$150 million of revenue and C$50 million of EBITDA in its first month alone.
On a GAAP basis, the company swung to a C$28.0 million net loss from continuing operations. A year earlier it earned C$90.4 million. The loss was weighed down by:
- C$46.5 million of transaction costs;
- a C$32.4 million ARO depreciation adjustment;
- higher interest expense from deal financing.
Net leverage rose to 3.8x from 3.4x at year-end, and long-term debt climbed to about C$11.7 billion. Management guides leverage to the mid-3s by year-end.
Underneath the acquisitions, the organic engine did improve. Organic growth accelerated 100 basis points from the second quarter, with core price of 5.7% and surcharges adding 1.5 points. Construction and demolition landfill tons rose 4.5%. That was the first positive reading since early 2025, after declines of roughly 10% in Q2 and 7.5% in Q1. Adjusted free cash flow of C$272.5 million beat the company's own C$235 million guide and rose more than 50%.
The headline adjusted EBITDA margin of 31.5% was essentially flat with a year ago, and that is the central tension. Diesel prices up more than 60% are adding about C$125 million of 2026 cost, only partly recovered through surcharges, which amounts to a roughly 75-basis-point margin drag. Excluding M&A and diesel, underlying margin expanded about 115 basis points by the release's figure; the call cited 125. Segment results diverged. Canada's margin rose to 35.7% on SECURE, while the U.S. margin slipped to 33.8% from 36.1%.
The call preserved a credible growth story, but bears have legitimate ammunition. Management issued a 2027 framework of:
- revenue of roughly C$9.7-9.8 billion;
- EBITDA of C$3.125-3.15 billion;
- adjusted free cash flow above C$1.3 billion.
Management also cited SECURE synergies of C$25 million with C$25-50 million of potential upside, and pricing opportunities beyond its Investor Day target. Tone was notably assertive, with leadership describing the base business as never better.
Against that, management flagged several headwinds:
- fourth-quarter volumes should decelerate and possibly turn negative as EPR benefits lap and Midwest ancillary services are exited;
- a restructured recycling contract removes C$13 million of quarterly pass-through revenue;
- landfill leachate costs are rising, and roll-off pulls remain flat;
- headline pricing may not accelerate in 2027;
- borrowing spreads are 100-125 basis points wider than earlier this year;
- net capex guidance rose to C$910 million.
The dominant near-term catalyst is not operational. A Special Committee is reviewing unsolicited take-private proposals, with a final bid deadline of November 9. That introduces binary outcome risk, including the possibility of a bid below management's view of value. It also makes the stock partly a deal-pricing exercise rather than a pure earnings story.
Investor sentiment remains negative but improved meaningfully, rising from -0.35 to -0.24 since the prior report. Shares are up 3.9% from the open after the July report, at $43.59. That leaves them about 6.9% above the 200-day moving average of $40.77, and the Earnings Whispers price and AVWAP trend readings are positive. The market has treated the stock steadily rather than enthusiastically, consistent with investors waiting on the strategic review.
The bottom line is that GFL's slight EPS miss is overshadowed by a third guidance raise, accelerating organic growth, strong free cash flow and an ambitious 2027 framework. Still, much of the growth is bought with debt-funded acquisitions, diesel is masking real margin progress, and volumes are softening into year-end. With sentiment still negative but improving and a take-private deadline days away, the next move likely hinges more on the Special Committee than on the quarter itself.
Read our earnings preview for GFL Environmental Inc.: https://www.earningswhispers.com/article/GFL/20940
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-08 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-17 | |
| Sep-17 | |
| Sep-16 | |
| Sep-01 | |
| Sep-01 | |
| Aug-11 |
