Enerflex's Earnings Jump 50% And Bookings Hit A Record $1 Billion, But Flat EBITDA Keeps The Payoff In 2027-2028
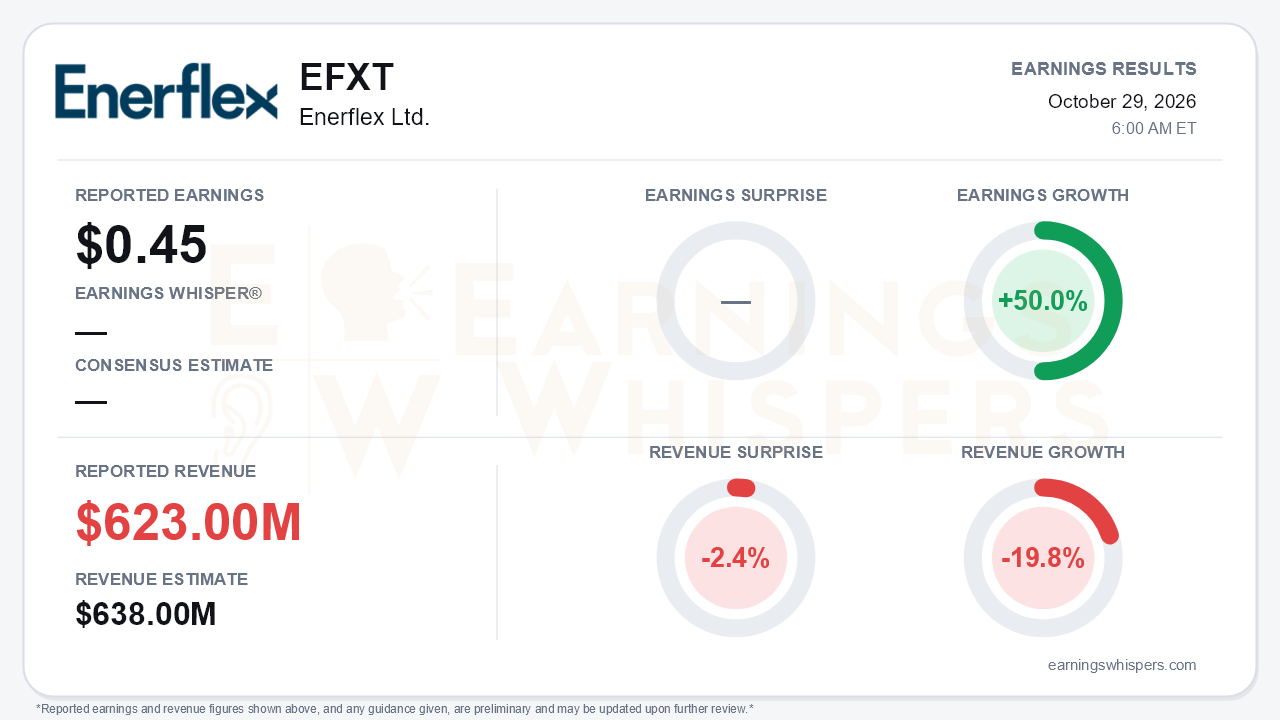
Enerflex (NYSE: EFXT) reported third-quarter earnings of $0.45 per share, up 50.0% from a year ago, on revenue of $623.0 million. Revenue fell 19.8% year over year and missed the $638.0 million consensus by 2.4%. The headline numbers are not the main story. Engineered Systems (ES) bookings reached a record $1.0 billion, about triple the $339 million booked a year earlier and double the $488 million in Q2. ES backlog climbed to $2.1 billion. Enerflex also moved behind-the-meter gas-fired power generation from a pipeline concept into booked work. That is the central tension: demand has stepped up, but current earnings power has not yet followed.
The quality of the earnings gain deserves scrutiny. Net earnings rose to $55 million from $37 million, but several non-operating items did much of the work. These included a $5 million gain on the Asia Pacific divestiture, lower net finance costs, a smaller tax bill, and a much smaller unrealized loss on note redemption options ($3 million versus $16 million). Adjusted EBITDA tells a less flattering story. It fell to $129 million from $145 million a year ago and was essentially flat with $128 million in Q2 and below $137 million in Q1. Gross margin before D&A was 28.3%, up from 26.5% a year ago but down from 30% in Q2 and 31% in Q1. Management attributed the sequential decline to mix and project sequencing, with ES margins slipping to 17%, in line with the product line's historical average. Core SG&A also rose to $58 million from $53 million to support growth. The year-over-year revenue decline mostly reflects a tough comparison: last year's quarter included revenue recognized on the Bisat C expansion start-up. Sequentially, revenue rose from $582 million.
Cash generation was the cleanest part of the quarter, though it had help. Free cash flow was $102 million, up from $43 million a year ago and $32 million in Q2. That figure included $51 million of working capital recovery and quarter-end customer deposits, so it should not be treated as a new run rate. Funds from operations were $96 million, down from $115 million a year ago. Even so, net debt fell to $312 million from $455 million in Q2, helped by $62 million of APAC proceeds. Bank-adjusted leverage dropped to 0.6x. The board raised the quarterly dividend about 17% to $0.035, which the call described as the third consecutive annual increase.
Management's tone was noticeably more confident on the call. Enerflex now expects full-year ES bookings to exceed $3 billion, roughly double its prior record of about $1.5 billion. Book-to-bill was 3.0x in the quarter. After quarter-end, Enerflex won an award to supply more than 1.0 gigawatt of power generation for a North American data center. That lifts its power generation backlog above 1.75 gigawatts, with deliveries extending through 2028, and management identified another 1.5 to 2 gigawatts of filtered opportunities. U.S. contract compression also remained steady. The fleet grew to 521,000 horsepower from 496,000 in Q2, utilization held at 94%, and the company kept its 10% to 15% fleet growth target.
The catch is timing and capacity. Management said power generation margins should be accretive to ES, but they are not expected to show up until late 2027 and 2028. ES capacity remains constrained until the planned expansions arrive, largely in 2028. Enerflex is spending $30 million to $40 million on ES facilities this year, up from roughly $15 million previously guided, plus about $85 million in 2027. Total 2026 capex guidance was held at $185 million to $195 million only because maintenance spending was cut to about $55 million, partly by deferring work into 2027. Equipment supply was named as a gating factor for further power bookings. Analysts also raised the risk of data-center backlash and regulatory shifts after the U.S. midterms. Bears have legitimate ammunition here: a record backlog is only as valuable as the margins and execution behind it.
The market had already priced in a good part of this story. Shares rose 20.8% from the open after the prior report to $25.00 ahead of the release. That leaves the stock about 10.9% above its 200-day moving average. It is also roughly 30% above its late-August low but nearly 10% below its October 13 high of $27.69, suggesting some enthusiasm cooled before the print. The Earnings Whispers price, momentum and AVWAP trend readings are positive. Investor sentiment, however, remained near neutral and edged slightly more negative into the report.
The bottom line is that Enerflex delivered a transformational bookings quarter wrapped in a flat earnings quarter. The 50% EPS gain relied heavily on below-the-line items. Underlying EBITDA and margins have stalled, and the strong cash flow was flattered by working capital recovery. The backlog, power generation wins and balance sheet give the growth story real credibility. The open question is whether Enerflex can add capacity and convert that backlog at accretive margins before investors lose patience with the 2027-2028 timeline.
Read our earnings preview for Enerflex Ltd.: https://www.earningswhispers.com/article/EFXT/21063
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-01 | |
| Sep-30 | |
| Aug-06 | |
| Aug-06 |
