Restaurant Brands Tops Consensus But Misses The Whisper As Burger King's Surge Is Offset By A Stalled Popeyes Turnaround And Slowing Growth
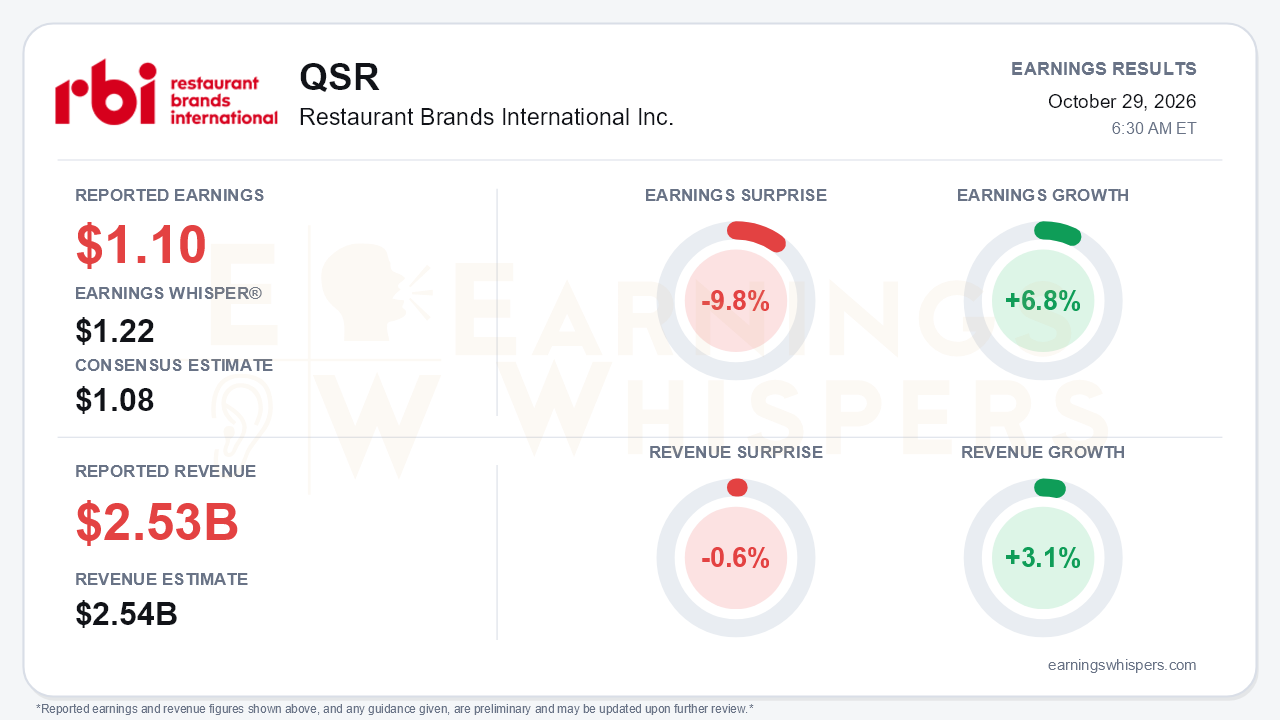
Restaurant Brands International delivered a quarter that will look different depending on which bar investors use. Adjusted earnings of $1.10 per share edged past the $1.08 consensus but fell 9.8% short of the $1.22 Earnings Whisper number. Revenue of $2.525 billion came in 0.6% below the $2.54 billion consensus. Earnings grew 6.8% year over year and revenue rose 3.1%. That earnings growth is a clear step down from the 14.6% adjusted EPS growth in the first quarter and the 10.7% pace a year ago. That is the central tension: Burger King US is having its best stretch in years, but consolidated profit growth is decelerating, and Popeyes has become a drag rather than a recovery story.
The quality of the headline numbers deserves scrutiny. GAAP diluted EPS from continuing operations jumped to $1.54 from $0.96. That gain came largely from a $133 million income tax benefit tied to intra-group reorganizations, not from operations, and management notes it does not affect the adjusted tax rate. Organic adjusted operating income grew 6.7%, down from 10.7% in the first quarter and 8.8% a year earlier. Even that figure had help. Tim Hortons' AOI growth was driven primarily by tariff refunds of roughly $11 million. International G&A included one-time legal expenses, and Popeyes AOI fell 8% as comps declined and compensation costs rose. The Restaurant Holdings segment contributed just $5 million of AOI versus $10 million a year ago. RBI still expects $10 to $20 million for the year, which implies a fourth-quarter loss as refranchising and international start-up spending weigh.
The operating story beneath the numbers is sharply bifurcated.
- **Burger King US:** Comps accelerated to 8.4% from roughly 6% in the first quarter and 3.2% a year ago. Management said the brand reclaimed the No. 2 spot in US burgers and widened its gap over peers to nearly 10 points. The upgraded nuggets launch pushed King Jr. meal unit volumes to their highest level in more than a decade.
- **Tim Hortons Canada:** Comps recovered to 1.8% from a soft second quarter, aided by matcha, Monster energy infusers, and a Canadian Tire loyalty tie-up that is ahead of plan. That is still well below the 4.2% posted a year ago, and higher gas prices are weighing on rural and drive-thru traffic.
- **International:** Comps slowed to 3.9% from 5.7% in the first quarter and 6.5% a year ago, with Western Europe macro headwinds cited.
- **Popeyes US:** Comps fell 2.2%, with the domestic segment down 1.8%.
The Popeyes deterioration is the most consequential change in the investment setup. Management withdrew its earlier expectation for positive Popeyes comps in the second half of 2026. It said the $6 Big Box promotion was less incremental than hoped and that scaling back wings is pressuring sales. Popeyes North America unit growth will also slow from 2025. The Burger King remodel timeline is slipping as well, with the target of roughly 85% modern image now pushed to 2028-2029. On the positive side:
- Net restaurant growth ticked up to about 3%.
- Popeyes International crossed 2,000 units and $2 billion in system sales.
- Popeyes China posted its first quarter of positive four-wall margins.
- Beef cost relief is beginning, which management expects to support remodel pace in 2027.
The balance sheet and capital return story improved meaningfully. Net leverage fell to 4.0x from 4.4x a year ago, and Moody's upgraded RBI to Ba2, supporting management's stated path toward investment grade by 2028. Repurchases totaled roughly $275 million in the quarter and $444 million year to date, on track for about $500 million. Refranchising accelerated to 135 Burger King units. All 2026 guidance was reaffirmed, including G&A of $600 to $620 million, interest expense of $500 to $520 million, and capex of around $400 million. Organic AOI growth of 7.8% year to date keeps the 8% target within reach, though the third-quarter run rate sits below it.
Investor sentiment heading into the report was negative but improving, rising from -0.25 at the prior report to -0.18. That suggests expectations were tempered rather than euphoric, though the elevated whisper number shows some investors were looking for more. The stock has gone essentially nowhere, up 1.6% since the open after the August report at $74.52. It sits just 0.7% above its 200-day moving average and near the middle of its inter-earnings range, 9% below the late-August high of $81.88 and 8% above the early-October low of $69.03. The Earnings Whispers price and AVWAP trends remain negative, while momentum and sequential growth are neutral. That reflects a stock that has not yet been rewarded for Burger King's progress.
The bottom line is that RBI preserved a credible long-term narrative through Burger King's acceleration, falling leverage, and steady buybacks. The quarter also revealed decelerating profit growth, a stalled Popeyes turnaround, and softer international trends. A modest beat against consensus, supported by tariff refunds and a GAAP tax benefit, does not resolve those concerns. Bears have legitimate ammunition until Popeyes stabilizes and organic AOI growth moves back above the 8% target.
Read our earnings preview for Restaurant Brands International Inc.: https://www.earningswhispers.com/article/QSR/21123
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| 7 hours | |
| 7 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
