Norwegian Cruise Line Delivers First Clean Beat-And-Raise Of Its Turnaround, But Earnings Still Shrink And 2027 Bookings Lag
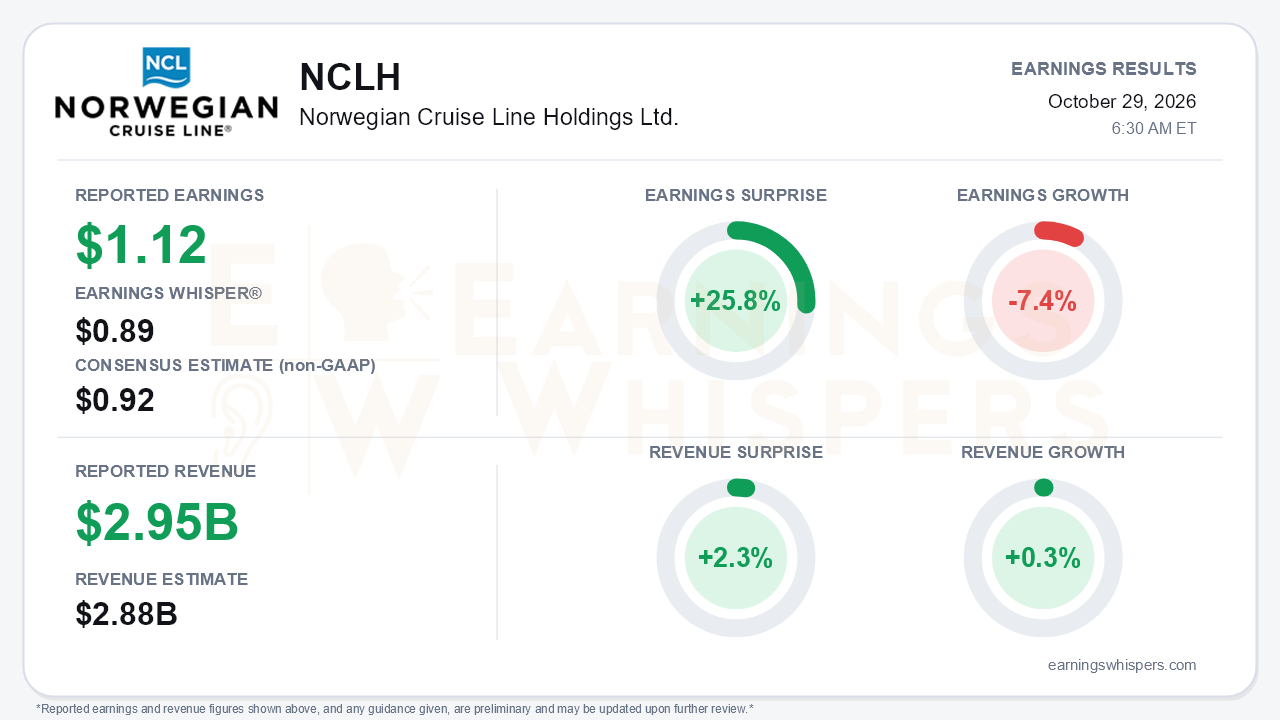
Norwegian Cruise Line Holdings finally gave turnaround skeptics something they were not positioned for: a clean beat-and-raise. Adjusted EPS of $1.12 topped the $0.92 consensus by 25.8% and cleared the $0.89 Earnings Whisper number. Revenue of $2.947 billion beat the $2.88 billion estimate by 2.3%. Management raised full-year 2026 adjusted EPS guidance to roughly $1.70 from about $1.50 and issued its first explicit 2027 outlook, calling for Net Yield growth of 1% to 2%. But the beat came against a lowered bar. Adjusted earnings still fell 7.4% year over year, revenue grew only 0.3%, and the raised 2026 targets sit well below the $2.95 billion adjusted EBITDA and $2.38 EPS management guided to at the start of the year. That is the central tension. The trajectory has turned upward, but the level of profitability remains impaired.
The quality of the beat deserves scrutiny in both directions. Operationally, the upside was real. Constant-currency Net Yield fell 6.7%, about 220 basis points better than the guided 8.9% decline. Adjusted net cruise cost excluding fuel per capacity day fell 2.3%, compared with guidance of down 0.9%. Adjusted EBITDA of $937 million exceeded guidance by $63 million, although it was still below the $1.02 billion reported a year earlier. The revenue mix is revealing. Onboard and other revenue rose nearly 13% to $1.0 billion, while passenger ticket revenue fell about 5% even though capacity days rose 5.4%. Guests are spending once aboard, but Norwegian is still discounting to fill ships. On a GAAP basis, EPS rose to $1.07 from $0.86. That improvement owed much to lower interest expense, after last year's debt-extinguishment charges, and to a sharply lower diluted share count. It does not reflect stronger operating income, which fell to $624 million from $749 million.
The call marked a clear shift in tone. Management moved from describing problems as 'self-inflicted' earlier in the year to 'highly confident' about 2027. The guidance trail now points up after three consecutive calls of cuts or resets. Full-year Net Yield guidance moved to about -4.4% from roughly -5%. The cost outlook improved for a third straight quarter. Identified 2026 savings climbed to $325 million, and the company added another roughly $100 million in run-rate savings tied to air optimization and promotional changes. Occupancy of 106.5% beat the 104% guide. Pricing for 2027 is ahead of last year in every quarter. However, management attributed much of the Q3 upside to pent-up close-in demand that it explicitly declined to extrapolate. The fourth-quarter yield guide of about -6.5% was held rather than raised, and the company expects a fourth-quarter adjusted loss of roughly $0.12 per share.
The catalyst list is longer than it has been all year. The Great Tides Waterpark opened at Great Stirrup Cay, and expected island visitors for 2027 rose to about 1.4 million. Seven Seas Prestige set a Regent launch-day booking record. A new Norwegian Cruise Line creative platform launches with wave season in January, base-loading now covers most second-half 2027 and all 2028 sailings, and an investor day is planned for the first half of 2027. Bears still have legitimate ammunition. The booked position for the next 12 months remains below the company's optimal range. First-half 2027 bookings trail last year, and base-loading has yet to pull second-half 2027 ahead of the curve. Net leverage stands at 5.5x, and the new $950 million notes carry an 8.75% coupon. Two ship deliveries in 2027 will add debt before their EBITDA annualizes. The departure of CFO Mark Kempa at year-end adds execution risk in the middle of a balance-sheet repair.
The market entered the report treating Norwegian with considerable suspicion. Shares closed at $16.06 ahead of the release, down 15.3% since the opening following the July report and about 14.5% below the $18.78 200-day moving average. The stock set a 52-week low of $13.63 on September 23. It had since recovered about 18% off that low but remained 22% below the August high of $20.61. Investor sentiment stayed negative and edged slightly lower, to -0.45 from -0.41, a modest change that suggests expectations were not improving into the print. The Earnings Whispers trend readings are mostly negative, with price and momentum weak, although the AVWAP trend is positive.
The bottom line is that Norwegian delivered the first quarter of its turnaround in which results, guidance, and tone all moved in the right direction. The 2027 yield outlook gives investors a concrete benchmark for the first time. Still, earnings are shrinking year over year, ticket pricing remains under pressure, and part of the beat rested on close-in demand management itself will not count on. For a stock trading well below its 200-day average with sentiment still negative, the report shifts the debate from whether the turnaround is failing to whether early 2027 bookings can catch up to pricing. That answer will not arrive until wave season.
Read our earnings preview for Norwegian Cruise Line Holdings Ltd.: https://www.earningswhispers.com/article/NCLH/21107
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 10 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 |
