Monster's Slowing Summer Tests Whether International Surge Can Outrun Rising Costs
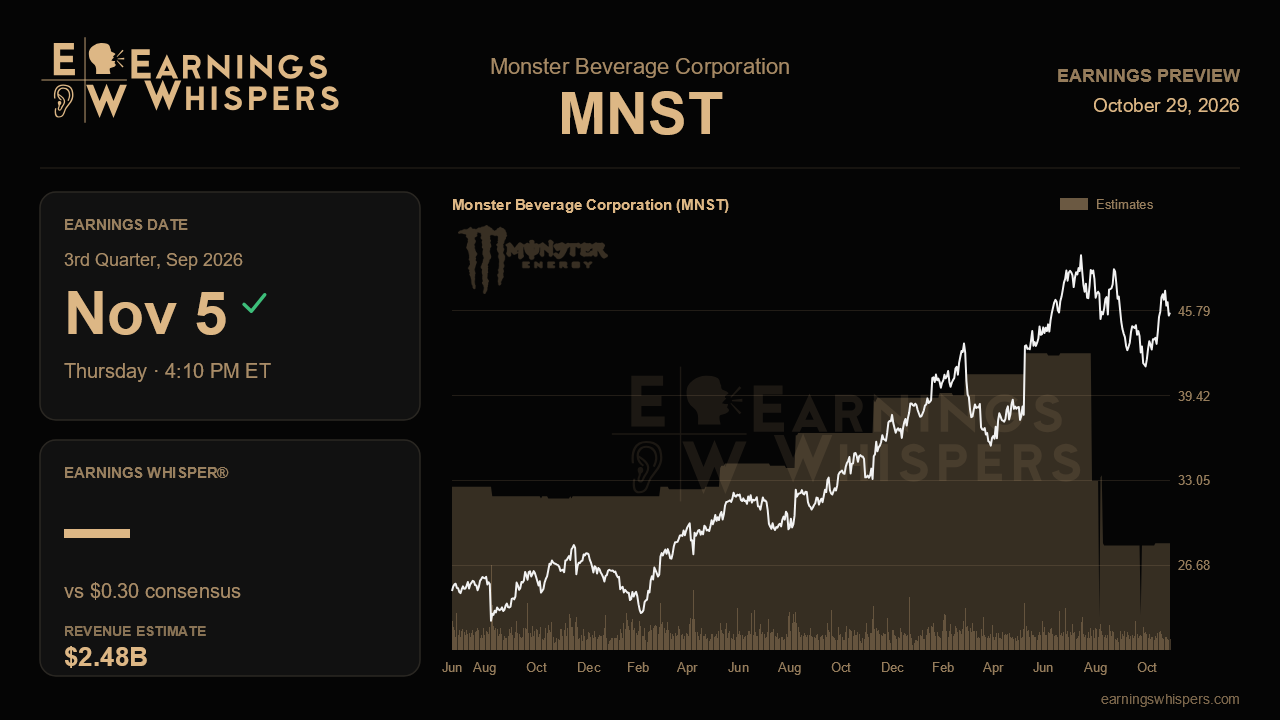
Monster Beverage enters its third-quarter report with an awkward contrast. Its last quarter was the best in its history, with record sales and a notably more confident management team. Yet the stock has slipped since then, and the one forward-looking number management offered, July sales growth of about 14% on a currency-neutral basis excluding alcohol, pointed to a cooler pace than the 20%-plus surge of the first half. The report due after the close on November 5 should show whether July was a pause or the start of a lower trajectory.
The Street expects revenue of about $2.48 billion, up 12.9% from a year ago. That is solid for a staples company, but it is a clear step down from the 20.2% growth Monster posted in the second quarter and slightly below that quarter's record $2.54 billion. In other words, analysts have largely taken management's July data at face value. The headline earnings comparison looks alarming, with consensus of $0.30 a share implying a 46% decline, but that is mostly an artifact of the two-for-one stock split that took effect August 11. Adjusted for the split, last year's $0.56 is roughly $0.28, so the estimate actually implies high single-digit growth and earnings roughly flat with the second quarter on a per-share basis. Monster does not issue formal guidance, so the bar is set by consensus and by the July run rate.
International is where the bullish case lives. Sales outside the U.S. jumped 34.6% last quarter and reached 46% of the total, powered by China, India, Brazil and Latin America, while EMEA gained meaningful value share. Management framed this as sustainable, tied to closer coordination with the Coca-Cola bottling system. Confirmation would look like international growth staying comfortably in the high 20s or better, continued share gains in Europe, and early evidence from the Monster Green vending rollout with Coca-Cola bottlers in Japan. A sharper fade abroad, or a lingering slump in South Korea, where bottler inventory adjustments pushed sales lower, would challenge the claim that the expansion is structural rather than a strong half-year.
Margins are the second swing factor, and they could make an in-line sales quarter feel better or worse. Gross margin improved to 55.9% on pricing and mix, but management warned that aluminum and Midwest premium costs would creep higher through year-end, and freight and fuel lifted distribution expense to 4.7% of sales. Selling expense also jumped to 10.6% of sales on heavy sponsorship and brand spending. Since the newly announced selective U.S. price increases do not take effect until the fourth quarter, this report gets the cost pressure without the pricing relief. Holding gross margin near 55% and showing some discipline on marketing would go a long way toward reassuring investors that the earnings estimate is achievable. Continued shrinkage in the alcohol segment is a smaller drag but remains an irritant.
Sentiment has cooled along with the stock. Pre-earnings sentiment has slipped to modestly bearish from modestly bullish a quarter ago, and shares have fallen 2.6% since the last report, trailing the S&P 500 by nearly three points. At $45.66, the stock sits in the middle of its post-earnings range of $41.05 to $49.24 and above its 200-day moving average, hardly a picture of capitulation but not of enthusiasm either. Commentary on new channels such as the Marriott foodservice partnership and the Big 12 sponsorship, plus any preview of the December 1 investor meeting, could help shift that tone.
Ultimately, the quarter comes down to whether growth stabilizes in the low to mid teens with margins intact, or whether July's deceleration deepens just as costs rise. If international momentum holds and gross margin resists aluminum and freight pressure, the more confident story from last quarter remains intact heading into the fourth-quarter price increases. If not, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-04 | |
| Sep-28 | |
| Sep-28 | |
| Sep-28 | |
| Sep-23 | |
| Sep-21 | |
| Sep-19 |
