Hilton Grand Vacations' 299% Beat Is A Construction-Accounting Mirage; Contract Sales Slide 11% And EBITDA Guidance Is Cut
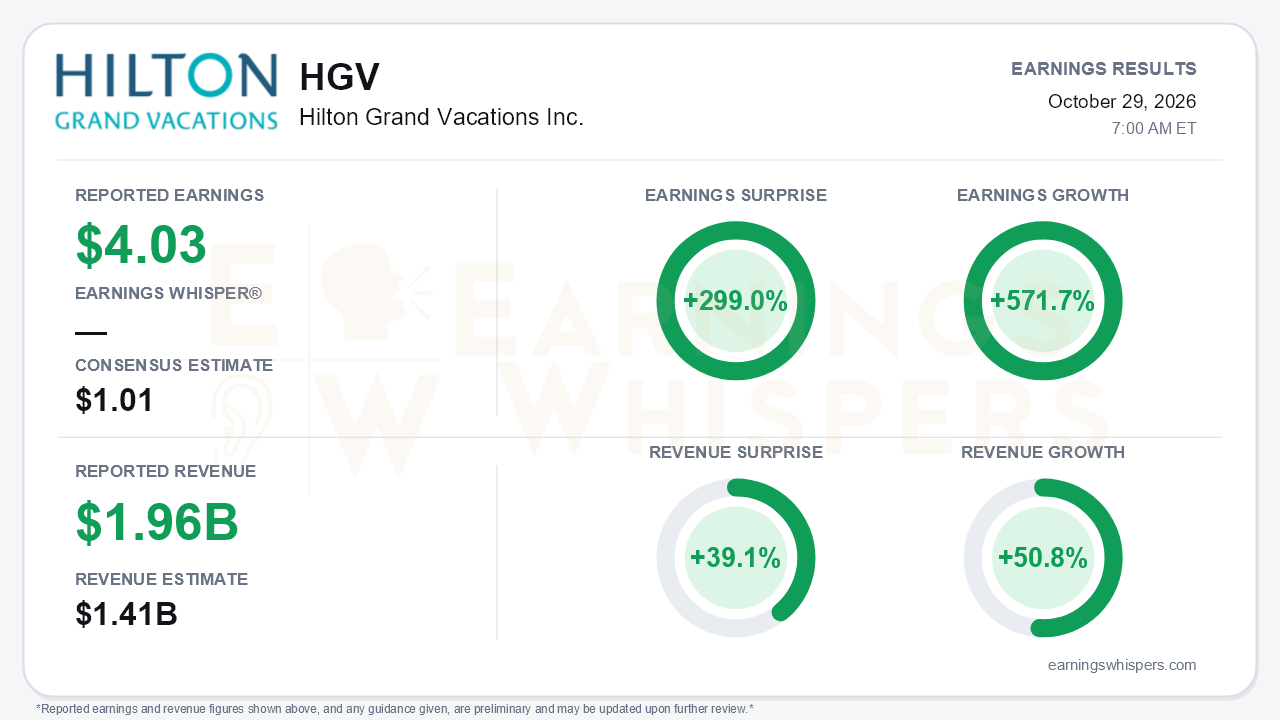
Hilton Grand Vacations posted adjusted earnings of $4.03 per share on revenue of $1.961 billion. That beat consensus of $1.01 by 299.0% and the $1.41 billion revenue estimate by 39.1%. Earnings grew 571.7% year over year and revenue rose 50.8%. Those figures say almost nothing about how the business performed. The quarter absorbed a $296 million net construction recognition tied to the completion of Ka Haku, the company's new Hilton Club in Waikiki, worth $3.76 per share. On the revenue line, $536 million of previously deferred VOI sales flowed through at once, against a $99 million deferral in the year-ago quarter. Strip that timing benefit away and the core story is the opposite of the headline. Sales execution deteriorated, and management cut full-year guidance. That is the central tension.
The quality of the beat deserves further scrutiny beyond the Hawaii recognition. HGV changed its allowance methodology for financing receivable losses during the quarter. It combined acquired portfolios into a single static pool stratified by FICO score and equity percentage, which produced a $55 million reduction in the allowance. As a result, the provision fell to 12.5% of owned contract sales, from 17% in the second quarter. Call commentary indicated the old methodology would have implied a provision of roughly 20%. Even the roughly 4% growth in EBITDA excluding deferrals and recognitions, which management cited on the call, leaned on that accounting change. Meanwhile, the operating metrics were plainly weak:
- Contract sales fell 11.0% to $807 million, worse than the mid-single-digit decline guided last quarter.
- Volume per guest dropped 12.5% to $3,406.
- Fee-for-service mix fell to 11.5% of contract sales from 17.2%.
The call revealed a steady erosion that has now become a reset. The contract sales trajectory went from slightly down in the first quarter to down 3% in the second and down 11% in the third. VPG declines widened from 8% to 9% to 12%. Full-year adjusted EBITDA guidance, excluding deferrals and recognitions, now stands at $1.165 billion to $1.180 billion. That compares with $1.225 billion to $1.265 billion previously, a figure that was raised in the first quarter and reaffirmed in the second. Management also lowered several sales outlooks:
- Full-year contract sales are now expected down mid-single digits, versus flat to down slightly.
- Full-year VPG is now expected down high-single digits.
- Fourth-quarter VPG, which was framed as 'solid growth' on the first-quarter call, is now expected down mid-single digits.
CEO Mark Wang's tone shifted accordingly. He said the company is 'not satisfied' and that summer execution initiatives are 'taking longer to ramp than we anticipated.' Notably, demand at the top of the funnel held: tour flow rose 1.7%. The problem is conversion. Above-normal sales-staff turnover and competitive poaching forced higher compensation. Sales and marketing expense reached 51% of contract sales, up 440 basis points, and management expects that pressure to persist into the fourth quarter.
The call did preserve some credible offsets. Financing remains the bright spot, with revenue up 16% to $149 million and margins around 64%. Credit metrics look healthy: Bluegreen delinquencies are back to 2022 levels and Diamond's are at a five-year low. Management cut 2026 inventory spend by $90 million to about $285 million, which should support cash flow. It plans two fourth-quarter securitizations and still targets $600 million of buybacks for the year. Management also described August as the trough, with September and October improving. The remediation plan includes:
- A sales leadership change, with Mike Riley promoted to chief sales and marketing officer.
- More than 430 experienced sales hires, about 165 of them former HGV reps.
- Revised incentive plans and new price tiers aimed at new-buyer conversion.
Bears have legitimate ammunition, however. Leadership transitions carry execution risk. Third-quarter buybacks slowed to $110 million from a $150 million run rate, and free cash flow conversion was only about 20%. Full-year cash targets now hinge on securitization timing. Management also flagged that consumer pressure, higher rates and fuel costs are marginally affecting purchase decisions and funding costs. Club membership slipped to 715,888 from 721,488 a year earlier.
The market had largely anticipated the disappointment. Shares have fallen 26.0% since opening at $48.00 after the July report, to $35.53. They trade 20.5% below the 200-day moving average and only 4.5% above the October 5 low of $33.99, a 52-week low set during the quarter. Investor sentiment deteriorated meaningfully, from -0.11 to -0.48. Price, momentum and AVWAP trend readings remain negative. The positive sequential-growth reading largely reflects the lumpy construction recognition rather than organic improvement.
The bottom line is that HGV's eye-popping beat is an artifact of construction timing and an allowance methodology change, while the operating engine of contract sales, VPG and sales efficiency weakened more sharply than guided. The guidance cut and leadership shake-up acknowledge the problem, and the financing book and tour flow offer a foundation for recovery. But with shares already pinned near their lows, the next leg depends on whether the September-October improvement becomes durable conversion gains rather than another quarter of promises.
Read our earnings preview for Hilton Grand Vacations Inc.: https://www.earningswhispers.com/article/HGV/21079
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| Oct-21 | |
| Oct-15 | |
| Oct-07 | |
| Oct-02 | |
| Aug-27 | |
| Aug-24 | |
| Aug-20 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 |
