Bloomin' Brands Must Prove Outback Traffic Can Follow Its Margin Gains
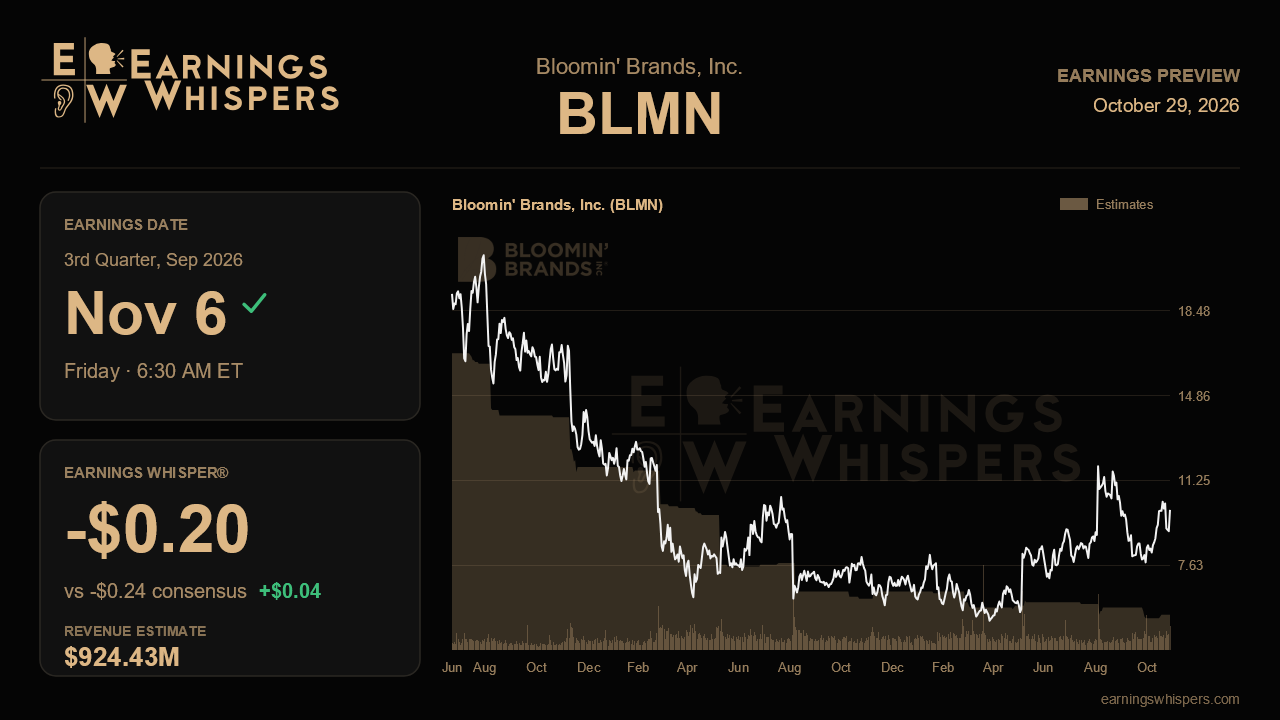
Bloomin' Brands heads into its third-quarter report with an awkward split between the business and the stock. Last quarter, management raised its full-year profit outlook for the first time in the Outback turnaround, citing richer menu mix and tighter cost control. Since then, the shares have fallen 17.6% while the S&P 500 was roughly flat. That gap suggests the market doubts the upgrade will last, and Thursday's release before the open is the first real chance to settle the question.
The headline numbers will look ugly, but that was expected. Wall Street projects a loss of 24 cents a share, compared with a loss of 3 cents a year ago, on revenue of about $924 million, essentially flat with last year. Management guided to a loss of 22 to 27 cents. The consensus sits near the midpoint after drifting down from a 19-cent loss when the guidance was issued. Part of the damage is a tax quirk: a negative full-year tax rate forces a third-quarter tax expense. The whisper number of a 20-cent loss is slightly more forgiving than consensus, so a result at the better end of guidance would not surprise people paying close attention. Because the quarter carries so much accounting noise, the more useful figure may be whether the company reaffirms or tightens its full-year range of 90 cents to $1.00 per share.
The central operating question is traffic. In the second quarter, guest counts fell 2.8% at Outback and 2.5% at Carrabba's. Management described this as a deliberate choice not to repeat discount-heavy third-party delivery promotions from last year. That logic holds only if improving guest scores eventually turn into more visits. Outback has posted four straight quarters of gains in service, atmosphere, value and intent to return. The four-tables-per-server model and the chargrill expansion are now fully in place. The heavier second-half marketing push, roughly $15 million in extra spending weighted toward Outback, is also now flowing. If traffic is still sliding at a similar rate with all of those levers working, the turnaround story starts to look like a pricing and mix story rather than a demand recovery. Even a narrowing decline would support management's case.
Mix is the other pillar to test. Management now expects mix to add about a percentage point to sales this year, a sharp reversal from the two-point drag it assumed last winter. Guests trading up to premium steaks, combos, sides and desserts allowed the company to cut its planned food investment from $50 million to $36 million. Evidence that this trade-up continued, rather than reflecting a single strong spring, would make the raised outlook more credible. Investors should also check whether the full-year U.S. comparable sales target of 1% to 2% still holds.
Costs are the swing factor on margins. Commodity inflation ran at 5.7% last quarter, ahead of pricing of roughly 4.5%. Continued food-cost pressure combined with increased marketing could squeeze the operating margin gains seen in the second quarter, when adjusted margin widened half a point to 4%. Progress toward roughly 85 Outback remodels this year and continued strength at Bonefish, where comparable sales rose 8.1% last quarter, would add useful support.
Sentiment has cooled from modestly bullish before the last report to mildly bearish now, so the bar is lower than it was in the summer. The stock trades near $10, comfortably above its 200-day average of about $7.85. It sits in the middle of a wide post-earnings range between roughly $7.66 and $12.63. Ultimately, the report will be judged on one issue: whether better service, refreshed dining rooms and new advertising are beginning to bring guests back. If they are, the raised guidance looks durable. If traffic remains stubbornly negative, investors may conclude that margin gains are masking a turnaround that has yet to win back customers.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-16 | |
| Oct-12 | |
| Sep-29 | |
| Sep-28 | |
| Sep-11 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
Steakhouse Stock Soars 40% As Diners Fork Over More For Dishes
BLMN +32.85%
Investor's Business Daily
|
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
Bloomin' Brands Raises Earnings View on Higher Profit, Check Size
BLMN +32.85%
The Wall Street Journal
|
