Linde Posts Record Quarter, But An FX-Aided Guidance Raise And A Softer Q4 Outlook Temper The Beat
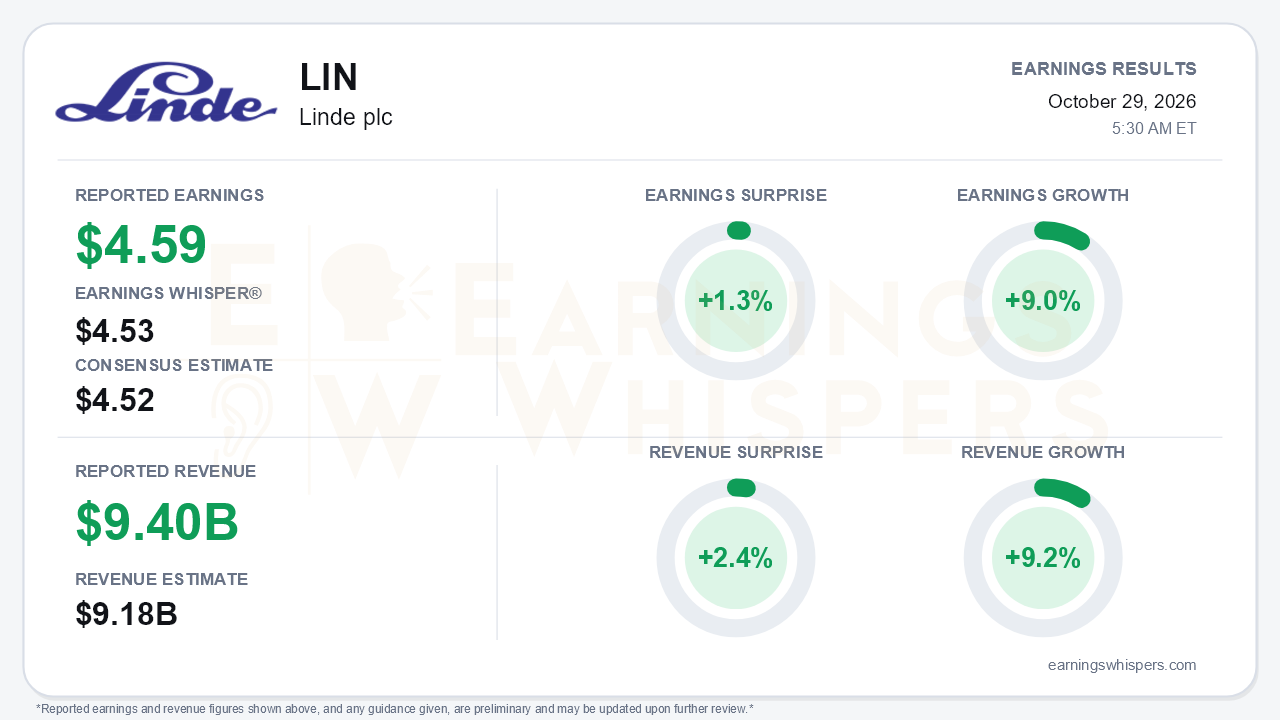
Linde delivered a record third quarter, but the details look less impressive than the headline. Adjusted EPS of $4.59 beat the $4.52 consensus and the $4.53 Earnings Whisper number by 1.3%, and grew 9.0% year over year. Revenue of $9.404 billion topped the $9.18 billion consensus by 2.4% and rose 9.2%. Both sales and EPS were company records, and EPS cleared management's own $4.45-$4.55 guidance range. The central tension is that demand is clearly improving while margins are stalled. At the same time, the fourth-quarter outlook implies that earnings growth will slow from here, which helps explain why the guidance came in below estimates despite a nominal full-year raise.
The beat deserves scrutiny. Underlying sales rose 5%, with 3% from price and 2% from volume, while currency added about 1 point. Part of the price gain was not organic strength. In the Americas, roughly 2 of the 6 points of pricing were inflation cost recovery, and management put the underlying regional run rate closer to 4%. According to the call, the quarter also included about a point of one-off equity income from a customer contract true-up that will not repeat. On a GAAP basis, the picture was weaker. EPS fell 11% to $3.66 and net income dropped 12%. The main drivers were a $425 million restructuring charge, up from $230 million in the fourth quarter of 2025, and Linde AG purchase-accounting effects. Cash generation remained solid. Operating cash flow rose 8% to $3.2 billion, and $1.69 billion went back to shareholders.
The revenue story is accelerating. Electronics grew 15%, supported by roughly $2 billion of projects under construction in the U.S., Korea and China, and management expects double-digit growth to continue. Chemicals & energy jumped 12%, up from 3% in the first quarter and low single digits in the second. That gain came from Gulf Coast and China feedstock advantages and from refiners' hydrogen demand amid the Middle East conflict. Global price improved to 3% from 2% in each of the first two quarters. Margins, however, did not follow. The adjusted operating margin of 29.4% was 30 basis points lower year over year and only flat excluding cost pass-through. Earlier in the year, management had talked about margin expansion above its 30-50 basis point annual range, so this result falls short of those commitments. APAC and EMEA margins both contracted, and the Americas, up 50 basis points, carried the improvement.
Guidance is where bears have legitimate ammunition. Full-year adjusted EPS guidance rose to $17.82-$17.92 from $17.70-$17.90. However, the assumed currency tailwind doubled from 1% to 2%, which leaves the underlying outlook essentially unchanged. The fourth-quarter range of $4.40-$4.50 implies growth of 5-7%. That is below the 9% just reported and continues a run of shrinking quarterly growth guides, from 8-10% to 6-8% and now 5-7%. The outlook assumes no restructuring benefit, the absence of the one-off equity income, and about a 1% sequential FX headwind. Other pressures remain:
- Europe is flat underlying, with what management called "no catalyst."
- China steel is down 2.5%.
- North American and European energy inflation is being recovered with a three- to six-month lag.
- Rare gas sales for satellite propulsion have softened.
The sale-of-gas backlog also slipped to about $8 billion from a record $8.1 billion.
The forward catalysts are real but back-end loaded. Restructuring savings are expected to reach full run-rate in the second half of 2027, on a 1.5-2 year payback. Lincare, which drags full-year EPS growth by roughly 1.5-2 points, has been moved into the Other segment under the CFO while strategic alternatives are evaluated, though an exit is not assured. Woodside's air separation unit started in the third quarter, with ATR trains due in the first half of 2027. That customer, however, is itself under strategic review. The sale-of-plant backlog of nearly $3 billion and new long-term helium contracts add visibility. Notably, the CEO opened by acknowledging that second-quarter results were "not up to the expectation of our owners," a more defensive tone than earlier in the year.
The market setup heading into the report was constructive, which raises the bar. Investor sentiment improved from roughly neutral (0.01) to modestly positive (0.13). Shares closed at $508.16 the day before the release, up 7.0% since the open after the July report. That price was 3.3% above the 200-day moving average and within 1% of the inter-earnings high of $512.49. The stock had rallied nearly 12% from its September low. Price and AVWAP trend readings are positive, while sequential growth and momentum are neutral. A stock trading near the top of its range does not leave much cushion for an underlying outlook that is essentially unchanged.
The bottom line is that Linde's quarter showed strengthening demand, especially in electronics and U.S. energy, but no progress on margins. The guidance raise owes more to currency than to the business, and the fourth quarter points to slower growth. The restructuring and Lincare review could reshape the 2027 earnings path, but investors are being asked to wait for those benefits after a pre-report rally.
Read our earnings preview for Linde plc: https://www.earningswhispers.com/article/LIN/21096
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| 8 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 |
