WTW's Margin Engine Delivers 18% Adjusted EPS Growth, But Missed Whisper And Trimmed Growth Guides Point To Slowing Organic Momentum
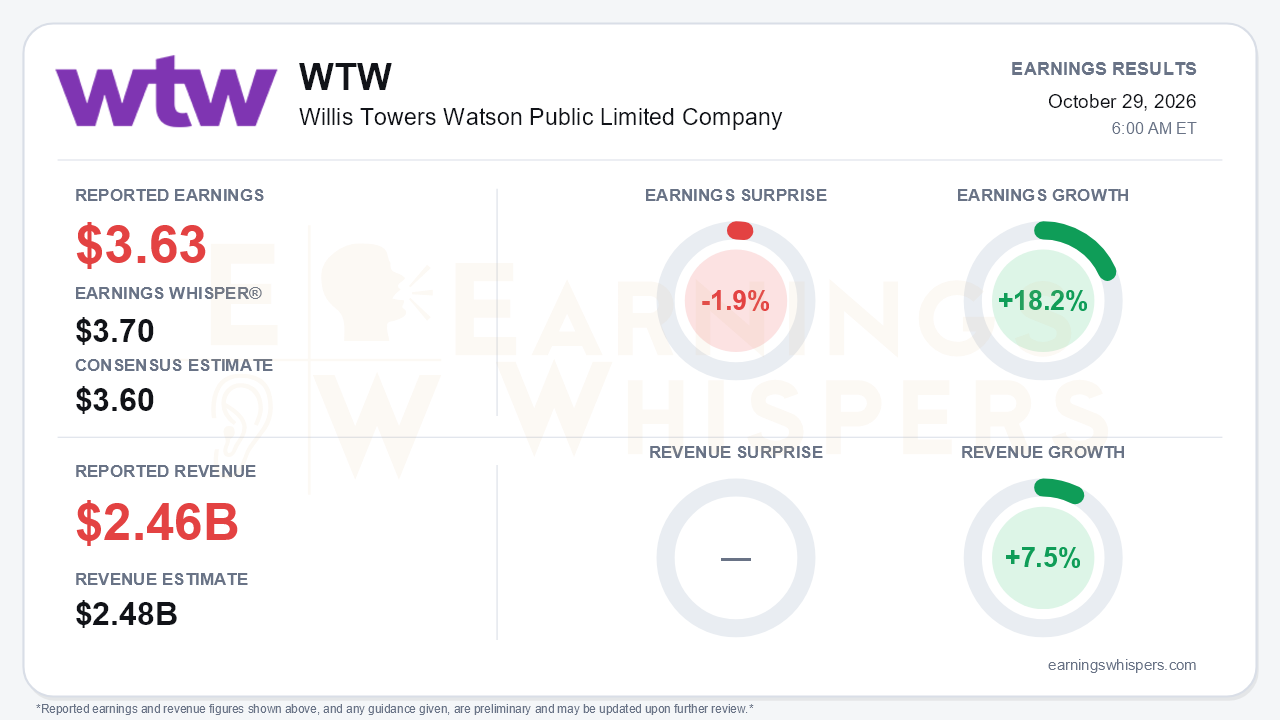
WTW posted adjusted earnings of $3.63 per share for the September quarter. That edged past the $3.60 consensus but fell 1.9% short of the $3.70 Earnings Whisper number. Revenue of $2.46 billion missed the $2.48 billion consensus by 0.8%. Earnings grew 18.2% year over year, in line with the 17% and 19% gains of the prior two quarters, and revenue rose 7.5%. The central tension is that the margin story keeps strengthening while the top-line story keeps softening. Management cut organic growth expectations across several businesses even as it delivered another quarter of operating leverage.
The beat deserves scrutiny. Adjusted operating margin expanded 150 basis points to 21.9%, faster than the 100-basis-point gain in Q2 and 70 points in Q1. Roughly 50 basis points of that came from a $13 million gain on an office sale, which leaves the underlying improvement closer to Q2's pace. Book-of-business settlements also rose to $20 million from $6 million, and the release explicitly credits them for much of Risk & Broking's 100-basis-point margin gain. Below the operating line, the diluted share count fell to 94 million from 98 million, adding meaningful per-share lift.
On a GAAP basis the picture is far less flattering. Diluted EPS rose just 4% to $3.24, and GAAP operating margin fell 90 basis points to 17.4%. Transaction and program expenses jumped to $42 million from $2 million, tied to the Newfront and Cushon deals and the Propel AI plan, and restructuring added $14 million. Free cash flow was a genuine bright spot, reaching $1.06 billion for nine months versus $838 million, although that figure includes $29 million of building-sale proceeds.
The call is where the setup shifted. Organic growth was 4%, compared with 5% in Q2 and 6% in Q4 of last year. Acquisitions supplied another 4 points of reported growth, mostly from Newfront. Risk & Broking slowed to 5% organic from 7% in Q2, or 4% excluding settlements and interest. Management now expects enterprise organic growth at the lower end of mid-single digits and made these segment cuts:
- **Health, Wealth & Career:** lowered to low-to-mid single digits.
- **BD&O:** lowered to flat from low single digits after three large clients postponed implementations.
- **ICT:** lowered to low single digits on consulting deferrals, despite 5-6% prints earlier in the year.
- **Career:** narrowed to low single digits; Q3's 9% was helped by timing that unwinds in Q4.
Commercial rates, particularly in large and complex property, continue to soften. That is a slow-burn headwind for the broking franchise.
There are offsets. Health grew 6% with its high-single-digit outlook intact, and CRB North America grew at a double-digit pace. A record individual marketplace enrollment cycle of more than 100,000 retirees, with 75,000 deferred into 2027, gives BD&O a credible rebound pipeline. Management reaffirmed the Propel framework: about $625 million of cash costs, $350 million of net run-rate savings and roughly 30% adjusted operating margin in 2028. That said, only $18 million of savings has been actioned so far, so the target remains largely a promise. Other new catalysts include:
- Willis Re's acquisition of BMS Re's U.S. business.
- Full ownership of the Middle East joint venture.
- The VIA Retirement launch.
- Expanded agentic AI deployments.
- A buyback target raised to more than $1 billion.
The BMS deal comes with a caveat: Willis Re is expected to remain an EPS drag into 2027.
Investor sentiment heading into the report improved modestly, from slightly negative to slightly positive. That signals a roughly neutral crowd rather than an enthusiastic one. Shares closed at $321.63 before the release, down 5.2% since the opening after the July report. The stock had rallied to a 52-week high of $351.51 in late August, slid to $283.42 in early October, and recovered about 13.5% off that low into earnings. It sits 8.3% above its 200-day moving average. The Earnings Whispers trend readings are mostly positive, with price, sequential growth and AVWAP all constructive. Still, the stock entered the print having already rebuilt a good portion of its October drawdown, which leaves less cushion for a report that missed the whisper and lowered growth expectations.
The bottom line is that WTW is increasingly an execution-and-efficiency story rather than a growth story. The margin and cash-flow progress is real, and the 2028 target gives bulls a clear roadmap. However, this quarter's margin beat leaned on a property gain and settlement activity. Organic growth is decelerating, and four segment guides moved lower in a single quarter. Until BD&O implementations resume and rate softness stabilizes, bears have legitimate ammunition. Investors are being asked to pay for cost savings that are still mostly ahead.
Read our earnings preview for Willis Towers Watson Public Limited Company: https://www.earningswhispers.com/article/WTW/21154
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 |
