Essent's Q3 Test: Can Investment Income And Lean Costs Offset A Stalled Mortgage Book?
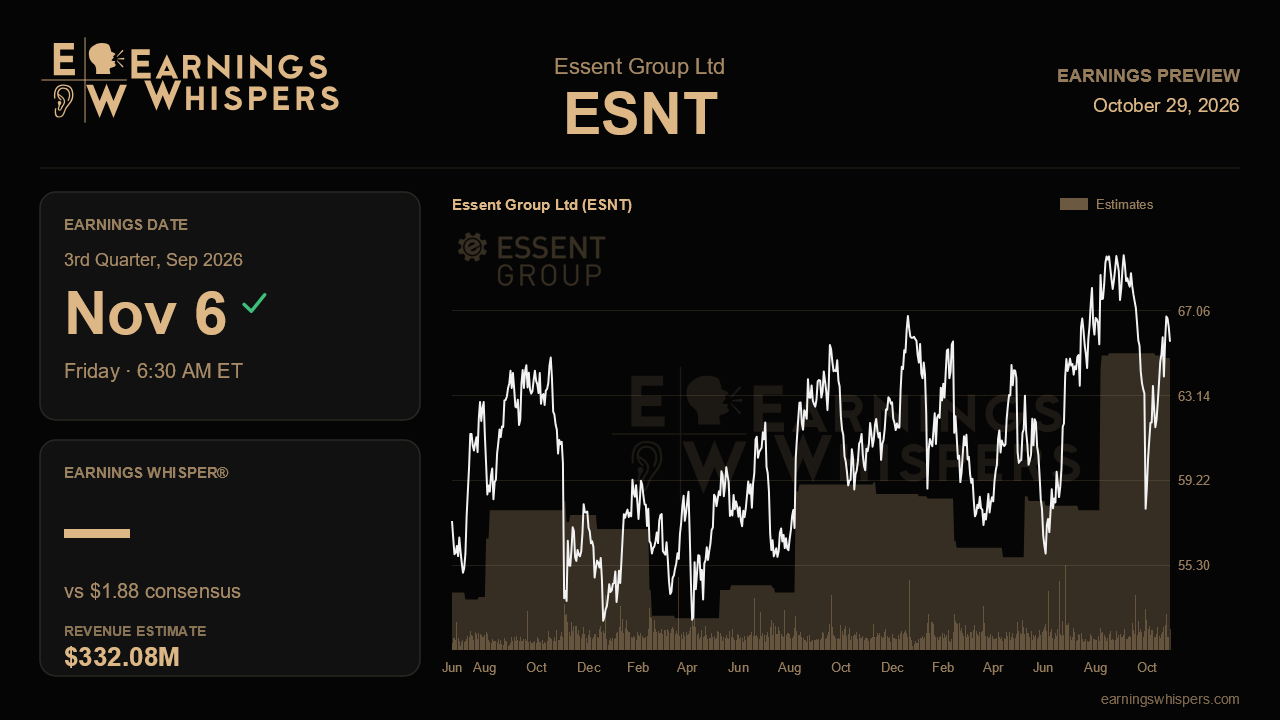
Essent Group heads into its third-quarter report with an unusual setup: Wall Street is bracing for earnings to fall from the prior quarter even while it expects solid year-over-year growth. That gap says a lot about how much of the second quarter's strength analysts consider repeatable. Last quarter the mortgage insurer posted $2.08 a share, helped by a sharp drop in its expense ratio, a lighter loss provision and nearly double the income from its alternative investment portfolio. The core insurance book, meanwhile, barely grew. The coming report should show whether those earnings tailwinds can last while the underlying franchise stays in what management described as a growth pause.
Consensus calls for $1.88 a share on revenue of $332.1 million when results arrive before the open on November 6. That would be up 12.6% from $1.67 a year ago, with revenue up 6.5% from $311.8 million, which is healthy for a company whose insured portfolio is roughly flat. Against the second quarter, though, the forecast implies EPS down about 10% and revenue down roughly $30 million. In effect, analysts are treating last quarter's $19.4 million from other invested assets and the 14.8% mortgage insurance expense ratio as at least partly one-off. There is no fresh company guidance to compare against, so the Street's caution reflects its own judgment rather than anything management signaled.
That makes the quality of the earnings mix the main thing to watch. Management has built its strategic investment portfolio to about $450 million, roughly 7% of investments, and committed another $100 million in the first half. Investment yield climbed to 4.9% from 4.2% a quarter earlier. If alternative investment income holds near second-quarter levels and the expense ratio stays well below the 17.4% seen in the first quarter, the $1.88 bar looks modest. If alternative returns swing back toward the roughly $10 million of the first quarter, the conservative forecast will prove justified.
The insurance engine is the bigger long-term question. Twelve-month persistency, the share of policies that stay on the books, has slipped every quarter, from 86% to 84%. The base premium rate edged down to 40 basis points, and management warned it may keep drifting lower for years. Insurance in force sat near $250 billion, up only about 1% from a year earlier, and management pushed any affordability-driven recovery out to the end of the decade. A modest uptick in new business premium, which rose 10% last quarter as Essent took on somewhat more risk in higher debt-to-income and loan-to-value loans where it has pricing power, would help. Further erosion in persistency or premium rate would challenge the view that margins can carry the story while volume waits.
Credit is the quiet swing factor. The default rate held at 2.53%, but the book continues to age toward the 36 to 60 month window when defaults typically peak. A loss provision near last quarter's $29.4 million would support the steady-earner case, while a jump back toward the first quarter's $37.6 million would weigh on results. Expect questions on VantageScore adoption, which management raised last quarter as a possible adverse-selection risk before playing it down, and on progress with the new Title system that recently started running live.
Sentiment has warmed noticeably, moving from slightly bearish before the last report to clearly bullish now, yet the stock has done almost nothing since then, rising 0.1% while the S&P 500 gained 0.2%. At $65.63 the shares sit above their 200-day average of $62.85 and in the upper half of the post-earnings range, but still about 7% below the $70.37 high, so a breakout is not imminent. With the stock trading only slightly above book value of $63.01, continued compounding of book value and buybacks backed by about $302 million of remaining dividend capacity remain central to the investment case. The real test is whether Essent can keep growing book value per share at a double-digit pace while its insurance portfolio stays flat.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-23 | |
| Oct-16 | |
| Aug-31 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-17 | |
| May-08 | |
| May-08 | |
| Apr-17 | |
| Mar-20 | |
| Mar-20 | |
| Mar-19 |
