Emera's Q3 Tests Whether Asset-Sale Progress Can Finally Reach The Earnings Line
Emera heads into its third-quarter report with a credibility gap of a particular kind. Management spent the summer ticking off strategic milestones, from the Grand Bahama Power sale to regulatory approval of the New Mexico Gas divestiture and a move by Moody's to a stable outlook. Yet the stock has slipped since the last report, as if the market is waiting for proof that a simpler, less indebted Emera can also grow earnings. This quarter is the first real chance to see that in the numbers.
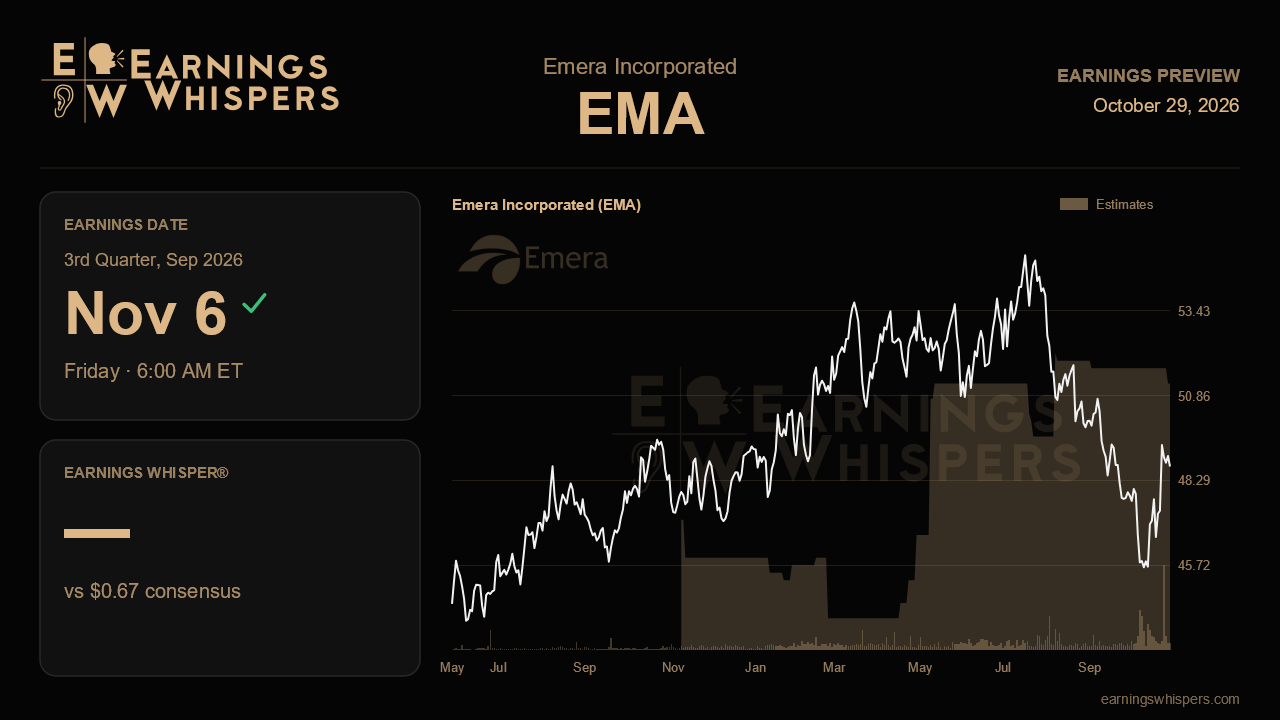
The bar is modest. Consensus calls for earnings of $0.67 a share, about 4.7% above the $0.64 earned a year ago. For a regulated utility that is ordinary growth, and it sits just below the 5% to 7% annual EPS growth management reaffirmed through 2030. That matters because the prior quarter went the other way. Adjusted EPS fell 10 cents from a year earlier, and year-to-date results were roughly flat. Management blamed tough comparisons with a record 2025, when new Tampa Electric rates and an unusually strong AmeriEnergy marketing business lifted results. A return to positive growth would support the view that the soft patch was about comparisons, not the underlying business.
Several moving parts make this quarter harder to read than usual. New Mexico Gas is expected to have closed in August, so its contribution drops out for part of the period. The $650 million to $700 million in after-tax proceeds goes to paying down holding company debt, and that interest saving may not show up right away. Corporate interest expense was also inflated by dual financing during the mid-year hybrid refinancing, and investors should look for signs that this cost is easing. Tampa's storm surcharge ended August 1, cutting residential bills by roughly 11% to 12%. The change should be revenue-neutral, but it will make reported revenue look weaker. Nova Scotia Power, meanwhile, should finally have a full quarter of the new rates that took effect May 1 after a regulatory delay, which is a clean test of whether that lag has been fixed.
The longer-term story depends on demand and capital deployment. Emera has lifted its 2026 capital plan to a record of about $4 billion, part of a $20 billion five-year program meant to support 7% to 8% rate base growth. In Florida, data center interest has grown from loosely optimistic talk to about 1,300 megawatts of interested counterparties, with 300 to 500 megawatts seen as serviceable in the near term. A large-load tariff under SB 484 was due to be filed by October 1. Confirmation that it was filed, along with any sign that interest is turning into signed load, would add substance to the growth story. AmeriEnergy, guided to $60 million to $80 million this year against a traditional range of $15 million to $30 million, is another swing factor. Progress on the $700 million Nova Scotia thermal asset securitization, targeted for year-end, also deserves attention.
Sentiment has moved from clearly bearish before the last report to roughly neutral now, so the crowd has softened rather than turned optimistic. The stock tells a cooler story. Shares are down 5.4% since the last report while the S&P 500 was essentially flat. At $48.71, the stock trades below its 200-day moving average of $51.16 and in the lower half of its post-earnings range of $45.27 to $52.27. That entire range sits below the prior quarter's trading band, which suggests investors have reset their expectations lower even as the strategic news improved.
That gap is the heart of the setup. If Emera can show earnings growing again, interest costs starting to ease and the Florida growth pipeline moving forward, the case that 2026 is a transition year rather than a stall becomes much easier to make. Another flat or down quarter, even one blamed on asset sales and refinancing timing, would leave investors asking when the deleveraging payoff actually reaches per-share earnings.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-02 | |
| Aug-25 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-07 | |
| Aug-07 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 |
