TotalEnergies Misses On EPS But Lifts Cash Flow Outlook And Buybacks As Refining And LNG Carry A Record-Setting Quarter
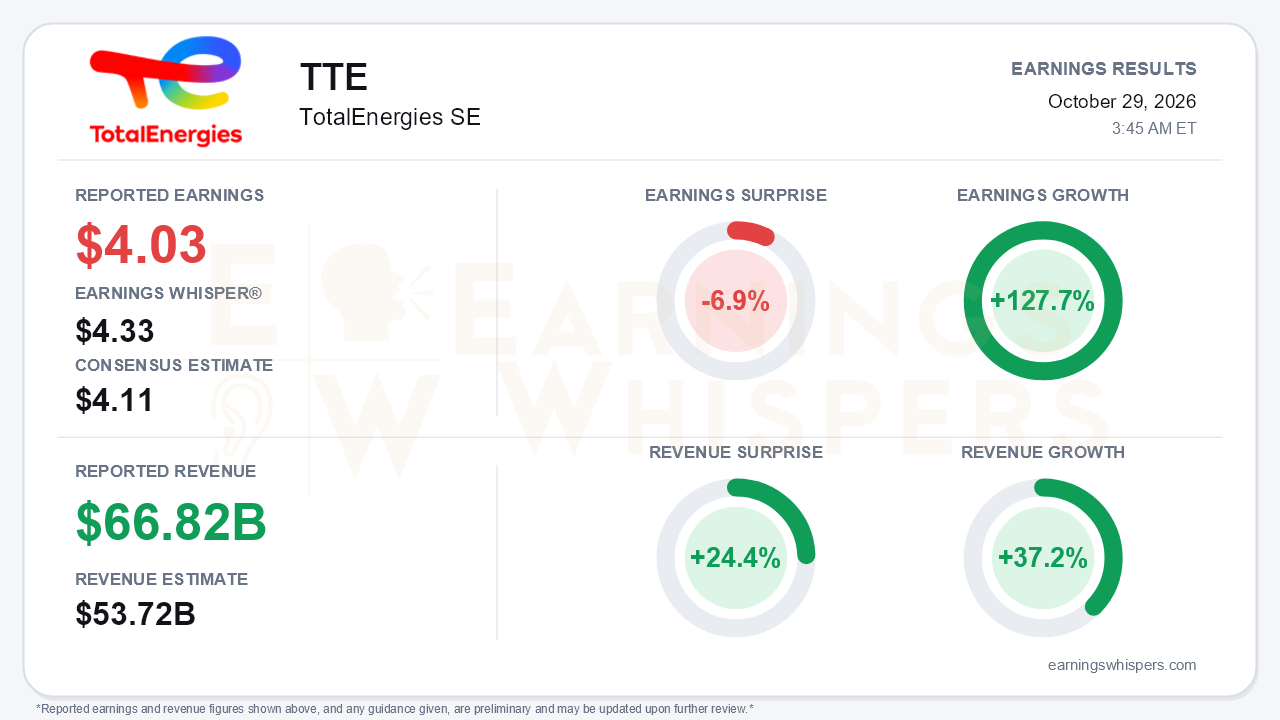
TotalEnergies delivered one of the strongest quarters of the current cycle, yet the headline still reads as a miss. Adjusted earnings of $4.03 per share fell 6.9% short of the $4.11 consensus and well below the $4.33 Earnings Whisper number. Revenue of $66.819 billion beat consensus by 24.4%. Year-over-year earnings growth of 127.7% and revenue growth of 37.2% mark a clear acceleration. Adjusted EPS jumped 51% sequentially from $2.68, and nine-month EPS growth stood at 78%. That is the central tension: the per-share number came in below what investors were positioned for, but almost everything that drives capital returns moved higher. Cash flow from operations excluding working capital (CFFO) rose 25% sequentially to $12.3 billion, and management lifted full-year CFFO guidance to more than $42 billion, possibly $43 billion. That is up from $35-38 billion just one quarter ago.
The composition of the quarter deserves scrutiny. Downstream did the heavy lifting. Refining & Chemicals adjusted net operating income doubled to $3.6 billion as the European refining margin marker hit $33.2/bbl, about 2.5 times the second-quarter level. Refinery throughput rose nearly 10%, with SATORP returning to nominal capacity. Integrated LNG more than doubled to $1.9 billion as the gas-trading long position that hurt second-quarter results swung to profit. The upstream picture was softer. Brent averaged $97 versus $104, and Exploration & Production income slipped 2% sequentially to $3.2 billion, with E&P cash flow easing to $5.4 billion from $5.8 billion. On a GAAP basis, net income of $8.3 billion trailed adjusted results. A $1.5 billion inventory and fair-value gain was more than offset by $1.9 billion of impairments tied to offshore wind and the Hanwha petrochemical stake. A lower effective tax rate, 37.0% versus 39.3%, also helped. Reported operating cash flow of $15.4 billion was further flattered by a $3.1 billion working-capital release tied to higher payables and tax liabilities, which will not repeat indefinitely.
Operationally, the call preserved a credible growth story beyond the commodity windfall. Production rose more than 3% sequentially to 2.474 Mboe/d. Excluding the Middle East conflict, volumes grew more than 4% year over year, and the conflict's drag narrowed to about 5%, the low end of management's 5-10% range. Unit costs held at $4.7/boe. Final investment decisions on Cronos, Ima, Umm Shaif Gas Cap and Absheron Phase 2 mean all projects underpinning the 3%-plus annual growth target through 2030 are now in execution. Integrated Power is tracking toward roughly $3 billion of annual CFFO, helped by KKR farm-downs. The weak spots were volume-related. LNG production fell 7% on maintenance at Angola LNG and Ichthys, and Marketing & Services volumes dropped 4% year over year as high prices cut into demand.
The forward setup tilts favorable but leans heavily on a disrupted market. Oil opened the fourth quarter above $100/bbl, and the company guided fourth-quarter LNG prices above $14/MMBtu, with call commentary pointing toward $15. Buybacks step up to $2.5 billion per quarter for the fourth quarter and first quarter of 2027, from $1.5 billion. The board signaled a possible final-dividend top-up to honor its 40% payout target. Gearing of 9.1% already sits below the 10% target. Bears have legitimate ammunition, however:
- Qatar LNG force majeure persists, with Hormuz LNG flows around 25% of normal.
- The company is in an underlifting position in UAE offshore production.
- The French fuel price cap will cost about $500 million.
- German offshore wind concessions face write-offs.
- Yamal LNG offtake is expected to shrink to about 3 Mt from 2027 under EU sanctions.
- Management explicitly declined to extrapolate refining margins beyond the first half of 2027.
Investor sentiment cooled noticeably heading into the report, sliding from a modestly positive 0.18 to essentially neutral at -0.01. That retreat came even as the stock rallied. Shares at $92.88 were up 6.7% from the open after the July report, 9.4% above the 200-day moving average and just 1.2% below the inter-earnings high of $94.04 set October 26. The stock had climbed nearly 12% off its October 2 low. Price, momentum and AVWAP trend readings are positive, while sequential growth is neutral. The market setup is therefore more complicated than the miss implies: the shares entered earnings near the top of their range, priced for strength, while sentiment had already turned more cautious.
The bottom line is that TotalEnergies missed on EPS but beat on almost everything that funds shareholder returns: cash flow, guidance, buybacks and balance-sheet repair. The quality of those gains rests heavily on historic refining margins and conflict-driven gas pricing that management itself will not project far forward. Underlying production growth and project execution give the story a sturdier base than a pure price windfall. Even so, with shares near their quarterly high, the debate shifts to how long the exceptional margin environment lasts.
Read our earnings preview for TotalEnergies SE: https://www.earningswhispers.com/article/TTE/21143
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 5 hours | |
| 9 hours | |
| 12 hours | |
| 12 hours | |
| 12 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours | |
| 16 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-28 |
