Silicom Hits 71% Growth And Early Non-GAAP Breakeven, But Inventory-Driven Cash Burn And Cooler AI Talk Temper The Third Raise
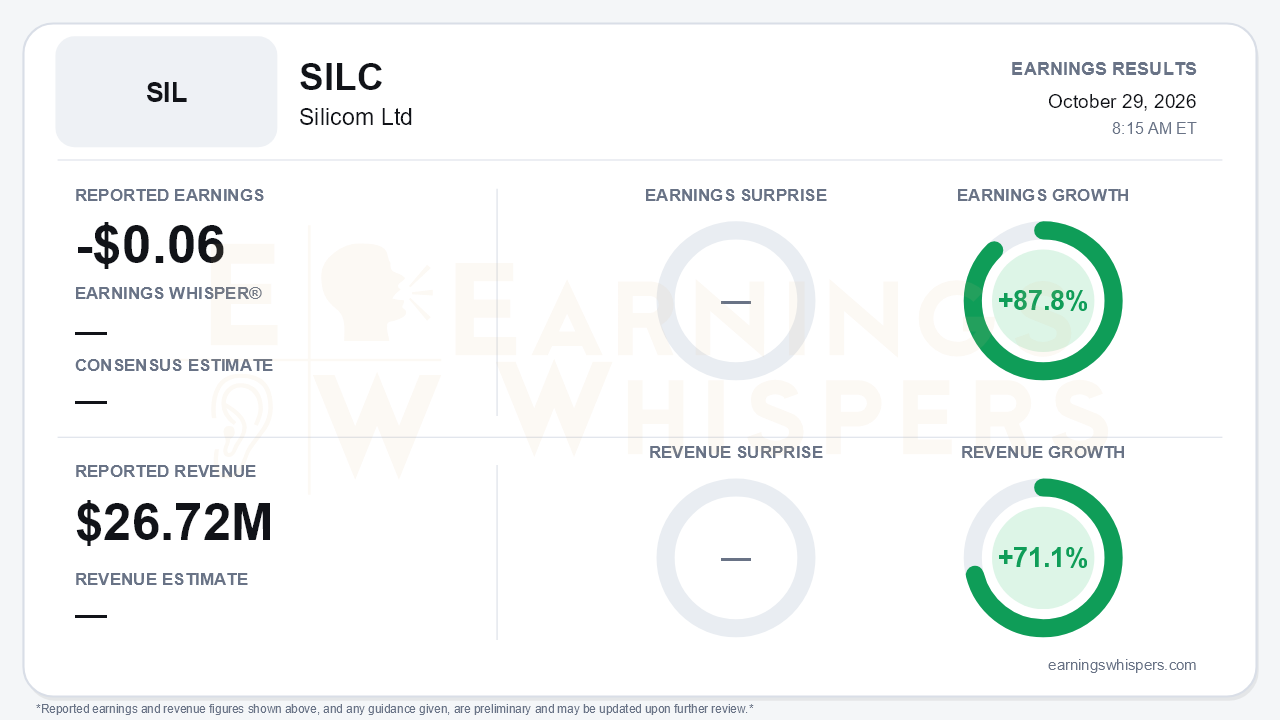
Silicom (NASDAQ: SILC) delivered its strongest growth quarter of the current upcycle. Third-quarter revenue rose 71.1% year over year to $26.72 million, topping the company's $25-26 million guidance. The GAAP loss narrowed to $0.06 per share from $0.49 a year earlier, which Earnings Whispers calculates as 87.8% earnings growth. No consensus or Whisper figure was available, so the useful benchmark is management's own guidance, and Silicom cleared it again. Revenue growth has now accelerated for four straight quarters, from 17% in Q4 FY25 to 33%, 59% and now 71%. Full-year guidance was raised for a third time, to $96-98 million. The central tension is that the top line is unambiguously inflecting, while the cash statement and the AI inference narrative are moving the other way.
The quality of the profitability milestone deserves scrutiny. Management said non-GAAP profitability arrived well ahead of initial expectations. On the Q2 call it had targeted the second half, so a Q3 arrival is earlier than planned. But the operating line is essentially breakeven.
- Non-GAAP operating income was roughly $20,000.
- The $0.3 million non-GAAP net profit, or $0.04 per share, leans on $643,000 of net financial income.
- On a GAAP basis, Silicom still posted a $0.8 million operating loss and a $0.3 million net loss.
The progress is real nonetheless. The GAAP operating loss shrank from $3.1 million a year ago, and non-GAAP EPS swung from a $0.16 loss in Q2. That leverage came from spending discipline rather than better pricing. Non-GAAP gross margin held at 30.3%, essentially flat with the prior three quarters and inside the 27-32% target band. Non-GAAP operating expenses slipped to $8.1 million from $8.3 million in Q2, up only 9% year over year against 71% revenue growth.
The call kept the growth story credible. Design wins reached eight year to date, up from four after Q1 and seven after Q2, against a full-year target of 7-9.
- The newest win is a tier-1 cloud-based cybersecurity customer for a 5G-integrated edge device. Management said it carries more than $5 million of annual revenue at full ramp, with an initial order placed and a ramp expected before year-end.
- The same customer is evaluating higher-end devices, including a GPU-integrated edge AI unit.
- The custom-adapter win announced in July is expected to lift that customer from about $3 million in 2026 to nearly $10 million in 2027.
- Customer concentration also improved. Only one customer exceeded 10% of revenue, at 13%, down from two customers totaling 23% in Q2.
The momentum is not uniform, and bears have legitimate ammunition. AI inference commentary cooled noticeably from the 'potential game changer' framing of the prior quarter.
- One prospect suspended its project to change strategic direction.
- An existing AI customer now has a dual-source option with a competing design.
- Management cited extended decision cycles and did not reiterate the $3-4 million fiscal 2026 AI revenue figure it gave in Q2.
Management did offer offsets. It is in final-stage talks with a new AI inference customer and said the industry's own shift toward dual sourcing is creating second-source opportunities for Silicom. The guidance trajectory is also flattening. The latest raise added about $3 million at the midpoint, versus roughly $11.5 million last quarter. The Q4 guide of $27-28 million implies about 66% growth at the high end, a modest deceleration from Q3's 71%. No fiscal 2027 figures were offered, and there was no update on white-label switch production orders that had been expected by year-end.
The balance sheet is the most underappreciated risk. Cash, deposits and marketable securities fell to about $45 million, down from $55 million in Q2 and roughly $74 million at the end of 2025. Inventory swelled to $72.8 million on memory-related buffer stock. The balance sheet shows $52.7 million of inventory at year-end, while the call analysis cites $42 million, so the size of the build depends on which figure is used. Either way, it is substantial. Payables also rose sharply, to $19.9 million from $11.1 million. Breakeven earnings are not yet translating into cash, and another quarter of this burn rate would leave a materially thinner cushion.
Market context is limited for this report. No sentiment readings or current share price were supplied. Shares opened at $40.93 after the July report, above a 200-day moving average now at $35.71. That suggests investors had already been rewarding the acceleration heading into this quarter, which raises the bar for incremental upside from guidance raises that are getting smaller.
The bottom line is that Silicom proved its operating leverage and design-win engine are working: growth hit 71%, guidance rose again, and non-GAAP breakeven came early. The next leg of the story, however, depends on things this quarter did not resolve. Investors still need AI inference to re-firm, inventory to convert back into cash, and management to put credible numbers around a 2027 it calls 'highly promising.'
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-01 | |
| Sep-02 | |
| Aug-03 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jul-02 | |
| Jul-01 | |
| Jun-30 | |
| May-26 | |
| May-05 | |
| May-05 |
