A.O. Smith Edges Past EPS Estimates, But The China Exit Overshadows A Thin Beat And Rising Cost Pressure
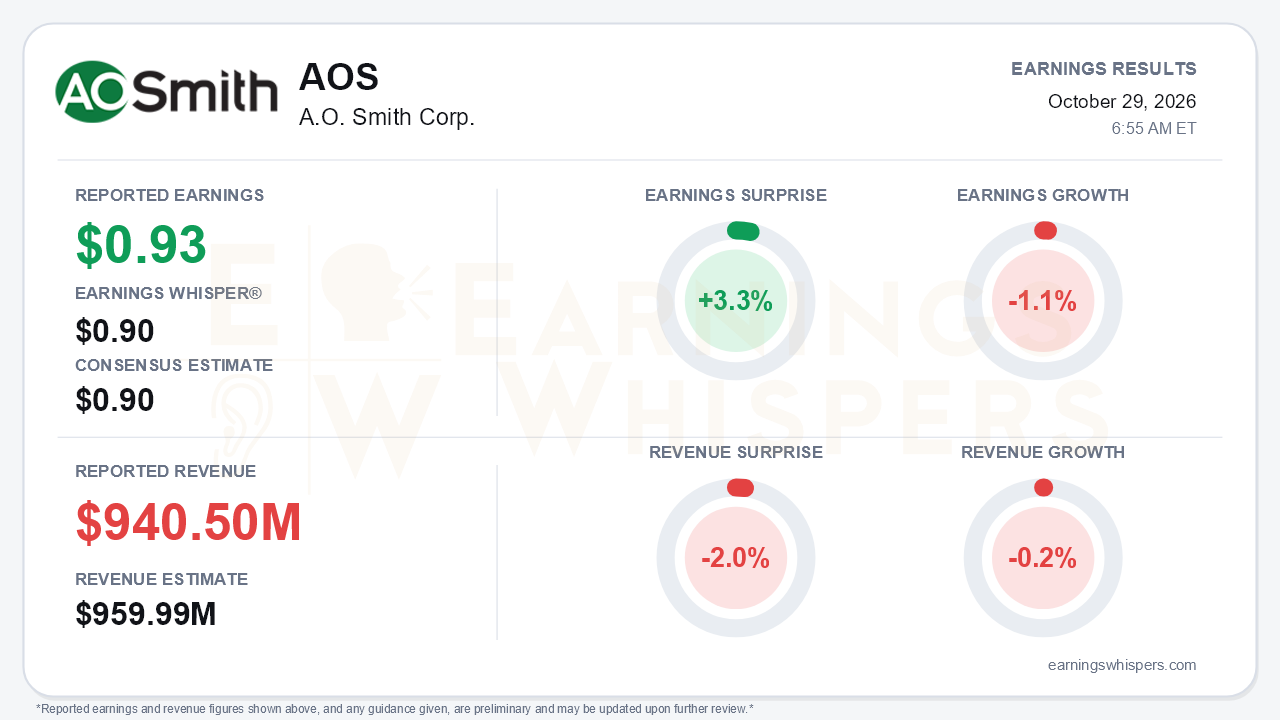
A.O. Smith delivered a modest third-quarter earnings beat that says less about the business than the strategic reset around it. The company earned $0.93 per share, $0.03 above both the $0.90 consensus and the Earnings Whisper number, a 3.3% surprise. Revenue of $940.5 million missed the $959.99 million consensus by 2.0%. Earnings fell 1.1% year over year and revenue slipped 0.2%, and EPS was down sequentially from Q2's adjusted $1.03. The central development was the agreement, announced two days before the report, to sell 81% of the China business to CPE. That deal turns A.O. Smith into a simpler, North America-centric water heating and boiler company. The beat itself was thin and heavily supported.
The quality of the beat deserves scrutiny. North America segment earnings were essentially flat at $179.9 million, and segment margin fell 60 basis points to 23.6%. That result included roughly $10 million of IEEPA tariff refunds, which on their own were worth more than the size of the beat. Management said input costs hit the quarter by $18 million. Below the segment line, corporate expense fell to $16.0 million from $19.7 million, and the diluted share count dropped to about 136 million from nearly 141 million after $260.6 million of year-to-date buybacks. Those items helped offset interest expense that more than doubled after the Leonard Valve financing. Organic North America growth was just 1%, with Leonard Valve contributing $15 million of sales. Rest of World revenue fell 7%, and China sales dropped 17% in local currency, worse than the low-double-digit decline management had guided.
The call showed a business pulling in two directions. Boilers are the clear bright spot. Sales rose 13% after 21% growth in Q2, and full-year boiler guidance was raised to 10-12% from the 6-8% held all year. Management expects that growth to normalize to 4-6% as residential share gains are lapped late in the fourth quarter. Elsewhere, the growth targets kept slipping. Water treatment growth guidance was cut again, to 3-4% from 5-6%, against an original 10-12%. Leonard Valve's 2026 sales outlook fell to about $65 million from $70 million because of boiler-control project delays in New York. Residential water heater sales declined 1%, and the industry outlook remains down low single digits. Steel and freight are now each expected to rise about 15% this year, and management said A.O. Smith exits 2026 at a meaningfully higher cost run rate.
Guidance is where the headline and the substance diverge. Guidance was reset to exclude China, calling for about 4% sales growth and $3.42-$3.52 in adjusted EPS. That range runs from flat to only modestly above 2025's comparable $3.42. Management said the new figures sit within July's $3.70-$3.85 range once China is included, but it gave no like-for-like bridge. That gap explains why the update reads as a reduction despite the company's framing. Against $2.60 in ex-China adjusted EPS through nine months, the range also implies a softer fourth quarter. Management flagged price-cost lag and said no further material tariff refunds are expected. The offset is pricing: a water heater increase of up to 9.5% takes effect in December, and competitors have announced similar moves. An increase that large also raises pre-buy and channel-inventory risk around year-end and into early 2027.
The China deal is the main catalyst. It values the business at about $400 million, or more than $500 million including the present value of the royalty stream. Management expects roughly $350 million of after-tax proceeds plus about $80 million of repatriated cash, earmarked for buybacks after a first-half 2027 close. On a pro forma basis, the ex-China business generated about $3.2 billion of 2025 revenue, with roughly 94% from North America and an EBIT margin of about 21%, versus 19% reported. The Groveport plant closure should add $6-8 million in annual savings. The dividend was also raised 6%.
Investors were not leaning bullish into the print. Sentiment weakened from -0.41 to -0.57, a meaningful move deeper into negative territory. Shares closed at $60.86 the day before the report, down 5.6% since the post-July open. They sit 4.2% below the 200-day moving average and 6% below the quarter high of $64.77. The stock has recovered 11.6% from its October 7 low of $54.55. The AVWAP trend reads positive, while price and momentum trends are neutral.
The bottom line is that A.O. Smith cleared a low bar with help from tariff refunds, lower corporate costs and a shrinking share count, while organic growth stalled and cost inflation intensified. The China exit creates a cleaner, higher-margin company with buyback firepower. Near term, though, the story depends on boiler strength, the December price increase and cost control outrunning steel and freight. Bears have legitimate ammunition in the repeated cuts to water treatment and Leonard Valve.
Read our earnings preview for A.O. Smith Corp.: https://www.earningswhispers.com/article/AOS/21023
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 12 hours | |
| 12 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-12 | |
| Oct-02 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-13 | |
| Jul-02 | |
| Jun-29 | |
| Jun-22 |
