Plains All American Faces A Crude Segment Test After Its Raised Outlook And Rally
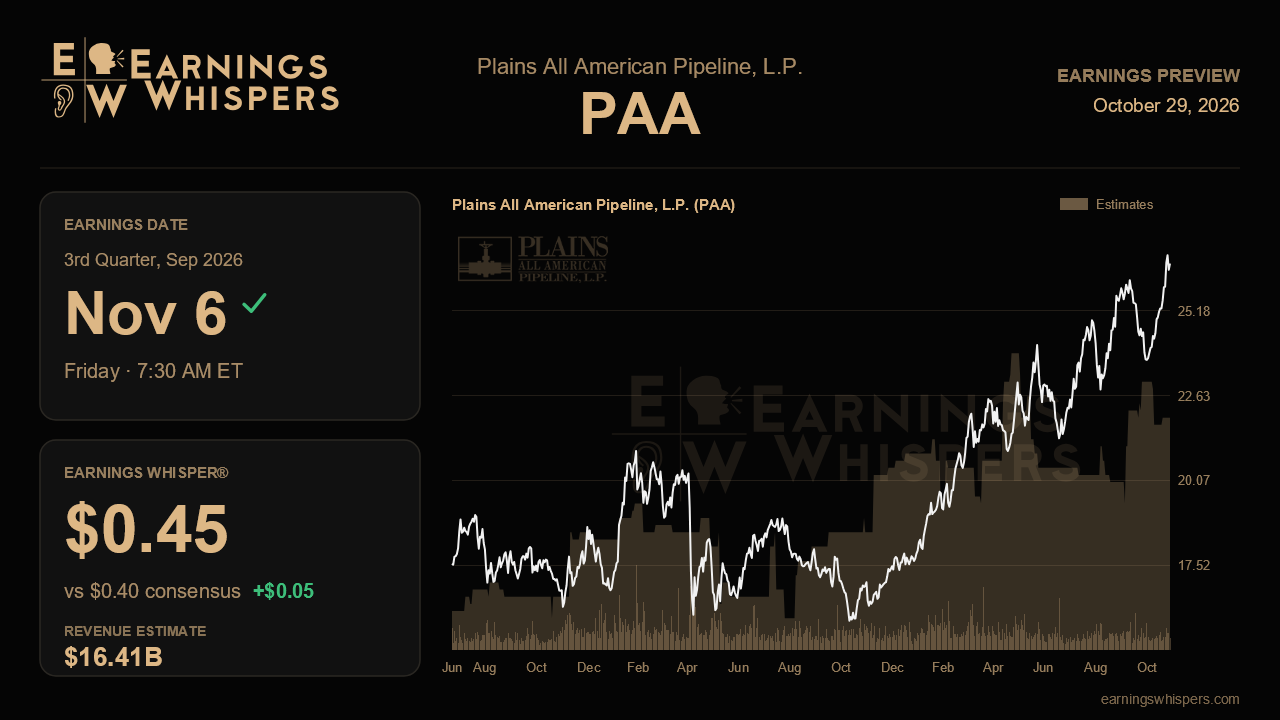
Plains All American walked out of its last earnings call sounding like a different company. The defensive language of integration and self-help gave way to talk of growth projects, new export customers and a market pulled by demand rather than pushed by supply. Since then the units have climbed about 15% while the S&P 500 has barely moved. The third-quarter report, due before the open on November 6, is where that more confident story has to show up in the numbers, and it arrives with the stock trading just below its post-earnings high.
Wall Street expects earnings of $0.40 per unit, essentially in line with the $0.39 earned a year ago and a touch below last quarter's $0.41. The Earnings Whisper sits higher at $0.45, a meaningful gap that suggests the informal bar is set above the published one. Revenue is forecast at $16.41 billion, up nearly 42% from a year earlier, but that headline figure largely reflects the marketing side of the business and the commodity prices that pass through it. The more telling comparison is that profit is expected to grow only about 3%, which puts the focus squarely on margins and segment earnings rather than the top line. This is also the first full quarter without the NGL business, sold in mid-May, so the results should give a cleaner look at the crude-centric partnership.
The central checkpoint is the crude segment. It rebounded to $690 million of EBITDA in the second quarter, more than $100 million above the first-quarter trough, and management modeled the second half in the low $700 millions. Hitting that range would support the raised full-year EBITDA guidance of $2.88 billion, plus or minus $75 million. A shortfall would be harder to excuse, because management chose not to lift guidance further precisely on the argument that a strong back half was already built in. There is a clear swing factor here: management noted that the third quarter was calmer than the second, with narrower margins and less volatility, and it does not forecast market-based optimization gains beyond what has already been captured. If those opportunistic profits faded more than expected, the low $700 million target could be at risk even with healthy volumes.
Volumes are the other piece of the narrative. Management raised its Permian production outlook to growth of 100,000 to 200,000 barrels per day exit-to-exit, citing earlier-than-expected gas takeaway, and said July and August trends were leaning toward the high end. Confirmation of that trajectory, along with an update on the 75,000-barrel-per-day Cactus 3 expansion slated to come online at the end of August, would reinforce the view that 2026 momentum carries into 2027. Progress on Permian and Canadian gathering build-outs, continued strength in Gulf Coast exports and evidence that new export customers are translating into recontracting at better rates would all strengthen the growth case. Investors should also look for the remaining cost efficiencies to keep tracking, with roughly half of this year's $50 million target realized by midyear and another $50 million lined up for 2027.
Sentiment has swung from mildly bearish before last quarter to mildly bullish now, and the units sit well above their 200-day moving average of $22.73, within about 1% of the $26.92 post-earnings high. That combination leaves less room for a merely adequate quarter. Management has already said 2027 guidance will not arrive until February and remains tied to Middle East developments and oil prices, so any directional commentary will be scrutinized.
Ultimately, the report hinges on whether crude segment earnings land in the low $700 millions without leaning on fading volatility. If they do, the raised outlook looks conservative and the breakout case gains support. If not, the market may decide that the rally priced in a 2027 story before 2026 finished proving it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-15 |
This Hot Pipeline Stock Trades In A Buy Zone With a Sizzling 6.7% Yield
PAA
Investor's Business Daily
|
| Oct-01 | |
| Sep-29 | |
| Sep-17 | |
| Sep-16 | |
| Sep-09 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-31 | |
| Jul-14 | |
| Jul-06 | |
| Jun-30 |
