Hyatt Crushes EPS Estimates And Lifts Guidance Again, But Mexico, Distribution And Back-End-Loaded Room Growth Keep The Beat From Being Clean
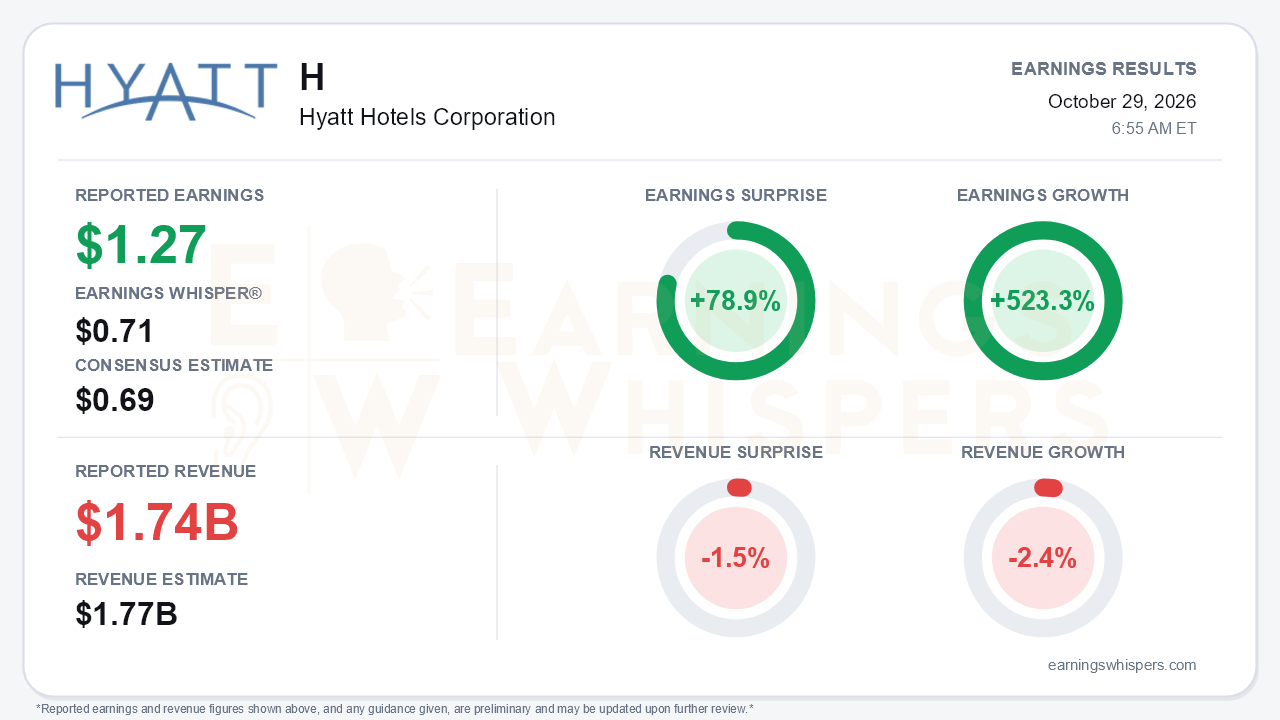
Hyatt Hotels Corporation delivered an earnings beat that was far larger than its revenue line would suggest. Adjusted diluted EPS of $1.27 topped the $0.69 consensus by 78.9% and cleared the $0.71 Earnings Whisper number with room to spare, while earnings grew 523.3% year over year. Revenue told a softer story: $1.743 billion missed the $1.77 billion consensus by 1.5% and fell 2.4% from a year ago. That gap is the central tension in the quarter. Hyatt's fee engine is accelerating, but the parts of the business that still carry real-estate and travel-distribution exposure, especially Mexico, are moving the other way.
The quality of the beat deserves some scrutiny. GAAP diluted EPS was $0.60 and net income was $58 million, less than half the adjusted figures of $1.27 and $122 million. The adjusted number is the authoritative comparison here, but investors should recognize that special items did a lot of work. The more convincing evidence came from fees. Gross fees rose 15.2% to $327 million, well ahead of the company's own high-single-digit expectation for the quarter and roughly double the 8% pace in the second quarter. Base management fees grew 10.0%, incentive fees jumped 21.9%, and franchise and other fees rose 16.8%. Adjusted EBITDA of $295 million increased only 6.2% as reported, but rose 19% after adjusting for assets sold in 2025, up from about 9% in the prior quarter. Those 2025 asset sales also help explain why revenue shrank even as fee earnings expanded.
The RevPAR trajectory is the strongest part of the story. Comparable system-wide RevPAR rose 7.2%, a fourth straight quarter of acceleration after 4% in the fourth quarter of 2025, 5.4% in the first quarter and 5.9% in the second. U.S. RevPAR climbed 8.2%. Luxury led, leisure transient grew about 10%, and business transient firmed to more than 4% in September. Some of that U.S. strength is borrowed, though. Management credited the FIFA World Cup and Jewish holiday timing, neither of which will repeat. Management also expects fourth-quarter U.S. RevPAR to moderate on tougher comparisons and the November midterms. Even so, full-year RevPAR guidance rose to 5.0%–5.5% from 3.5%–4.5% last quarter, and from 1%–3% when the year began. U.S. guidance moved to 5%–6%.
The weaker side of the ledger got worse, not better. All-inclusive Net Package RevPAR fell 2.5%, compared with a 1.2% decline in the second quarter and 7.4% growth in the first. Cancun was down more than 10%. Management now puts the Mexico fee headwind at about $20 million, up from roughly $15 million, and expects the Distribution segment's full-year EBITDA decline to reach about $30 million. That estimate was about $25 million last quarter and about $10 million in the original outlook. Net rooms growth also slowed to 3.9% from 4.4% and 5%. The full-year target of roughly 6% now depends on more than half of the year's openings landing in the fourth quarter, while multi-property conversions are taking longer to close. Free cash flow guidance held at $580–$630 million despite higher EBITDA and lower capex, a detail bears can reasonably flag.
Still, the call preserved a credible growth story into 2027. Management highlighted several supports for next year:
- the development pipeline reached a record of roughly 158,000 rooms, up 12%;
- signings are up 70% year to date;
- World of Hyatt membership reached 72 million, up 19%;
- a new long-term loyalty collaboration with Delta Air Lines adds a distribution channel;
- 2027 corporate group pace is up about 10%;
- first-quarter Americas all-inclusive booking pace is up high single digits, with airlift into Cancun and Jamaica improving;
- the Jamaica hotels are expected to reopen in late first quarter or early second quarter.
Management also expects Net Package RevPAR to return to growth in the fourth quarter. Capital returns guidance rose to $375–$425 million, and third-quarter buybacks totaled $147 million.
The market setup is more muted than the surprise implies. Investor sentiment remained positive but softened slightly, slipping from 0.21 to 0.18 heading into the report. Shares closed at $173.35 the day before earnings, essentially flat at +0.2% since the open after the July report. That flat result came after a round trip: the stock reached $184.35 in mid-August, then fell to $154.16 in mid-September. It sits about 2% above its 200-day moving average and roughly 6% below the inter-earnings high. The trend readings are mixed, with price trend negative while AVWAP remains positive.
The bottom line is that Hyatt's asset-light thesis strengthened this quarter. Fees grew 15%, RevPAR accelerated again, and guidance rose for a third straight quarter. Investors, however, have not yet rewarded that progress. Mexico, the Distribution segment and back-end-loaded room growth are the open questions, and fourth-quarter execution on openings and an all-inclusive recovery will determine whether the 2027 optimism holds.
Read our earnings preview for Hyatt Hotels Corporation: https://www.earningswhispers.com/article/H/21078
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 14 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-23 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 |
