St. Joe's Q3 Dip Reflects A Tough Watercrest Comparison, But Lumpy Land Sales Also Shape This Year's Figures
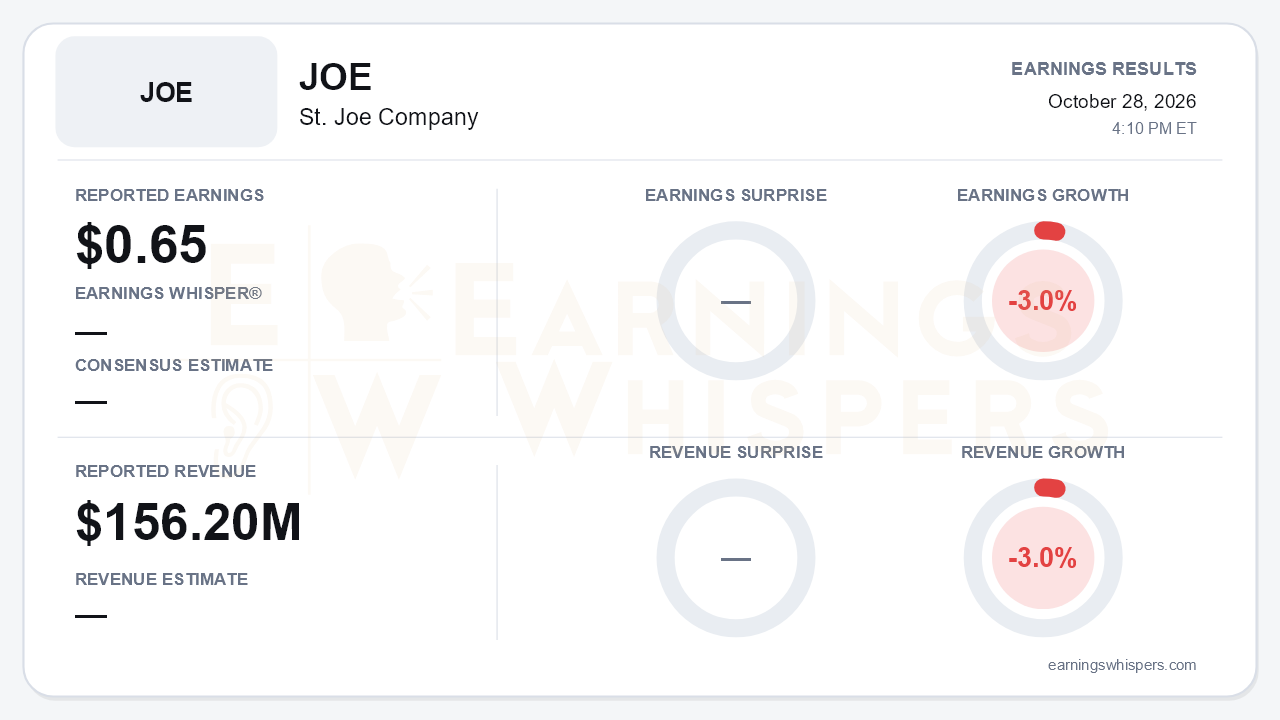
St. Joe Company (NYSE: JOE) reported third-quarter earnings of $0.65 per share on revenue of $156.2 million. Both figures fell 3.0% year over year. That ends a run of strong growth: revenue rose 23% in the second quarter and 24% in the fourth quarter of 2025, and net income rose 37% in Q2. No consensus estimate or Earnings Whisper number was available, so the quarter has to be judged on its own trajectory. The easy explanation is the comparison. The year-ago quarter included the $41.0 million Watercrest senior living sale, which added $19.4 million of gross profit. Management says the current quarter still showed organic growth. That claim holds in hospitality. In real estate, it deserves scrutiny, because Q3 2026 also benefited from a large one-time transaction.
That transaction was the sale of additional land to the Latitude Margaritaville Watersound joint venture. St. Joe booked $31.4 million of real estate revenue, the net present value of a $50.4 million contract, and recognized $21.8 million of operating income. That sale is the main reason operating income rose 16% to $61.5 million while revenue declined. The accounting cut both ways. St. Joe eliminated $10.9 million of the gain through equity in joint ventures, which swung to an $8.2 million loss from a $3.5 million gain a year ago. That elimination dragged on pre-tax income, and EBITDA fell 7% to $64.1 million. Strip out the one-time items from both years, Watercrest in 2025 and the land sale in 2026, and real estate revenue was roughly flat: about $44.7 million versus $42.8 million. Underlying residential activity was soft. The company closed 80 homesites and 5 townhomes, down from 189 homesites and 8 townhomes. The homesite backlog, excluding the Havenry and SouthWood communities, fell to 1,048 lots worth about $103.6 million from 1,345 lots worth $137.4 million a year earlier.
The cleaner growth came from hospitality. Revenue there hit a third-quarter record of $66.0 million, up 9%. Hotel revenue rose 7% and Watersound Club revenue jumped 14% to $26.4 million. Segment gross margin widened to 37% from 35%. Club membership grew by 253 to 3,831, and management said a recent increase in initiation fees was well received. Leasing revenue fell 16% to $14.1 million, but that reflects asset sales such as WindMark Beach Town Center rather than weaker demand. The portfolio remains 97% leased, and 78% of the 85,946 square feet under construction is pre-leased or company-occupied. Corporate expenses rose to $8.0 million from $6.9 million, a modest but persistent headwind.
The forward story improved more than the current quarter did. Latitude Margaritaville Watersound completed fewer homes, 67 versus 82, but new contracts jumped 49% to 106. Year-to-date contracts are up 24%, and the backlog stands at 222 homes worth roughly $140.9 million, up from 149 homes at the start of the year. Phase two nearly doubles the planned community to about 7,200 homes. The land was sold at an average of $14,400 per unit, a 44% increase over the original 2020 deal, and St. Joe expects $40.8 million of total pre-tax income from it over time. The PulteGroup community at Pigeon Creek, planned for about 3,000 homes, remains on track to break ground in early 2027. Together, these projects should support demand at the Watersound West Bay Center, where 69,134 square feet, including a Publix, is under construction.
Capital allocation is the other swing factor. St. Joe bought back $27.2 million of stock in the quarter and $64.9 million year to date, up 161% from the same period last year. Shares outstanding are at their lowest level since 1997. The board also raised the dividend 13% to $0.18. On the call, however, management said growth capex is likely to rise above its $80 to $100 million annual range over the next one to two years, driven by demand from national tenants. Contractual obligations have climbed to $120.6 million from about $30 million a year ago. Cash dipped to $117.9 million even as debt fell to $361.7 million. Bears have a legitimate question here: whether heavier development spending eventually crowds out the pace of buybacks. Other open items include an ICW marina that still lacks a final federal permit and hurricane damage that management described as minor.
Market context is thin. No current price or sentiment readings were available. The stock opened at $64.00 after the July report, just under today's 200-day moving average of $65.93. That leaves no clear technical signal to weigh against the fundamental mixed picture.
The bottom line is that St. Joe's headline decline is mostly a comparison problem, but the offsetting land sale means this quarter was not a clean organic win either. The durable positives are record hospitality results with expanding margins, a sharp pickup in Latitude contracts, and continued capital returns. The watch items are a shrinking residential homesite backlog, timing-driven swings in closings, and rising capex commitments that could compete with buybacks for capital.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-12 | |
| Oct-06 | |
| Sep-24 | |
| Sep-17 | |
| Sep-09 | |
| Sep-03 | |
| Aug-20 | |
| Aug-14 | |
| Aug-12 | |
| Aug-12 |
