Starwood Property Trust's Dividend Math Faces A Stress Test After A 24% Slide
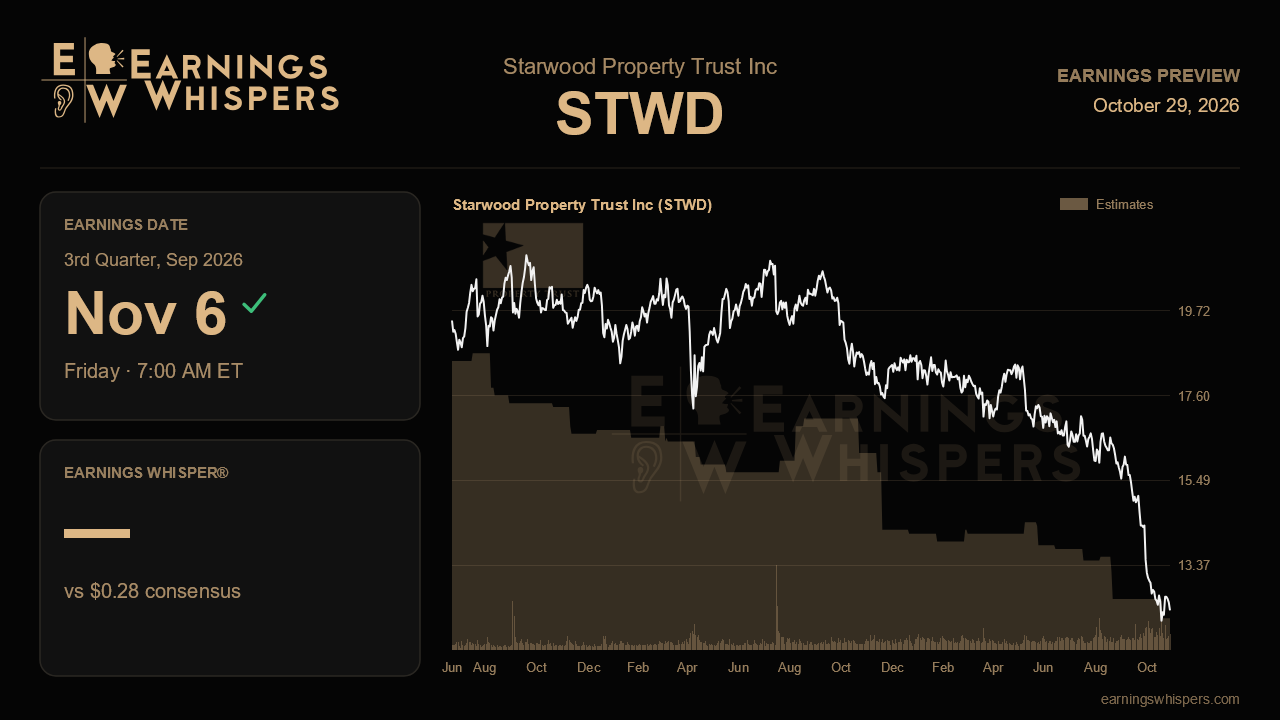
Starwood Property Trust heads into its third-quarter report with a striking disconnect. Management spent the last call describing record-setting deployment, a stronger balance sheet and stabilizing credit, yet the stock has since fallen about 24% while the S&P 500 went nowhere. The gap reflects one admission that overshadowed the good news: the company is no longer covering its dividend from distributable earnings and is knowingly letting book value erode a little to keep paying it. This report needs to show whether that shortfall is temporary or structural.
The Street is not expecting a recovery yet. Consensus calls for earnings of $0.28 a share, down 22.2% from $0.36 a year ago and well below the $0.36 posted last quarter. Part of that decline is mechanical. Management flagged a $6.3 million loss on early debt extinguishment that will hit third-quarter distributable earnings, a cost of the refinancing work that pushed average corporate debt maturity to 3.7 years and tightened the term loan by 25 basis points. No formal guidance accompanies the estimate, so the bar is set by the Street. At $0.28, the question is less whether Starwood clears a lowered hurdle and more whether the quarter offers a credible path back toward dividend coverage.
Several promised catalysts should start to show up. Management said the third quarter would be the strongest origination quarter in company history, following $6.7 billion deployed in the first half. Record volume should eventually lift interest income, but new loans take time to earn, so the near-term payoff is limited. More important for earnings are the one-time items management lined up for the second half: an infrastructure asset acquired through a debt-for-equity swap was under contract to sell at a gain management described as material to both distributable earnings and book value, and more than $800 million of credit resolutions were expected, mostly sales of foreclosed multifamily properties. If those deals closed on schedule, they would support the recovery narrative. If they slipped into 2027, the bear case that earnings power has stepped down gets stronger. Special servicing fees also matter, after falling to $20 million from $52 million on resolution timing even as the active servicing portfolio grew to $10.9 billion.
Credit migration is the swing factor. Each recent quarter has brought more Sunbelt multifamily downgrades, and last quarter added three more loans in Phoenix, Clearwater and Mesa to the watch list on oversupply. Management argued that troubled loans are leveling off, and the shrinking office book, now a company-low 7.6% of assets with $171 million repaid at par after quarter end, supports that view. Another batch of multifamily downgrades would undercut it. On the equity side, the Woodstar affordable housing portfolio has $416 million of debt maturing, and an update on refinancing alongside the 8.4% HUD rent increases would help. Management also promised to unveil a new business line in a segment regional banks have left, and it has repeatedly floated monetizing the net lease portfolio, which it believes the market undervalues.
Sentiment has soured with the share price. Bearish readings have deepened to 34.4% from 24.2% before the last report, and the stock at $12.24 sits roughly 3% above its post-earnings low of $11.84 and far below its 200-day moving average of $16.61. The prior quarter's range of $15.78 to $17.93 now looks distant. That pessimism lowers the bar for a relief move, but it also signals that investors want hard evidence rather than more promises.
Ultimately, the report comes down to whether management can show that dividend coverage is a timing problem. Closed asset sales, completed resolutions and a stable credit watch list would make the current shortfall look like a bridge. Delays, further multifamily downgrades or a softer tone on coverage would suggest the payout itself is at risk.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-26 | |
| Oct-12 | |
| Sep-17 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 | |
| Aug-14 | |
| Aug-06 | |
| Aug-06 | |
| Jul-27 | |
| Jul-23 | |
| Jul-16 | |
| Jul-13 | |
| Jul-01 |
