John B. Sanfilippo Misses Badly As Consumer Losses And Bar Delays Overshadow A Sequential Rebound
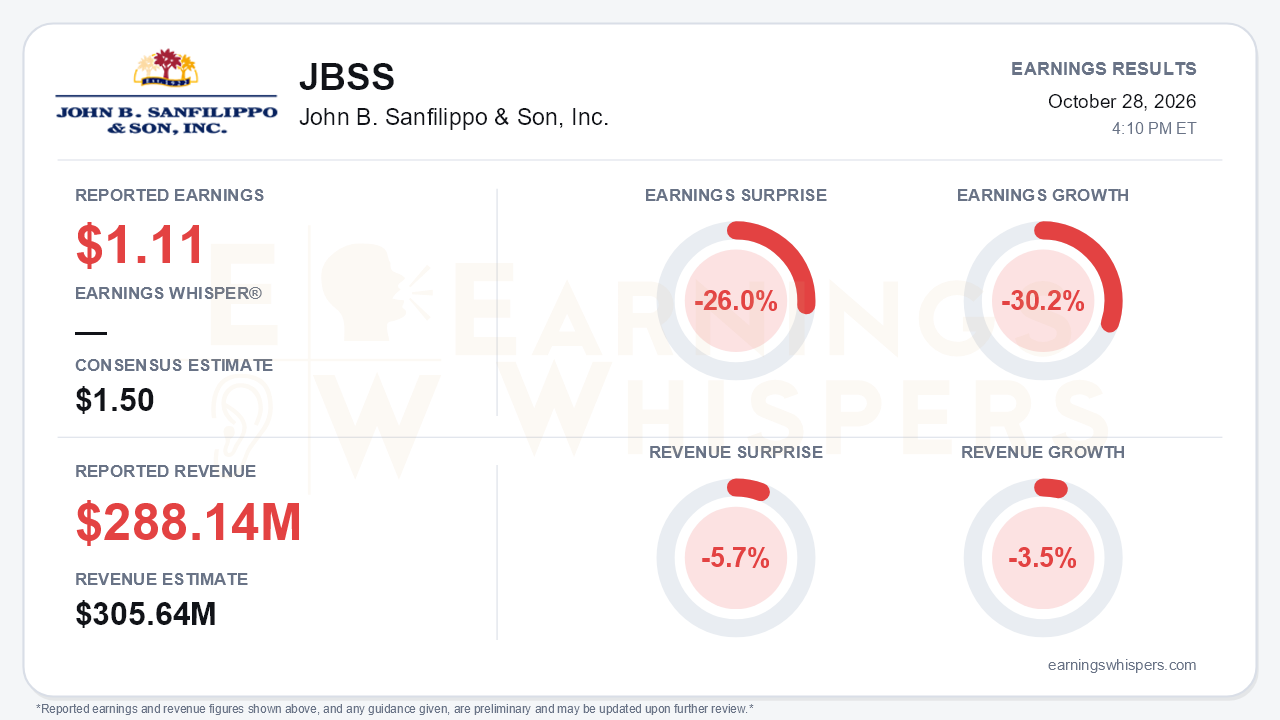
John B. Sanfilippo & Son opened fiscal 2027 with a quarter that management called a "solid start" and the Street will likely call a clear miss. Diluted EPS of $1.11 fell 30.2% from a year ago and came in 26.0% below the $1.50 consensus. Net sales of $288.14 million declined 3.5% and missed expectations by 5.7%. Management's case rests on the sequential improvement, with EPS up more than 50% from $0.71 in the fourth quarter. That rebound is real, but it comes off a weak base. The bigger development is that the top line has turned. Sales rose 4.6%, 8% and 4.2% over the prior three quarters before this first year-over-year decline, so growth decelerated sharply rather than merely cooling.
The quality of the quarter deserves scrutiny. Total volume was flat at 90.5 million pounds, the third straight quarter of stable or improving volume, but the mix underneath it deteriorated. Consumer channel volume fell 6.7%, reversing a 0.8% gain in the fourth quarter. Private brand volume dropped 6.3%, and private label snack and trail shipments fell 8% after rising 3% the prior quarter. Contract manufacturing filled the gap with volume up 41.3%, helped by a new customer running at roughly 7.9 million pounds. Commercial ingredients swung to a 3.7% gain on peanut crushing stock. The cost of that trade showed up in margins. Gross margin slipped to 17.0% from 18.1% a year earlier on competitive pricing pressure, lagging price actions, higher freight, repairs and rent, and unfavorable mix. Operating expenses rose to 10.3% of sales from 9.1%, so operating income fell to $19.3 million from $27.0 million.
The call made clear that the consumer weakness is partly structural, not just category softness. Management attributed roughly 50% to 60% of the consumer decline to lost business, including a mass merchandiser now dual-sourcing nut types where JBSS had been the sole supplier. Management expects that pressure to persist for the next two to three quarters. Management also said contract manufacturing will replace the lost volume but not the lost gross profit. That is an important admission: flat volume going forward should not be read as stable earnings power. Management also described the competitive environment as tougher than normal. Private label bar category volume fell 10%, with reduced distribution in mass and club, and the company's private label bar shipments declined 4%.
The bar growth story, a key pillar of the investment case, also lost time. Protein bar customer shipments are now expected around the end of fiscal Q4 or Q1 of fiscal 2028, versus "early Q3" on the prior call. The fruit-and-grain line slipped to a fiscal third-quarter start, pushing benefits into Q4. That matters because the balance sheet already carries the investment. Net properties stand at $265.7 million versus $181.7 million a year ago, and revolver borrowings climbed to $56.0 million from $33.6 million in June. Spending is running ahead of the revenue it was meant to generate.
There are genuine offsets. Two competitors are exiting nut and trail manufacturing, removing excess industry capacity. Some lost online retailer business has been won back, with shipments expected around fiscal Q4 or Q1. Private label recipe nut shipments rose 29% on grocery and mass distribution gains. Pricing actions take effect in January or February. In addition, the weighted average cost of raw nut inventory is down 20.6%, largely on cheaper peanuts. Management also completed a consulting review that reinforced the protein bar and price-pack strategy, and it launched a formal cost structure review. However, management has not quantified the margin impact of pricing because pecan, almond and peanut costs remain uncertain. The cost review is an intention, not yet a number.
Investors had already been leaning cautious, and the report deepened that stance. Earnings Whispers investor sentiment fell from a roughly neutral -0.04 to -0.32, a meaningful move into negative territory. Shares at $66.34 are down 12.1% since the open following the August report and sit 14.1% below the 200-day moving average of $77.21. Price and AVWAP trend readings are both negative, consistent with a stock the market has been steadily marking down even before this miss.
The bottom line is that JBSS delivered sequential improvement but not the quarter the market expected, and the call weakened the near-term outlook more than it reassured. Sales have turned negative, margins are below every comparable period last year, and the lost consumer volume is being replaced with lower-margin business. The bar capacity payoff has also moved out by roughly a quarter or more. Competitor exits, January pricing and a cost review give bulls something to watch. For now, however, bears have the more concrete evidence, and the stock's position well below its 200-day average reflects that.
Read our earnings preview for John B. Sanfilippo & Son, Inc.: https://www.earningswhispers.com/article/JBSS/21261
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Aug-20 | |
| Aug-19 | |
| Aug-19 | |
| Aug-12 | |
| Jul-17 | |
| Jul-16 | |
| Jul-15 | |
| Jun-02 | |
| May-07 | |
| May-05 |
