PPL Needs Rate Relief To Show Up In Earnings As Data Center Pipeline Keeps Swelling
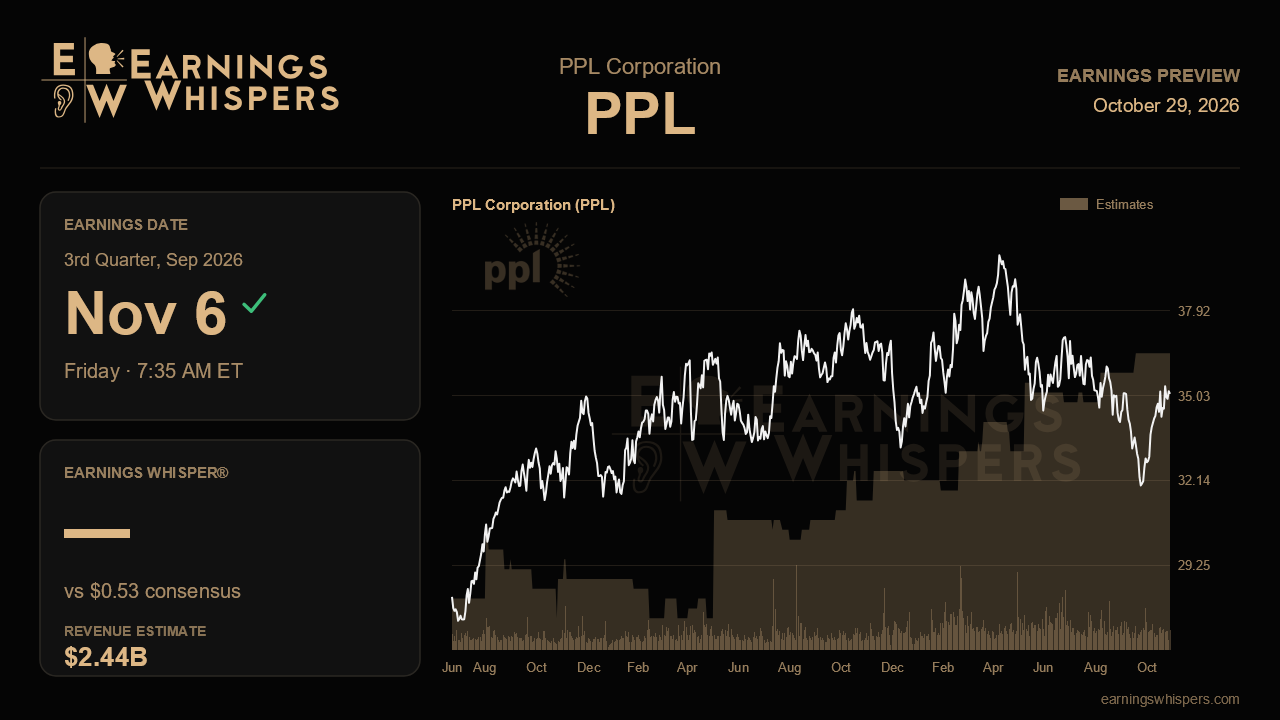
PPL has spent the past year telling one of the more compelling demand stories in the utility sector, but its reported earnings have not kept pace with the narrative. Last quarter, signed data center agreements in Pennsylvania climbed for a tenth straight quarter, while ongoing earnings per share rose by a single penny. The third-quarter report, due before the open on November 6, is the first real chance for fresh rate relief to close that gap and show that the growth story is reaching the income statement, not just the investor slides.
Wall Street expects earnings of $0.53 per share on revenue of about $2.44 billion. That would be roughly 10% growth in earnings from $0.48 a year ago and about 9% growth in revenue, a clear step up from the flat second quarter. The acceleration is not wishful thinking. Pennsylvania's rate settlement, worth about $275 million with a two-year stay-out, took effect July 1, and Rhode Island's new rates were expected September 1, so this is the first quarter carrying most of that benefit. Higher depreciation and interest costs dragged on the Pennsylvania segment last quarter, and the new rates are meant to recover exactly that kind of investment. If the segment still looks soft despite the settlement, that would raise questions about how quickly cost growth is eating into allowed returns. For the full year, management has reaffirmed guidance of $1.90 to $1.98 per share, and consensus at $1.94 sits squarely at the midpoint. That means a solid quarter is largely priced into annual estimates, and a guidance raise, which management has so far declined to offer, would be the clearest sign of upside.
The operational scorecard matters as much as the earnings line. Investors should look for the Pennsylvania pipeline to extend its streak beyond about 32 gigawatts, and more importantly for signed electric service agreements to move beyond 11 gigawatts and construction activity to grow from 6.5 gigawatts. Those later-stage figures are what convert into rate base. In Kentucky, the pipeline reached 13.7 gigawatts with probability-weighted load of 3.7 gigawatts by 2032, and management signaled a new filing for additional generation, including pumped storage, batteries and gas, worth a potential $3.5 billion to $4 billion. Progress on that filing, and clarity on the state commission's response to PPL's reconsideration request, would help determine whether the Kentucky upside is real or stalled.
The biggest swing factor is the NVIDIA Energy joint venture with Blackstone. Management firmed up its language last quarter, pointing to one or more commercial agreements by year-end, backed by land for 8 to 14 gigawatts and more than 5 gigawatts of reservation agreements. That puts this call close to the deadline. A signed deal, or a specific path to one, would validate the $10 billion to $12 billion of incremental capital upside management has outlined and the idea that the joint venture could lift growth above the top of the 6% to 8% target later in the decade. Any slippage tied to the PJM matchmaking process or local opposition to data centers in Pennsylvania would challenge that premise.
Sentiment has warmed noticeably, moving from deeply bearish ahead of the last report to nearly neutral now. The stock, however, has gone essentially nowhere, up about half a percent and roughly in line with the S&P 500. At $35.09 it trades below its 200-day moving average of $36.08 and sits in the upper half of a wide post-earnings range between $31.56 and $36.60, so the market has not yet paid up for the improving story.
That leaves a clear test. PPL needs to show that rate relief is translating into double-digit earnings growth while delivering tangible progress toward a joint venture contract. Meeting the numbers keeps the thesis intact; a signed or imminent agreement is what could finally move the stock.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-23 | |
| Sep-24 | |
| Sep-14 | |
| Sep-10 | |
| Aug-21 | |
| Aug-19 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Jul-30 |
PPL Corp., Blackstone spend $40.4M on possible Luzerne County power plants
PPL
The Times-Tribune, Scranton, Pa.
|
| Jul-23 | |
| Jul-17 |
