Plains GP's Stock Rally Puts The Permian Volume Story To The Test Ahead Of Q3
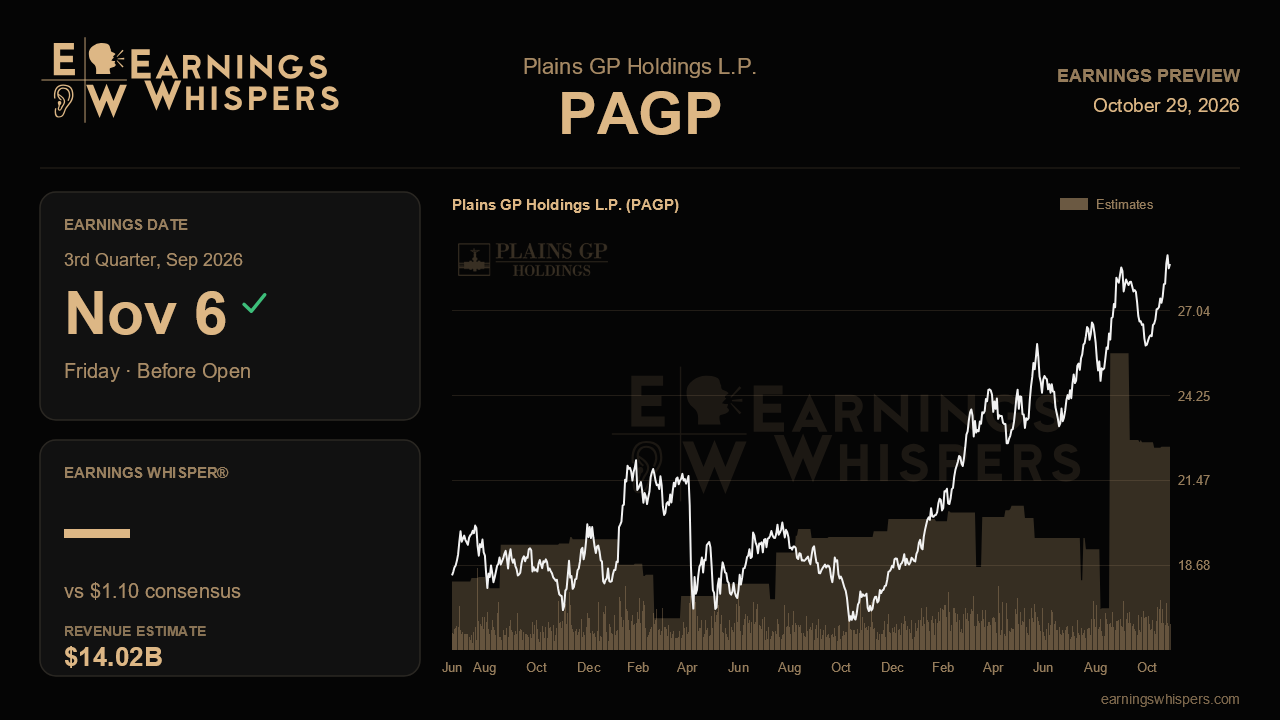
Plains GP Holdings enters its third-quarter report with an unusual tension. Last quarter, management laid out its most growth-minded case in some time, lifting its Permian production outlook, raising growth spending and sanctioning a fresh pipeline expansion. Yet it pointedly declined to raise its 2026 earnings guidance, telling investors the volume upside mostly belongs to 2027. The stock has rallied anyway, so this report has to show that the operating momentum is real enough to justify a valuation that is already pricing in next year.
Wall Street is looking for earnings of $1.10 per share on revenue of about $14.02 billion. Both comparisons look dramatic: the EPS estimate implies growth of roughly 255% from the $0.31 earned a year ago, and revenue is projected up 21%. Those headline figures need context. The prior quarter's loss of $0.37 per share was distorted by the sale of the Canadian NGL business, and revenue for a crude marketer swings heavily with oil prices and traded volumes rather than with underlying profitability. The cleaner yardstick is whether results keep the company on pace for its full-year adjusted EBITDA target of $2.88 billion, plus or minus $75 million. That midpoint was raised $130 million in the first quarter and held steady in the second, with management saying a stronger back half was already built into the plan.
That back-half ramp is the first thing to check. Crude segment EBITDA climbed to $690 million in the second quarter from $582 million in the first, helped by a volatile market that produced wide differentials and lucrative optimization opportunities. Management warned that third-quarter spreads were narrower, which limits that kind of capture. A crude figure that holds near second-quarter levels despite calmer markets would suggest the base business, not trading luck, is doing the work. A meaningful step back would raise questions about how much of the spring strength was transient. This is also the first quarter with the NGL segment removed from reporting, so a cleaner, crude-centric story should make the underlying trend easier to read.
The forward-looking evidence matters as much as the quarter itself. Management said the Cactus 3 expansion, adding 75,000 barrels per day to reach 725,000, would be online by the end of August, and confirmation that it arrived on schedule and is filling would support the 2027 thesis. Updates on the Permian outlook of 100,000 to 200,000 barrels per day of exit-to-exit growth, tied to natural gas takeaway arriving early, are equally important, as is progress on Permian and Canadian gathering build-outs backed by producer commitments. Investors should also look for reaffirmation of $50 million in 2026 streamlining savings and the new $50 million target for 2027, along with any revision to adjusted free cash flow, which slipped to about $1.75 billion last quarter. With leverage already down to 3.3 times, at the low end of the target range, capital allocation commentary could become a bigger part of the conversation.
The market has clearly bought the narrative. Shares are up about 13.6% since the last report against a nearly flat S&P 500, and at $28.58 the stock sits well above its 200-day average of $24.56 and within about 1% of its post-earnings high of $28.93, effectively testing a breakout. Sentiment, by contrast, remains mildly bearish and essentially unchanged from last quarter, a sign that the rally has come without much enthusiasm in the crowd. That combination leaves room for upside on a clean print, but little cushion if the guidance merely holds again.
The central question is whether Plains can show that stronger Permian volumes and new capacity are translating into durable earnings power rather than deferred promises. A reaffirmed or nudged-up EBITDA range, solid crude margins despite narrower spreads and a confident 2027 setup would keep the story intact. Another flat guide paired with softer crude results would leave the recent rally looking ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Sep-17 | |
| Aug-07 | |
| Aug-07 | |
| Jul-31 | |
| May-08 | |
| Feb-27 | |
| Feb-06 | |
| Feb-06 | |
| Feb-04 | |
| Jan-23 | |
| Jan-22 | |
| Jan-20 | |
| Jan-19 | |
| Jan-16 |
