Howmet Aerospace Delivers Record Growth And A Fourth Guidance Raise, But Shares Down 35% Show Investors Questioning What Comes After 2026
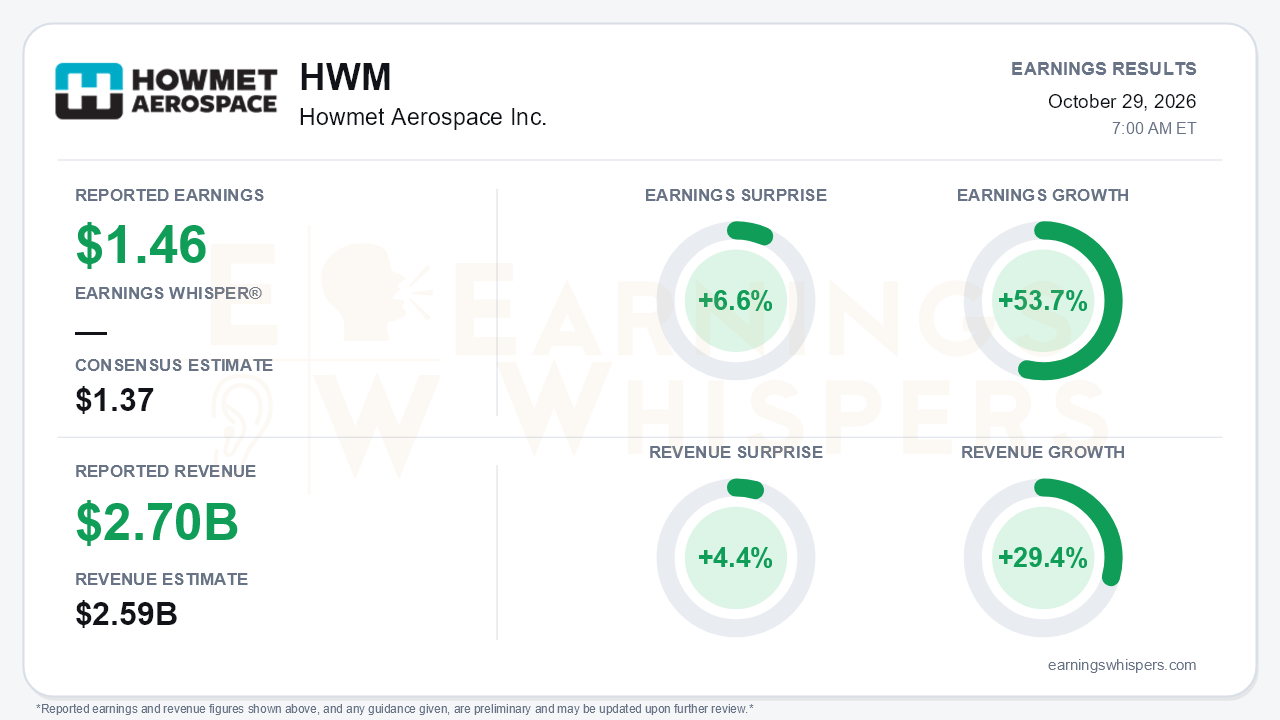
Howmet Aerospace reported third-quarter adjusted earnings of $1.46 per share, beating the $1.37 consensus by 6.6% and growing 53.7% year over year. Revenue rose 29.4% to $2.703 billion, 4.4% above the $2.59 billion consensus, on organic growth of 25%, the strongest rate in the company's history. Management raised full-year guidance for the fourth consecutive quarter. Yet the stock arrived at the report about 35% below where it opened after the August release. That is the central tension. Howmet's operations are accelerating, while the market is debating how durable that growth is and who will capture it.
The quality of the beat holds up. GAAP EPS was $1.42. The gap to the adjusted figure came from $7 million of acquisition costs, $2 million of restructuring, and roughly $10 million of net discrete tax charges, so the adjustments were not flattering add-backs. Operating income rose 43% to $777 million, and adjusted EBITDA margin widened 310 basis points to 32.5%. Free cash flow reached $562 million even after capital spending climbed to $147 million. The standout was Engine Products, where segment margin reached 39.1%, up from 36.6% in Q1 and 37.7% in Q2. That segment grew 33%, entirely organically, as gas turbine revenue jumped 45%.
The acceleration is visible quarter to quarter:
- Organic growth went from 19% in Q1 to 21% in Q2 to 25% in Q3.
- Gas turbine growth reached 45%, versus 38% to 39% in the first half.
- Commercial aerospace rose 32%.
The softer spots sit at the edges. Fastening Systems' 41% headline growth was only 10% organic, and its margin fell 140 basis points year over year to 29.4% on dilution from the CAM acquisition. Forged Wheels margin slid to 26.3% from 29.6% because of aluminum cost pass-through. Defense organic growth slowed to 3% from 7% in Q2, with missile-rate increases and inventory replenishment still waiting on budget clarity. Spares fell to roughly 21% of revenue from 23% in Q1.
The forward story is where the debate lies. Full-year 2026 guidance now calls for:
- revenue of $10.3 billion, up from $9.1 billion in February;
- adjusted EPS of $5.50, up from $4.45;
- free cash flow of $2.0 billion.
The initial 2027 outlook of roughly $11.5 billion, however, implies about 12% growth, less than half the current organic pace. Q4 guidance of $2.74 billion to $2.76 billion implies only modest sequential growth. Earnings Whispers flagged that the revenue outlook came in below estimates. So a raised guide still left the Street wanting more, and investors are being asked to price a deceleration even as growth peaks.
The call added two significant catalysts:
- The industrial gas turbine target was pulled forward and enlarged. Management now expects to double the roughly $1 billion 2025 base in three years, versus a prior three-to-five years, and to reach about 2.5x by decade-end. Customers are said to be sold out through 2031.
- Howmet confirmed it supplies blades for turbines powering the SpaceX/xAI Colossus data centers. It also discussed new GE capacity and next-generation LEAP blade work.
The same call surfaced new risks that bears can use. GE's acquisition of CPP and Pratt's Asheville operation point to OEM vertical integration in castings, and SpaceX may insource turbine blade casting. Management addressed these at length, but they go directly to Howmet's share in its highest-margin franchise. Other pressures include elevated jet fuel prices tied to the Iran conflict, a capex step-up into 2028, and the strain of hiring thousands of workers across seven new plants.
The market had already moved decisively against the stock. Shares hit a 52-week high of $310 on the day of the August report and then fell to a 52-week low of $183.52 on October 23. At $195.19, they sit just 6.4% above that low and 21.5% below the 200-day moving average. Investor sentiment swung from a marginally positive 0.02 to -0.23, a meaningful shift toward skepticism. The trend readings are split, with sequential growth and momentum positive while price and AVWAP remain negative. Notably, Howmet repurchased stock in Q3 at an average of $264.77 per share. The new $5 billion authorization, bringing the total to $5.397 billion, now lets it buy at substantially lower prices, with leverage at a modest 1.3x.
The bottom line is that Howmet produced one of its cleanest quarters on record: accelerating organic growth, expanding margins, rising cash flow, and a larger long-term turbine opportunity. The market's concern is not the current quarter but the slope after it. That includes a 12% 2027 outlook, Q4 guidance that suggests a plateau, and new questions about OEM and customer insourcing. The report strengthened the fundamental case, but it did not resolve the durability debate that drove the stock's collapse from its August high.
Read our earnings preview for Howmet Aerospace Inc.: https://www.earningswhispers.com/article/HWM/21084
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 13 hours | |
| 14 hours | |
| 14 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Oct-01 | |
| Sep-15 | |
| Sep-09 |
