Utz Brands Tests A Doubled Share Price Against Flat Third-Quarter Earnings Expectations
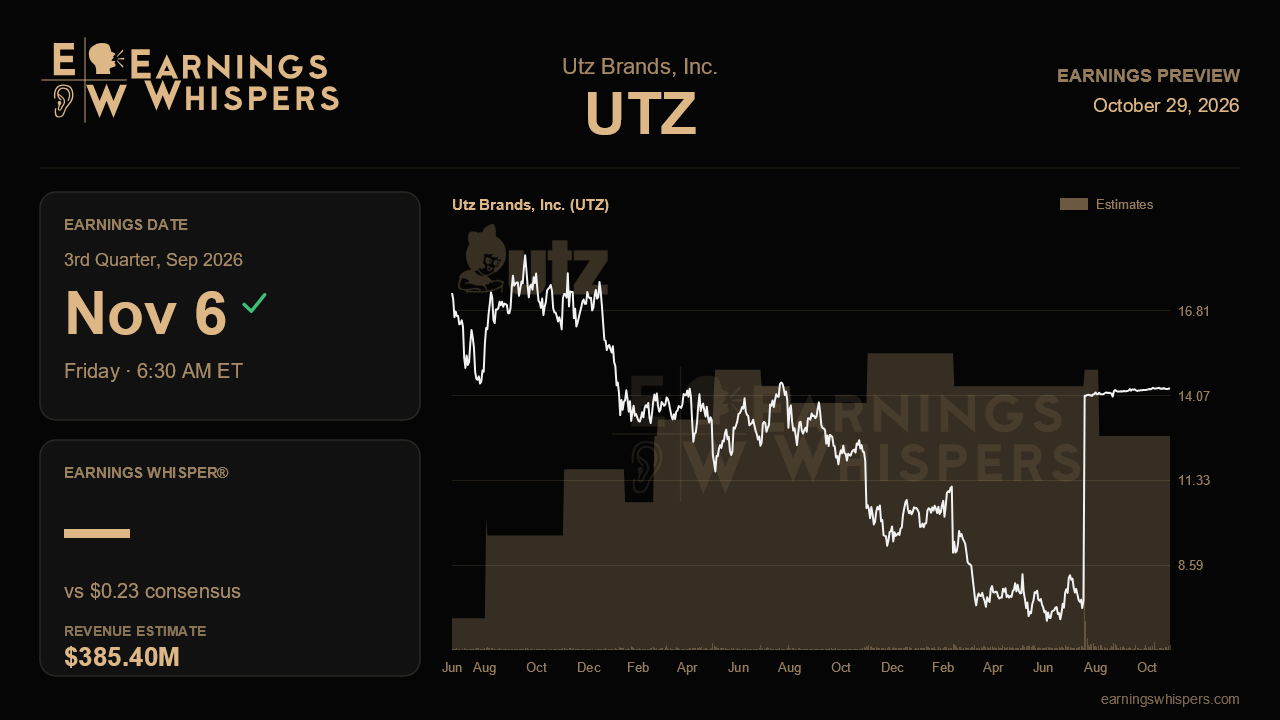
Utz Brands heads into its third-quarter report with an unusual mismatch between its stock chart and its earnings outlook. The shares, which traded as low as $6.78 during the prior quarter, now sit at $14.29, more than double that trough and well above the 200-day moving average of $10.34. Yet Wall Street is not looking for any earnings growth at all. That gap between a dramatically rerated stock and a flat profit forecast is the central tension going into the November 6 release, due before the market opens.
Consensus calls for earnings of $0.23 per share, exactly matching the year-ago figure, on revenue of about $385.4 million, roughly 2% above the $377.8 million reported a year earlier. For a salty snack maker, that profile describes a business that is growing its top line modestly but converting none of that growth into higher per-share profit. Put differently, analysts are assuming that whatever Utz gains in sales gets absorbed by costs somewhere between the factory and the store shelf. The company has not provided updated guidance that would allow a direct comparison, which leaves the quarter's numbers themselves to carry the burden of proof.
The sequential picture offers some encouragement. Last quarter Utz earned $0.19 per share on $371.8 million in revenue, so the Street is asking for a step up of about $13.6 million in sales and four cents in earnings from the second quarter. Hitting that would suggest the business is gaining momentum into the back half of the year rather than treading water. The quality of the revenue matters as much as the total. Growth driven by volume, meaning more bags actually sold, would say far more about the health of brands like Utz, On The Border and Zapp's than growth that leans on price increases or promotional timing, which can fade quickly in a category where shoppers have plenty of alternatives.
Margins are the real swing factor. Because consensus already assumes zero earnings growth on rising sales, even modest improvement in gross margin or operating expenses could push results past the $0.23 mark. Conversely, if heavier promotional spending, input costs or distribution expenses eat into profitability, Utz could post its sales target and still fall short on the bottom line. Investors should pay close attention to any commentary on cost savings and productivity, since those are the levers that would let a low-growth snack business expand earnings without relying on a stronger consumer.
Sentiment has warmed noticeably. Roughly 50% of readings are bearish now, down from nearly 62% heading into the last report, so skepticism has eased without disappearing. The stock has edged up about 1% since the prior release while the S&P 500 slipped 0.5%, a modest outperformance. More striking is how quiet trading has been: the shares have moved within a tight band of $14.04 to $14.36 since the last report, compared with a range of more than $7 in the prior quarter. At $14.29, the stock is pressing against the top of that narrow channel and above the prior quarter's high of $14.19, so a clean move through $14.36 would mark a technical breakout, while a disappointing print could test how firmly the recent rerating is anchored.
Ultimately, this report needs to show that the business can justify a share price that has already moved far ahead of its earnings trajectory. A quarter that pairs volume-led sales growth with stable or improving margins would support the idea that Utz deserves its higher valuation. Another quarter of flat profits on modest revenue gains would leave the stock's recent gains looking more like a repricing in search of fundamental confirmation.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-18 | |
| Oct-14 | |
| Oct-06 | |
| Sep-24 | |
| Sep-22 | |
| Sep-21 | |
| Sep-18 | |
| Sep-10 | |
| Sep-09 | |
| Sep-02 | |
| Aug-28 | |
| Aug-24 |
