Life Time Beats And Raises Again As Core Membership Growth Accelerates, But Heavy Capex Keeps Free Cash Flow Thin
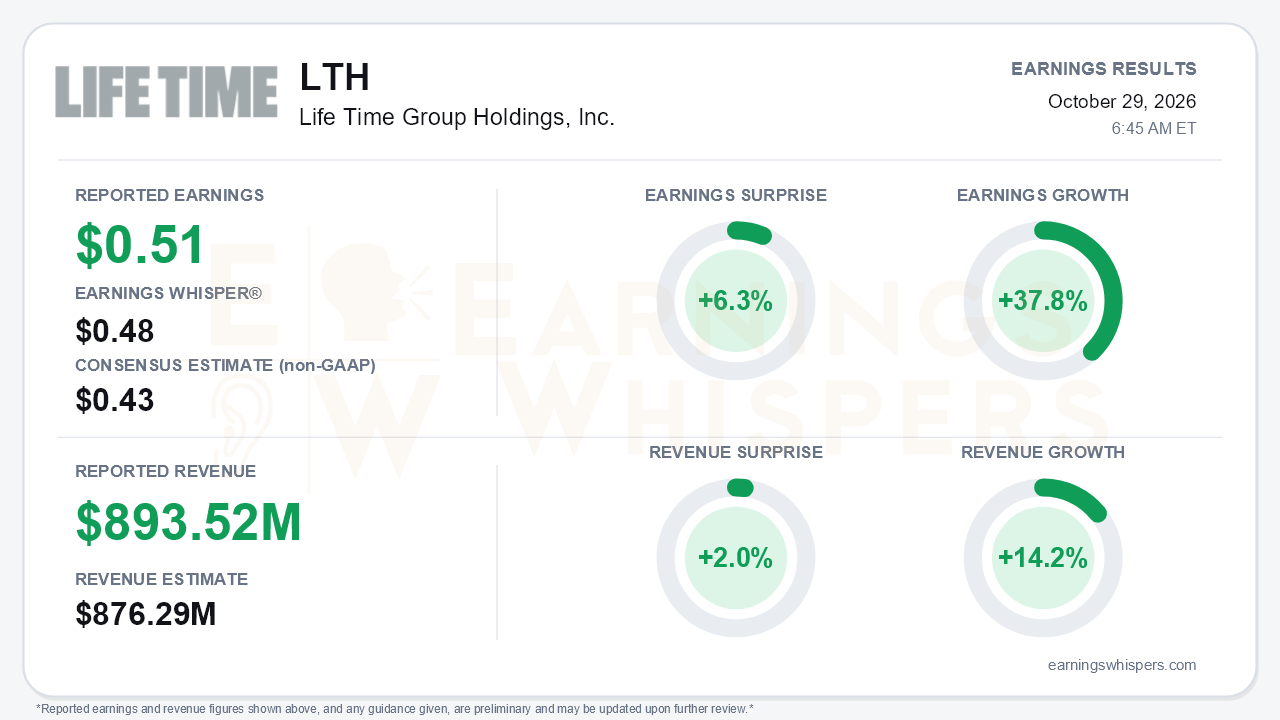
Life Time Group Holdings delivered another beat-and-raise quarter, with core demand still strengthening rather than gliding down. Adjusted earnings of $0.51 per share beat the $0.43 consensus and topped the $0.48 Earnings Whisper number, a 6.3% surprise. Revenue of $893.52 million beat the $876.29 million consensus by 2.0%. Earnings grew 37.8% year over year on Earnings Whispers' normalized basis. The company's own adjusted diluted EPS comparison shows a 24.4% gain from a restated $0.41, so the size of the growth rate depends on the base used, but either measure points to strong expansion. Revenue growth of 14.2% extended a clear acceleration from 11.7% in the first quarter and 13.7% in the second. The central tension is that the operating story keeps improving while free cash flow remains squeezed by an aggressive build-out.
The quality of the beat deserves some scrutiny. GAAP diluted EPS rose only 2.2% to $0.46, and GAAP net margin slipped to 11.9% from 13.1%. That reflects a tough comparison rather than weaker operations: the prior-year quarter included $16.2 million of tax-effected employee retention credits and a larger sale-leaseback gain. Stripping those out, the operating picture is clean. Income from operations rose about 16%, adjusted EBITDA climbed 16.5% to $256.3 million, and adjusted EBITDA margin expanded 60 basis points to 28.7%. Average center revenue per membership jumped 12.0% to $1,016, outpacing 2.2% growth in center memberships. The model is now driven primarily by pricing, mix and engagement rather than headcount.
The call reinforced that point. Comparable center revenue grew 8.7%, and management raised full-year comp guidance for the third straight time, to 8.5%-8.7%. The path has been steady: 6.3%-7.3% initially, then 6.9%-7.5%, then 7.9%-8.3%. The expected deceleration simply has not arrived. Several metrics improved together:
- Membership growth excluding qualified medical plans accelerated to 5.4%, from 4.2% in Q2 and 3.7% in Q1, and the Q4 guide for that metric was lifted to 4.8%-5.2%.
- In-center contribution to comp edged up to 3.0%, led by Dynamic Personal Training and spa.
- Visits per membership rose 4% to 13 a month.
Beneath those gains, the tailwind from membership mix is fading. Its comp contribution eased to 2.4% from 3.1% and 3.5% earlier in the year. Membership volume added only 0.3%, and qualified medical memberships fell 19.6%. The growth formula is shifting from upgrading the base toward in-center monetization and new clubs.
Guidance moved higher across the operating lines:
- Revenue to $3,380-$3,390 million.
- Adjusted EBITDA to $958-$962 million, lifting the implied margin midpoint to 28.4%.
- Adjusted net income to $408-$412 million.
GAAP net income guidance was narrowed to $358-$360 million, trimming the top end, as sale-leaseback losses weigh. Cash taxes were cut sharply to $82-$83 million. Forward catalysts include 14 clubs planned for 2027, nearly all already under construction, along with the LT Social launch and spa and cafe as the next in-center levers. Management also said reliance on sale-leasebacks should shrink, with growth self-funded by 2029-2030.
Bears still have legitimate ammunition. Quarterly capex rose 29.8% to $288.7 million, and free cash flow fell to $35.7 million from $62.5 million despite $62.3 million of sale-leaseback proceeds. Hitting the $400 million sale-leaseback target requires another $135 million in the fourth quarter. Management also flagged a Q4 margin step-down from seven back-end-loaded openings, pre-opening costs and a richer mix of lower-margin in-center revenue. The Miora rollout was paused after its chosen software system failed, a sharper disclosure than the 'technology challenges' cited last quarter. Management acknowledged a softer consumer backdrop while reporting no impact so far. Offsetting those concerns, net debt leverage improved to 1.3x from 1.6x, and liquidity stands above $900 million.
The market setup is more complicated than the surprise implies. Investor sentiment turned meaningfully more negative heading into the report, falling from roughly neutral at -0.03 to -0.28. Shares entered at $43.14, down 4.8% since the open after the July report and 8.7% below the $47.24 52-week high set that day. The stock had slid to $36.52 in late September before rebounding 18.1%, and it remains 23.2% above its 200-day moving average. Earnings Whispers momentum and AVWAP trend readings are positive, while the price trend is neutral. Investors are skeptical, but the longer-term trend remains intact.
The bottom line is that Life Time keeps beating the conservative path it laid out at the start of the year: revenue is accelerating, comps keep getting raised, and core membership growth is speeding up. The open question is no longer demand but capital intensity. Until free cash flow catches up with the build-out and reliance on sale-leasebacks fades, the stock's souring sentiment may hinge as much on cash conversion as on the next beat.
Read our earnings preview for Life Time Group Holdings, Inc.: https://www.earningswhispers.com/article/LTH/21100
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 |
