Newmark's Record Third Quarter Overshadowed By A Guidance Cut That Undercuts Its Own February Outlook
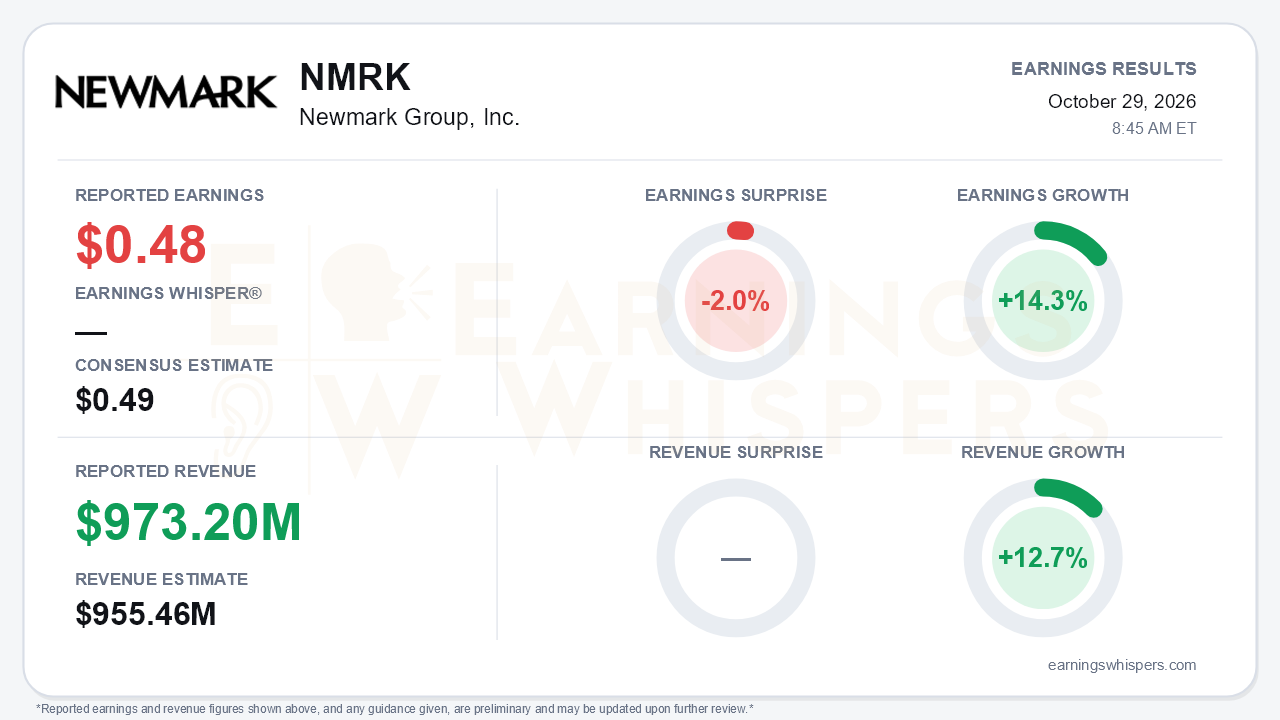
Newmark Group (NASDAQ: NMRK) reported adjusted earnings of $0.48 per share for the third quarter, missing the $0.49 consensus by 2.0%. Revenue of $973.2 million, a third-quarter record, beat the $955.46 million consensus by 1.9%. Earnings grew 14.3% year over year and revenue grew 12.7%. By most standards that is a respectable quarter. The headline result is not the story, though. Management cut its full-year 2026 outlook, and the adjusted EBITDA and adjusted EPS ranges now sit below even the original February guidance. It also framed 2027 earnings as roughly flat, within plus or minus 10%. A company that raised guidance in the first quarter and reaffirmed it in the second has now given that progress back and then some. That reversal is the central tension.
The quality of the quarter is mixed. Leasing was the standout. It grew 26.5% to its best third quarter ever, accelerating from 17.2% in the second quarter and 20.2% in the first. Management credited demand from AI and data center users, technology, manufacturing, aerospace and defense, healthcare and legal tenants. Management services and servicing grew 18.3%, its fifth straight record quarter, up slightly from 17.7%. Capital markets went the other way. Capital markets revenue fell 4.4%, compared with gains of 16% in the second quarter and 45.5% in the first, and GSE industry activity was down roughly 30%. Investment sales volumes still rose 33.4%, and Newmark now ranks second in U.S. investment sales year to date, so the firm appears to be gaining share in a weakening market rather than losing ground. Still, the overall growth curve is unmistakably bending lower. Total revenue growth has slowed from 27% to 17% to 12.7% over three quarters. Implied year-over-year EBITDA margin expansion narrowed to about 30 basis points from 65 and 91 basis points in the prior two quarters.
The guidance revisions quantify the softer outlook:
- **Revenue:** now $3.7 billion to $3.8 billion, down from $3.775 billion to $3.875 billion. Implied growth falls to 12% to 15% from 15% to 18%.
- **Adjusted EBITDA:** now $629 million to $667 million, down from $656 million to $694 million.
- **Adjusted EPS:** now $1.80 to $1.90, down from $1.87 to $1.98.
Cash generation is also cooling. Trailing twelve-month adjusted free cash flow of $336.8 million rose 16%, a sharp slowdown from 111.7% growth in the first quarter. Excluding a roughly $42 million prior-year settlement, third-quarter free cash flow fell about 10%.
The call's tone turned noticeably more cautious. Management cited macro volatility and deal-timing uncertainty, and described transactions as being "pushed." Data center deals are being delayed by NIMBY and political pushback around the election. Management expects industry capital markets volumes to decline through at least the first half of 2027, with a downside case of a 20% to 30% drop in capital markets revenue if rate volatility persists. Even leasing, the current engine, is expected to slow to single-digit growth in 2027 because of Class A supply constraints. The 2029 target of more than $2 billion in management and servicing revenue is now framed as implying "double-digit" growth rather than "mid-teen" growth. Layered on top is leadership uncertainty: CEO Barry Gosin steps down at year-end, and no successor has been named.
There are offsets. The board reloaded the buyback authorization to $400 million, and Newmark repurchased 3.9 million shares for $59.4 million late in the quarter, with more buybacks expected. Capital allocation has shifted toward recurring-revenue acquisitions, with six management and servicing deals in about a year, while employee loan issuance is down 36.9% year to date. Management also plans an international expansion across nearly all service lines over the next 18 to 24 months. Non-U.S. revenue is currently 13% of the total. These moves strengthen the recurring-revenue mix, but they do not offset a capital markets downturn in the near term.
The market had largely anticipated trouble before the report. Shares closed at $12.06 heading into the release, down 21.6% from the $15.39 open after the July report. That leaves the stock about 19% below its 200-day moving average and 26.7% below the inter-earnings high of $16.45 set in mid-August. The stock touched a 52-week low of $11.25 just two days before the report. Investor sentiment flipped from modestly positive (0.13) to modestly negative (-0.11), a meaningful but not extreme shift. Price and AVWAP trend readings remain negative, although sequential growth still registers as positive, which reflects record revenue colliding with deteriorating forward expectations.
The bottom line is that Newmark delivered a record quarter but delivered a weaker outlook alongside it. Leasing and recurring services are performing well. However, the capital markets slowdown, guidance now below February's starting point, a flat 2027 earnings frame and an unresolved CEO transition give bears legitimate ammunition. With shares already near their lows, much of the disappointment may be priced in. A rerating likely depends on capital markets stabilizing sooner than management's cautious timetable suggests.
Read our earnings preview for Newmark Group, Inc.: https://www.earningswhispers.com/article/NMRK/21109
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 11 hours | |
| 11 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Sep-30 | |
| Sep-30 | |
| Sep-28 | |
| Sep-23 | |
| Sep-18 |
