MYR Group Delivers Record Beat And Faster 2027 Growth Outlook, But Weak Cash Conversion Gives A Skeptical Market Pause
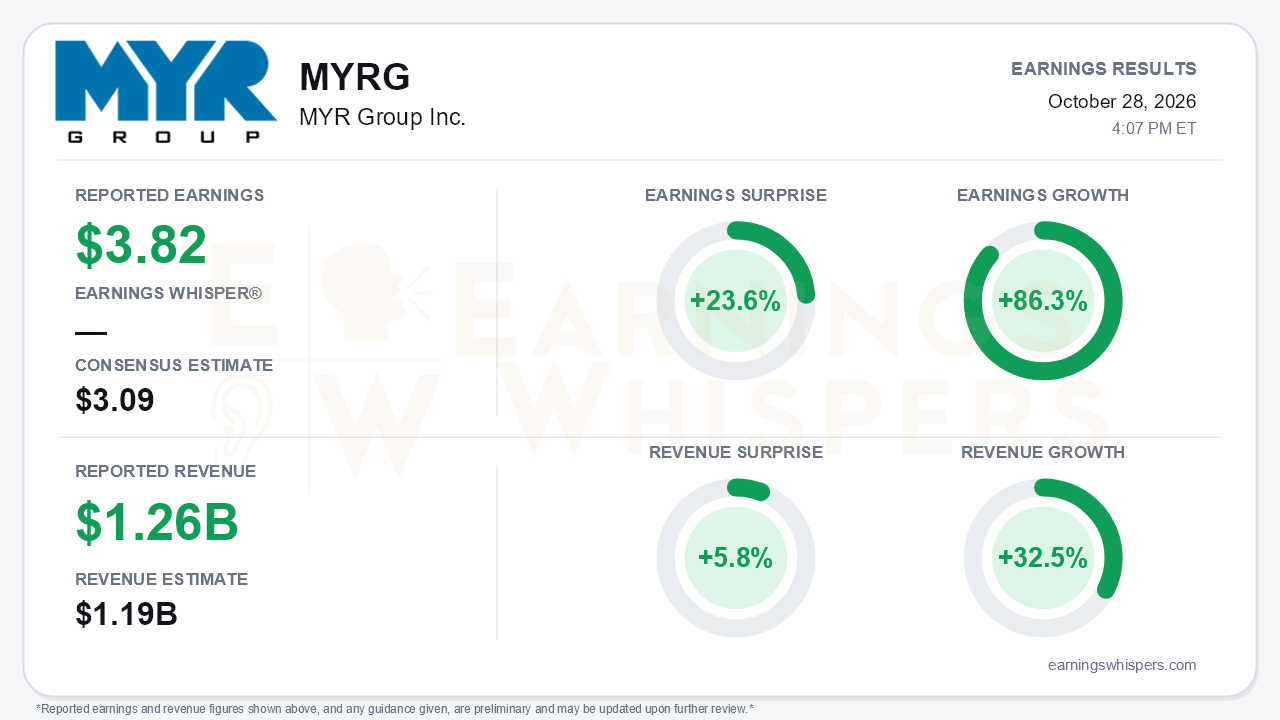
MYR Group posted the kind of quarter that usually resets a narrative. Third-quarter earnings of $3.82 per share beat the $3.09 consensus by 23.6% and grew 86.3% year over year. Revenue of $1.259 billion topped the $1.19 billion estimate by 5.8% and rose 32.5%. Top-line growth accelerated sharply from roughly 20% in each of the first two quarters, and EPS stepped up from $2.99 in Q1 and $3.17 in Q2. Record backlog of $3.68 billion, up 38%, and an initial 2027 outlook calling for 15-18% revenue growth extend the story well beyond one strong print. The central tension is that earnings are surging while cash generation has nearly stalled, and the market had been marking the stock down well before the report.
The quality of the beat deserves some scrutiny. Gross margin expanded to 13.6% from 11.8% a year ago, but a meaningful share of that gain reflects project accounting rather than steady-state pricing. Changes in estimates added a net 0.4 point of margin this quarter, compared with a 0.6-point drag in the year-ago period. That swing accounts for roughly half of the year-over-year improvement, helped by productivity gains and favorable job close-outs. A slightly lower 27.1% tax rate also helped. Growth is partly acquired as well: C&I revenue jumped 58% to a record $704.5 million, including Valley Electric and Comet Electric. T&D grew a more modest 10% to $554.5 million. The acquisitions also brought costs. Intangible amortization rose to $6.1 million from $1.2 million, and interest expense more than doubled. Even so, segment operating margin reached 9.0% versus 7.4%, and C&I margin hit 8.7%, its fourth consecutive sequential improvement.
The call preserved and arguably strengthened the growth case. Management has raised its forward growth framing at every report this year: from about 10%, to roughly 12%, to 13-15% organic plus acquired revenue, and now 15-18% for 2027. That outlook includes 18-22% growth for C&I and 10-13% for T&D. C&I margin expectations moved to the upper end of the 6-9% range for the rest of 2026 and through 2027, after sitting at mid-range in the first half. That range itself was lifted from 5-7.5% earlier. C&I backlog jumped to $2.39 billion from $1.89 billion in a single quarter. Management also said customers are sharing project pipelines out to 2029-2030. Valley amortization appears to be a smaller headwind than feared, with acquired backlog burning off over just over two years.
Bears still have legitimate ammunition. Free cash flow was just $9.2 million, down from $65.4 million a year ago, after a negative $26 million in Q2. Operating cash flow fell to $46 million from $96 million. Management acknowledged that customers are pushing payment terms as rates stay elevated. Unbilled receivables and unapproved change orders are also rising as fixed-price work grows in the mix. Cash dropped to $26 million from $150 million at year-end, and funded debt climbed to $216 million. The new $100 million buyback will be funded partly from the revolver. T&D is also softening at the margin. Operating margin slipped from 9.7% to 9.4% to 9.3% over the year, and management expects modest growth for the next two quarters against a tough comparison. The large 345kV and 765kV transmission build-out remains a late-2027 and 2028-plus story, still exposed to siting and regulatory risk.
The market setup is more complicated than the surprise implies. Shares entered the report at $279.92, down 18.3% from the $342.60 open following the July report. They sat roughly 16% below the 200-day moving average of $334.51. Investor sentiment flipped from modestly positive (0.13) to modestly negative (-0.18), a meaningful deterioration but not a capitulation. The Earnings Whispers price and AVWAP trend readings are both negative, consistent with a stock that has been distributed rather than accumulated since summer.
That backdrop matters. Investors were not positioned for a quarter that combines a 23.6% beat, accelerating revenue, rising margin targets, and a faster 2027 growth outlook. Yet the cash-flow gap and the leverage taken on for Valley give skeptics a reason to question how much of the earnings power is converting to cash.
The bottom line is that MYR Group's fundamental trajectory improved materially this quarter, led by C&I strength, record backlog, and a 2027 outlook that implies continued acceleration. Investors now need to watch whether working capital normalizes and how much margin depends on estimate changes. If cash conversion recovers, the earnings story becomes much harder to dismiss. If it does not, the stock's discount to its summer levels may persist despite the record numbers.
Read our earnings preview for MYR Group Inc.: https://www.earningswhispers.com/article/MYRG/20964
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Sep-11 | |
| Sep-08 | |
| Sep-01 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Jul-30 |
