Myers Industries Holds EPS At $0.32 As A Resin Spike Erases Margins; Signature Growth Plan And Q4 Recovery Promise Carry The Story
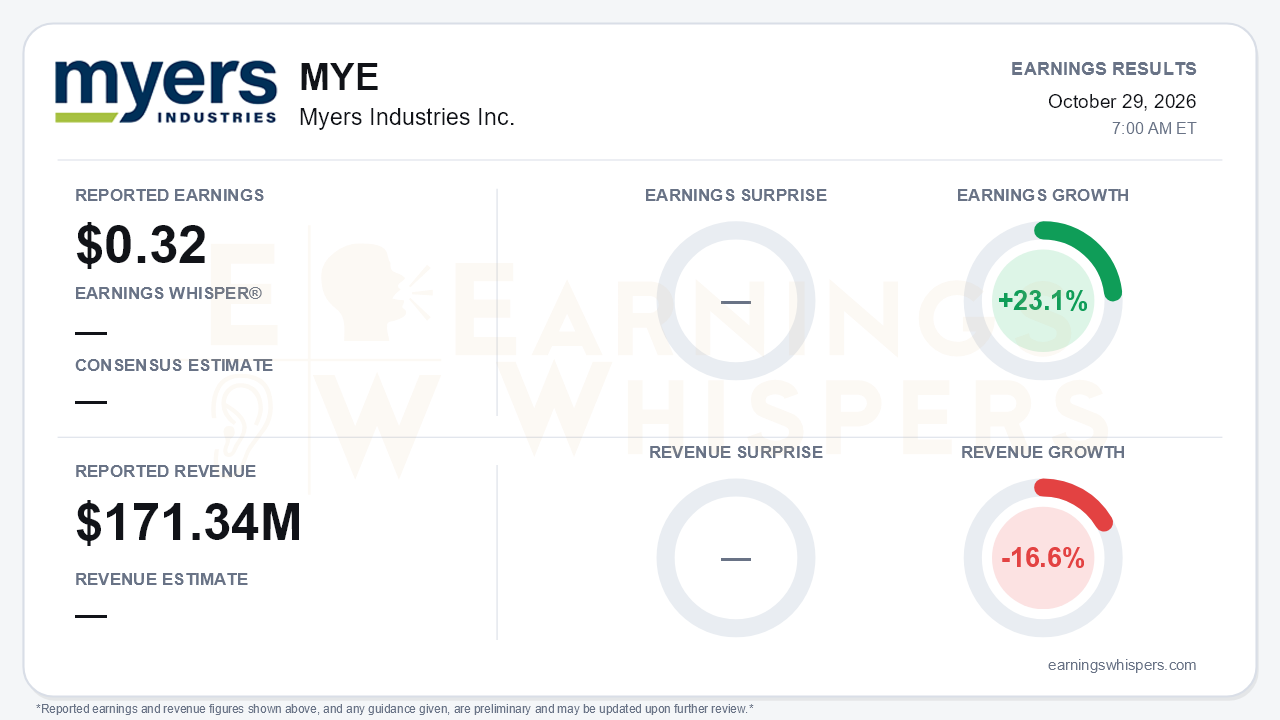
Myers Industries reported adjusted earnings of $0.32 per share on revenue of $171.34 million for the September quarter. Earnings Whispers' normalized comparison shows earnings up 23.1% year over year and revenue down 16.6%. The company's own continuing-operations figures tell a different story: sales rose 8.1% (10.4% excluding exited low-margin products), and adjusted EPS edged up just 3.2% from $0.31. The gap likely reflects how the year-ago base treats the now-divested Myers Tire Supply business, which the company has moved into discontinued operations. Investors should read the normalized growth rates with that in mind. Neither the normalized growth nor the company's slight EPS gain captures what happened inside the business. This was a margin quarter, and a bad one. No consensus figures were available, so the quarter has to be judged on its own trajectory rather than on a beat or miss.
The quality of the earnings deserves scrutiny. GAAP gross margin fell 380 basis points to 27.3%. Adjusted gross margin was 28.2%, down from 34.6% in the second quarter and 34.7% in the first. Adjusted EBITDA margin dropped to 15.5% from 21.8% sequentially, and adjusted operating income declined 9.9% year over year. Adjusted EPS held steady only because interest expense fell to $5.2 million from $7.5 million and the tax line was lighter. That is below-the-line help, not operating improvement. On a GAAP basis, continuing EPS slid to $0.13 from $0.17, weighed by a $3.5 million debt-extinguishment loss from the credit amendment. Including a $5.6 million discontinued-operations loss, the company posted a net loss of $0.02 per share. Quarterly free cash flow of $11.5 million was roughly half the $21.8 million a year ago and well below the $26.5 million in Q2.
Management attributed the compression to a 76% resin spike between March and May, a lag in price realization, unfavorable mix and unplanned maintenance. Its central claim is that this is transitory. Resin has since declined and stabilized, pricing actions remain in place, and the company expects "significant sequential margin improvement" in the fourth quarter. The commitment is directional and unquantified, so the next print becomes a direct test of that credibility. Encouragingly, SG&A fell in dollars and as a share of sales, suggesting the Focused Transformation cost savings are holding.
The top-line mix was more constructive than the margins. Infrastructure, driven by Signature Systems matting, grew 38%, though that was a deceleration from 52% in Q2. Food & Beverage grew 12%, and its full-year outlook was raised again to strong growth on intermediate bulk container (IBC) conversion, backlog and quoting. That extends a steady climb from "slightly down" earlier in the year. Consumer was lifted to moderate growth on fuel-can demand. Industrial, Consumer and Vehicle sales were flat, however. Industrial was held back by military timing softness that persists into Q4, and the Vehicle outlook was cut from stable to down on RV weakness and delayed automotive OEM launches.
The most significant forward-looking development was a new long-term framework for Signature. Management is targeting mid-to-high-teens annual revenue growth through 2029 against a roughly $4 billion addressable market. The plan includes 30% capacity additions in both 2027 and 2029 and an innovation pipeline aimed at more than $60 million of incremental revenue, including the IceShield R10 product for ice arenas. Combined with the Myers Tire Supply exit, the plan sharpens Myers into a more focused specialty-engineered-products story. The balance sheet is also moving in the right direction. Net debt fell $28.5 million, and net leverage improved to 1.86x from 2.2x in Q1. Year-to-date free cash flow of $61.9 million is up 29%. The Central America portion of the tire supply sale remains pending, and working capital rose sequentially as a share of sales.
Market context is limited this quarter. Current sentiment and price data were not available. Shares opened at $35.00 following the July report, well above the 200-day moving average now at $26.42, which indicates the stock had been re-rated substantially on the strong first-half margin story. That re-rating raises the stakes on whether the third-quarter compression proves to be a one-quarter resin event.
The bottom line is that Myers delivered a quarter where revenue momentum, end-market upgrades and deleveraging all held up, but the earnings engine stalled. Margins reset sharply lower, and flat adjusted EPS leaned on lower interest and taxes. The long-term Signature framework gives the growth story real substance. However, bears have legitimate ammunition in the Vehicle cut, the slowing Infrastructure growth and halved quarterly cash flow. The fourth quarter now carries the burden of proving that management's promised margin rebound is real.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-13 | |
| Oct-13 | |
| Oct-08 | |
| Sep-18 | |
| Sep-08 | |
| Sep-03 | |
| Aug-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
