VEON's Digital Surge Faces A Margin Test After Three Straight Guidance Raises
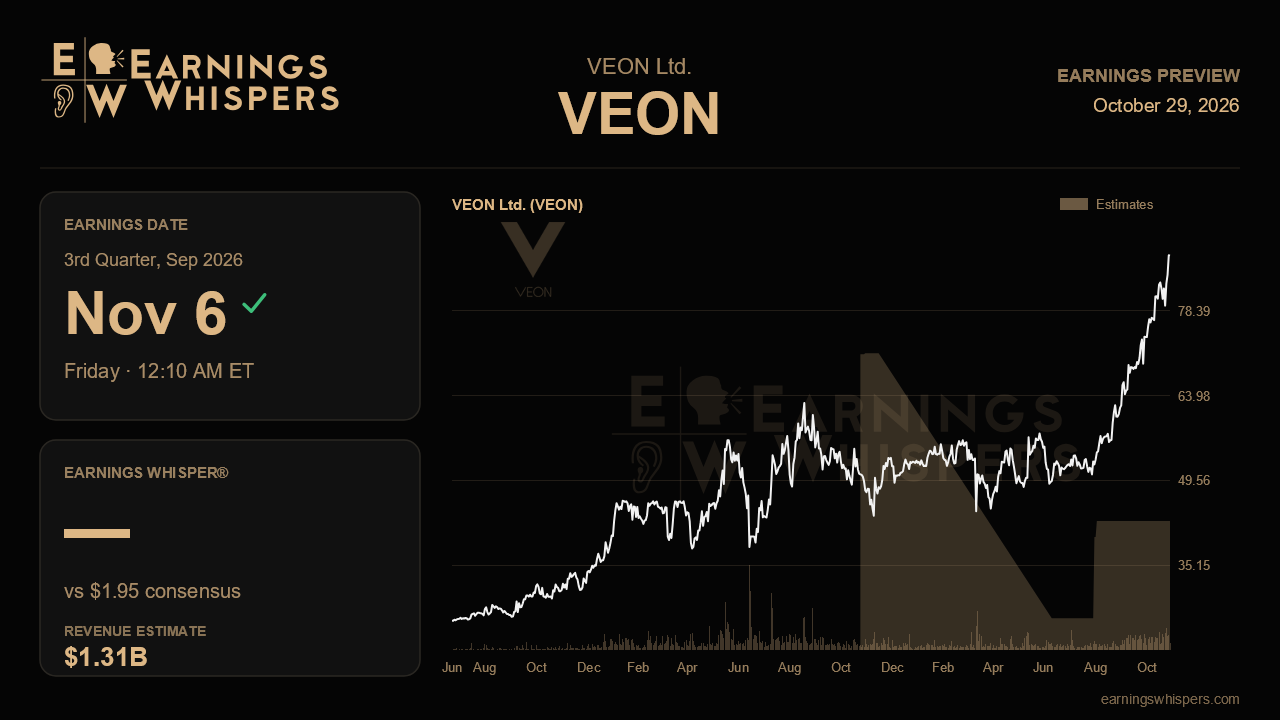
VEON has spent 2026 doing something few emerging-market telecom operators manage: raising its outlook again and again. Full-year revenue growth guidance has climbed from 9% to 12% at the start of the year, to 11% to 14%, and most recently to 15% to 18%, with EBITDA growth lifted to 9% to 12% last quarter. The stock has responded with a 66.7% gain since the last report, crushing the S&P 500's 3.7% advance. The third-quarter release on November 6 arrives with the bar raised accordingly, and ten days before a Capital Markets Day in New York where management will want a clean set of numbers to build on.
The Street expects earnings of $1.95 per share, up about 71% from $1.14 a year ago, on revenue of $1.31 billion, a 17.5% increase. That revenue figure sits squarely inside the newly raised growth range and represents a modest step up from the second quarter's $1.27 billion. The more interesting disconnect is on the annual line. Management now targets 2026 revenue of $5.06 billion to $5.19 billion, yet the full-year consensus of $4.94 billion sits below even the bottom of that range. Either some estimates have not caught up with the latest raise or analysts are discounting currency and macro risk. A third quarter that lands at or above $1.31 billion would make that skepticism harder to defend.
The engine behind the optimism is digital. Last quarter digital revenue jumped 53.6% to $342 million, digital EBITDA rose 66% to $123 million, and the digital margin reached roughly 36%, well above the 20% to 25% management originally modeled. Digital now accounts for about 27% of revenue. The key question this quarter is whether that margin holds or expands as the mix keeps shifting. Evidence of continued growth in Pakistan's JazzCash lending, which had reached 225,000 nano loans per day, plus early traction from the Bangladesh fintech launch slated for the third quarter and the new MasterCard partnership, would validate the flywheel story. A stall in digital margins would undercut the most important reason the stock has rerated.
The group EBITDA line is the other test. Reported EBITDA grew only 6.2% to $552 million last quarter, a sharp slowdown that management attributed to a prior-year Bangladesh provision release, a year-ago Pakistan tower gain and a $22 million warrant fair-value loss, insisting underlying growth exceeded 15%. If those distortions fade as promised, reported growth should reaccelerate toward that adjusted pace. If it does not, the one-off explanation loses credibility. Telecom and infrastructure EBITDA, which fell 3.8%, also needs to stabilize, and Kazakhstan, squeezed by a six-point VAT hike and handset-bundling timing, should show the revenue recognition catching up. Bangladesh energy outages, which cut data usage 15%, and high fuel costs in Pakistan remain the swing factors for the legacy business.
Sentiment has warmed from 18.5% bearish before the prior report to essentially neutral, while the stock trades at $87.77, a hair below its post-earnings high of $88.50 and far above its 200-day average near $57. That places shares right at the edge of a breakout, but it also means much of the good news is priced in, leaving less cushion for a messy quarter.
Ultimately, this report hinges on whether digital profitability keeps compounding fast enough to lift reported group EBITDA above the noise. Clean reacceleration plus reaffirmed or higher guidance would keep the upgrade cycle intact heading into Capital Markets Day. Another quarter dominated by explanations would invite questions about how durable the momentum really is.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-09 | |
| Oct-08 | |
| Oct-02 | |
| Sep-29 | |
| Sep-28 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-23 | |
| Sep-15 |
