Hanover Beats On Record Q3 Operating EPS, But Underwriting Strength Outruns Slowing Premium Growth
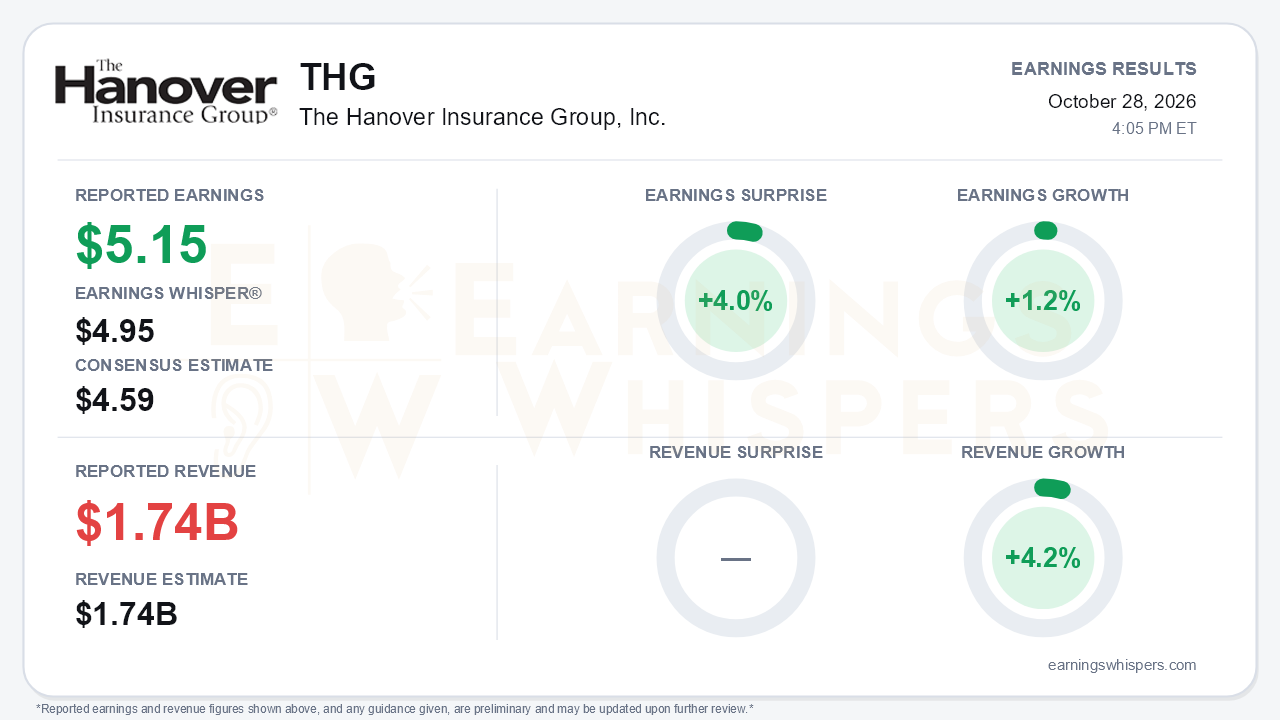
The Hanover Insurance Group delivered another underwriting-driven beat in the third quarter, but the more important development sits beneath the headline. Operating earnings of $5.15 per share, a record for a third quarter, cleared both the $4.59 consensus and the $4.95 Earnings Whisper number, a 4.0% surprise. Revenue of $1.736 billion, up 4.2% from a year ago, fell 0.3% short of consensus. Earnings grew only 1.2% year over year, and operating EPS slipped from $5.31 in the second quarter. That modest growth came despite catastrophe losses more than doubling. The central tension is clear: margins keep improving while premium growth is losing momentum across most of the book.
The quality of the beat is better than the headline growth rate suggests. Catastrophe losses of $109.7 million added 6.8 points to the combined ratio, up from 3.0 points a year ago, which pushed the reported combined ratio to 92.3% from 91.1%. Excluding catastrophes, the combined ratio improved to 85.5% from 88.1%. The current accident year loss ratio excluding catastrophes fell 1.9 points to 55.7%, and the call noted improvement in every segment. Some support came from favorable prior-year reserve development of 1.1 points, including $14.8 million in Specialty, along with benign property frequency. Net investment income also rose 12.7% to $131.9 million as the fixed-maturity earned yield climbed to 4.58%. On a GAAP basis, net income was $4.86 per share versus $4.90, weighed down by $14.1 million of investment losses.
Personal Lines carried much of the margin story. Its current accident year combined ratio excluding catastrophes improved 3.9 points to 81.9%, and the homeowners loss ratio fell to 40.6% from 43.7% in Q2 and 46.7% in Q1. Specialty's underlying combined ratio tightened to 84.6% from 88.6% in Q2. Growth inside Specialty was encouraging as well:
- E&S growth accelerated to 11.7% from 6.5% in Q2, helped by AI-driven submission triage.
- Management liability grew 15.5%.
- Surety grew 8.8%.
The weak spot was Core Commercial, which posted a 100.5% all-in combined ratio as catastrophes hit 7.8 points. Its underlying loss ratio was flat at 60.5% as management kept liability loss picks conservative.
Growth is where bears have legitimate ammunition. Consolidated net premiums written rose just 3.1%, down from 4.6% in Q2 and below the mid-single-digit 2026 target, which management no longer reiterated.
- Personal Lines growth slowed to 1.7%, the fourth straight quarterly deceleration, with policies in force slightly lower year over year. That marks a retreat from the earlier goal of sequential PIF growth by year-end.
- Core Commercial growth slowed to 4.6% from 7.2%, and middle market cooled to 6.7% from 9.4%.
- A competitive property market is pressuring Hanover Specialty Industrial, and management held programs back.
- The 30.9% expense ratio, lifted by incentive compensation, will likely miss the 30.3% full-year guide.
Against those weaker metrics, management upgraded its profitability language. It now expects the full-year combined ratio to "clearly beat" original ex-catastrophe guidance of 88% to 89%, firmer wording than the "couple points better" used earlier in the year. Executives described themselves as never more optimistic, pointing to the Adjuster Workbench claims platform, AI-enabled agency data exchange and the Q4 national rollout of a workers' comp sales platform.
Capital is the other part of the setup. Repurchases rose to $86 million from $55 million in Q2, with $546 million of authorization remaining. Higher rates cut both ways, however. Rising yields lift reinvestment income, but they also widened unrealized losses to $636.1 million and drove GAAP book value per share down 5.4% to $99.69. Excluding those marks, book value rose 2.7% to $114.26.
Investor sentiment improved meaningfully into the report, swinging from -0.33 to +0.11, a shift from mildly negative to modestly positive. The stock is up 3.0% since the open after the July report, at $233.26, and sits roughly 17% above its 200-day moving average of $199.36. The market has been rewarding the margin story, though not aggressively since last quarter. Earnings Whispers trend readings lean positive, with AVWAP positive and price trend neutral.
The bottom line is that Hanover's underwriting engine is running about as well as it ever has, and management's stronger combined-ratio language reinforces that. The beat, however, leaned on improving loss ratios, reserve releases and investment income rather than volume. With Personal Lines units shrinking, Core Commercial decelerating and the growth target quietly dropped, the next leg of earnings growth depends on whether E&S and Specialty can offset a slowing core before pricing tailwinds fade.
Read our earnings preview for The Hanover Insurance Group, Inc.: https://www.earningswhispers.com/article/THG/20992
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Sep-28 | |
| Sep-23 | |
| Sep-11 | |
| Aug-31 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 | |
| Jul-01 | |
| Jun-25 | |
| Jun-04 |
