Provident Financial Misses On GAAP EPS As Debt Charge Hides Record Core Revenue, But Rising Funding Costs And Slower Loan Growth Cloud The Outlook
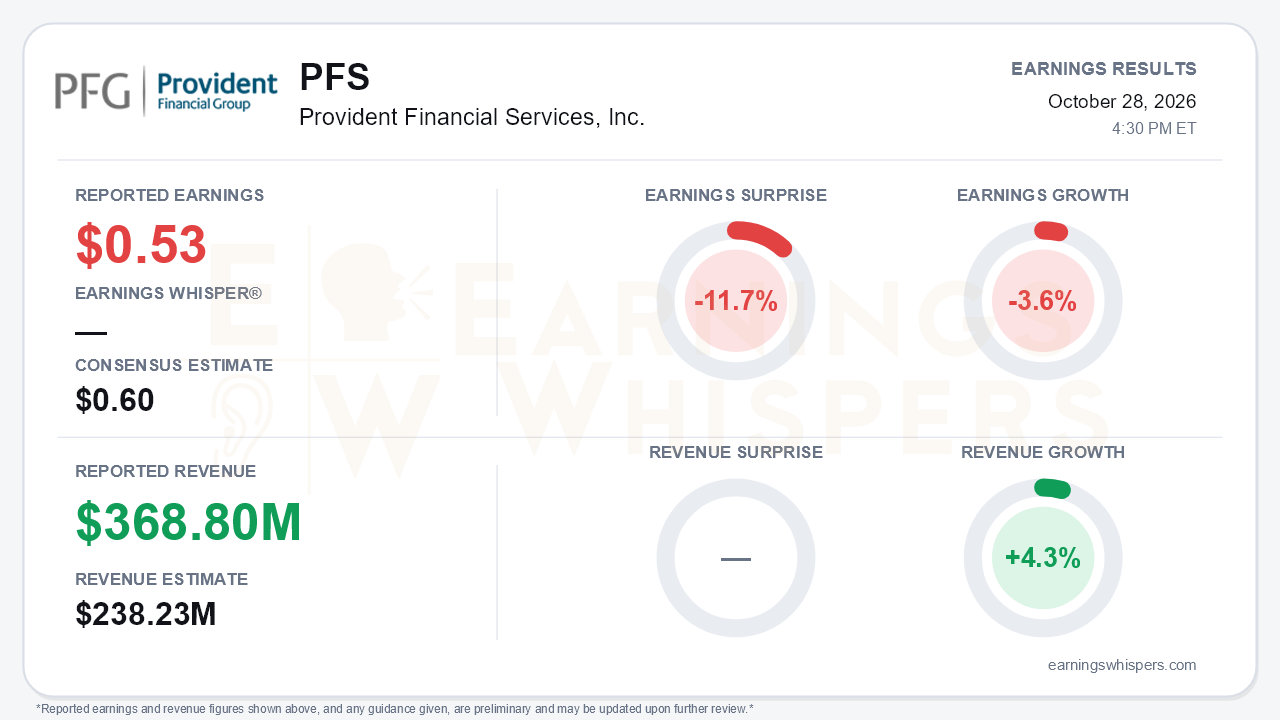
Provident Financial Services (NYSE: PFS) reported third-quarter GAAP earnings of $0.53 per share, missing the $0.60 consensus by 11.7% and falling 3.6% from a year ago. A $17.5 million loss on extinguishment of subordinated debt drove the shortfall. The loss came from accelerated amortization of purchase accounting adjustments. Excluding that charge, $3.7 million of core-conversion costs and $465,000 of branch restructuring, core EPS was $0.65, up from $0.61 in each of the prior two quarters. The headline miss mostly reflects accounting cleanup rather than operating weakness. The harder question is what the next few quarters look like. Loan growth slowed sharply, and the rate backdrop has turned from a tailwind into a modest headwind.
The revenue figures also need context. Earnings Whispers shows revenue of $368.8 million, up 4.3% year over year and 54.8% above the $238.23 million consensus. That consensus appears to be on a net-revenue basis, and the company's own record total core revenue was roughly $238 million. On that basis, revenue was essentially in line rather than a blowout. The underlying trends were still solid:
- Net interest income reached a record $208.0 million, up from $202.7 million in the second quarter and $194.3 million a year earlier.
- Core net interest margin rose 7 basis points sequentially to 3.16%, beating management's prior guidance of 1-2 basis points.
- Core pre-provision net revenue was $119.5 million, up 10% year over year.
- The core efficiency ratio stayed below 50%.
The quality of the core beat still deserves scrutiny. The effective tax rate fell to 25.3% on discrete carry-back credits, well below the roughly 28% management guides to. Bank-owned life insurance income jumped to $6.5 million on benefit claims, about $3.5 million above normal. Strip those out and fee income weakened: it fell to $30.5 million from a record $32.0 million, with loan-related and deposit fees both lower.
The call surfaced three trends worth watching.
- **Loan growth decelerated.** Commercial loans grew 3% annualized, down from 10% in the second quarter, and period-end loans held for investment rose just 2.5% annualized versus 8%. The pull-through-adjusted pipeline has declined three straight quarters, from $1.9 billion to $1.8 billion to $1.7 billion. Management also flagged fourth-quarter payoffs as a drag. It still says growth is pacing near the top of its 5-6% range.
- **Funding costs turned higher.** Interest-bearing deposit costs rose 13 basis points to 2.50% after declining in the first half. Incremental deposits now cost about 3.25%, up from 2.85-2.95% a quarter ago. Seasonal municipal outflows of $527 million were partly backfilled with $432.5 million of brokered demand deposits and borrowings.
- **The rate outlook flipped.** Management now models a December Fed hike, after assuming no action last quarter. The balance sheet is slightly liability-sensitive, losing about 1-2 basis points of margin per 25-basis-point hike. Fourth-quarter margin expansion guidance is therefore a modest 1-2 basis points.
The main offset is roughly $3.3 billion of loans repricing over the next 12 months, from about 5.75% to about 6.5%.
The forward picture is reasonably constructive but not flawless. Management completed its core system conversion on schedule, with only about $1 million of cost left for the fourth quarter. It offered early 2027 framing of 5-6% loan growth and core expense growth of about 3.5-3.75%. However, it raised the fourth-quarter core expense guide to $118-120 million on higher incentive accruals.
Credit has improved since last quarter, though it remains worse than at year-end:
- Net charge-offs are just 5 basis points year to date.
- Non-performing loans are 0.69% of loans, up from 0.40% at year-end. Commercial non-accruals have risen from $33 million to $108 million over that span.
- The allowance has edged up from 90 to 94 basis points as specific reserves were added.
- Management expects resolution of senior-housing credits by year-end, which it says would cut non-performing assets to about 23 basis points.
Tangible book value slipped $0.26 to $16.16, and the tangible common equity ratio fell to 8.4%, both on an $83 million decline in accumulated other comprehensive income. The company resumed opportunistic buybacks in October, repurchasing about 370,000 shares around a $22 threshold.
Investor sentiment, already slightly negative heading into the report, deteriorated meaningfully, falling from -0.06 to -0.21. Shares have dropped 6.2% since the open following the July report, to $23.12. That leaves them only 2.3% above the 200-day moving average of $22.59, and not far above management's stated buyback threshold. The Earnings Whispers trend readings tilt negative, with the AVWAP trend negative and price trend neutral. The market has clearly been discounting the rate and loan-growth concerns that the call validated, more than the margin gains the quarter delivered.
The bottom line is that Provident's GAAP miss overstates the damage. Core earnings, net interest income and margin all hit new highs, and the core conversion is behind it. Still, the drivers behind that strength are turning. Loan growth and pipeline conversion are slowing, deposit costs are rising again, and management now expects a rate hike that slightly pressures the margin. Elevated BOLI income and a low tax rate also flattered the core beat. Until loan repricing visibly outruns funding costs and the senior-housing credits are resolved, bears have legitimate ammunition, and the cooler sentiment looks more like a reasonable reassessment than an overreaction.
Read our earnings preview for Provident Financial Services, Inc.: https://www.earningswhispers.com/article/PFS/20975
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-02 | |
| Sep-29 | |
| Aug-20 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 |
