Acadian Beats On Record Margin And Comp Leverage, But Slowing Flows And A Revenue Miss Temper The Quarter
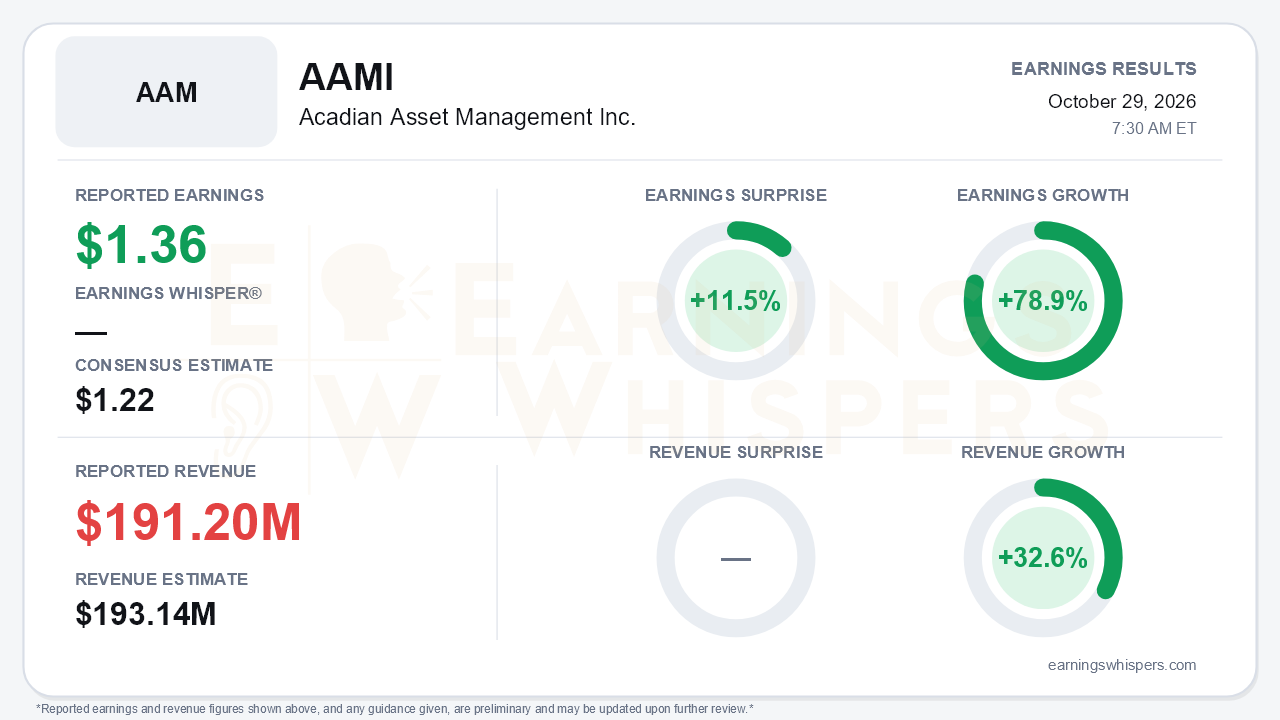
Acadian Asset Management (NYSE: AAMI) delivered another record quarter on the earnings line, but the quality of the beat depends more on margin and compensation leverage than on top-line strength. Economic net income (ENI) per share, the company's non-GAAP measure, came in at $1.36, a firm record. That was 11.5% above the $1.22 consensus and up 78.9% year over year. Revenue of $191.2 million rose 32.6% but missed the $193.14 million consensus by 1.0%. The call showed slightly different figures: ENI revenue of $189 million, up 39%, which reflects a different revenue definition from the normalized figure. Either way, the pattern is the same. Profitability is outrunning revenue, and revenue is not quite meeting the Street's expectations.
The central tension is that Acadian's absolute numbers keep setting records while its growth rates and organic momentum are cooling.
**What went right**
- **Margin:** ENI operating margin climbed to 42.6% from 40.3% in Q2 and 38.1% in Q1. That already clears the aspiration management laid out at its May investor forum, and the CFO said the target could be revisited.
- **Fees:** Management fees reached a record $188 million, up from $177 million in Q2 and $159 million in Q1.
- **Assets under management:** AUM hit a record $239.6 billion.
- **Compensation guidance:** Full-year variable comp ratio guidance was lowered for a second time, to 34-38%, from 38-42% after Q2 and 40-43% at the start of the year. That accounts for a large share of the margin expansion.
**What is decelerating**
- **Year-over-year growth:** AUM growth slowed to 44% from 54% in Q2 and 61% in Q1. ENI growth eased to 78% from 107% in Q2.
- **Net flows:** Inflows fell to $2.6 billion, a 4% annualized pace, from $4.3 billion (9%) in Q2 and a record $21.4 billion in Q1. That still extends the streak to 11 consecutive positive quarters, and management attributed the slowdown to client rebalancing after strong equity gains.
- **Costs:** Operating expenses rose 18% year over year on technology, G&A and AUM-driven servicing costs.
Management explicitly cautioned that the lower comp ratio is tied to the timing of performance fees and should not be treated as a durable run rate. Bears therefore have legitimate ammunition. A meaningful part of the margin story rests on a performance-driven, potentially lumpy input, while the flow engine behind recurring fees has downshifted for two straight quarters.
Investment performance is the strongest counterweight. Trailing one-year outperformance jumped to 95% of strategies, from 77% in Q2 and 73% a year ago. The five-year revenue-weighted excess return improved to 4.8% from 4.3%. That sets up a strong performance-fee year and gives the sales effort a compelling record to market.
The call also added several new growth avenues:
- **Wealth channel:** Acadian was selected as the inaugural manager for UBS Global Wealth Management's exclusive manager-access fund program in Asia.
- **Systematic credit:** First external institutional funding is expected later in 2026 from a prominent US asset owner.
- **Tax Aware:** The strategy, launched in May, received initial client funding.
- **Extension strategies:** These have grown to roughly $13 billion, up about 170% year over year, and inflow fee rates exceeded outflow fee rates, which kept the blended fee rate stable.
The caveat is timing. Management said wealth partnerships could take 12-24 months to contribute, so these are not near-term offsets to slower flows.
Capital allocation is more ambiguous. Cash rose to $150 million from $65 million, and net leverage fell to 0.2x from 0.5x, a clear balance-sheet improvement. Yet buybacks dropped to zero in Q3 after $10.6 million in Q2 and $4.7 million in Q1. The company has more firepower, but the call did not provide a reason for the pause.
Investor sentiment has turned noticeably cooler. The Earnings Whispers sentiment reading slid from a modestly positive 0.10 at the prior report to -0.25, a meaningful swing into negative territory. That shift sits awkwardly against the stock's performance. Shares are about 9.8% above the open following the July report and roughly 24.5% above the 200-day moving average. However, they sit about 7.4% below the $98.52 52-week high set on August 28, having given back part of that summer run. The internal trend readings are mixed, with momentum positive and AVWAP negative, consistent with a stock consolidating after a strong advance rather than one with a clear direction.
The bottom line is that Acadian's third quarter strengthened the profitability case: record margin, record fees and EPS, sharply improved investment performance, a cleaner balance sheet and credible new distribution channels. But the revenue miss, decelerating growth rates, a second straight slowdown in net flows, rising costs and a comp benefit that management itself called non-sustainable all mean the beat deserves scrutiny. With sentiment souring and the stock below its late-August peak, the next leg likely depends on whether exceptional performance converts back into faster organic growth.
Read our earnings preview for Acadian Asset Management Inc.: https://www.earningswhispers.com/article/AAMI/21017
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-14 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-15 | |
| Jun-26 | |
| Jun-14 | |
| May-20 | |
| May-19 | |
| May-01 | |
| Apr-30 |
