UFP Industries Grows Sales 11% But Misses On EPS As Freight Costs Erode Margins And Decking Target Is Cut
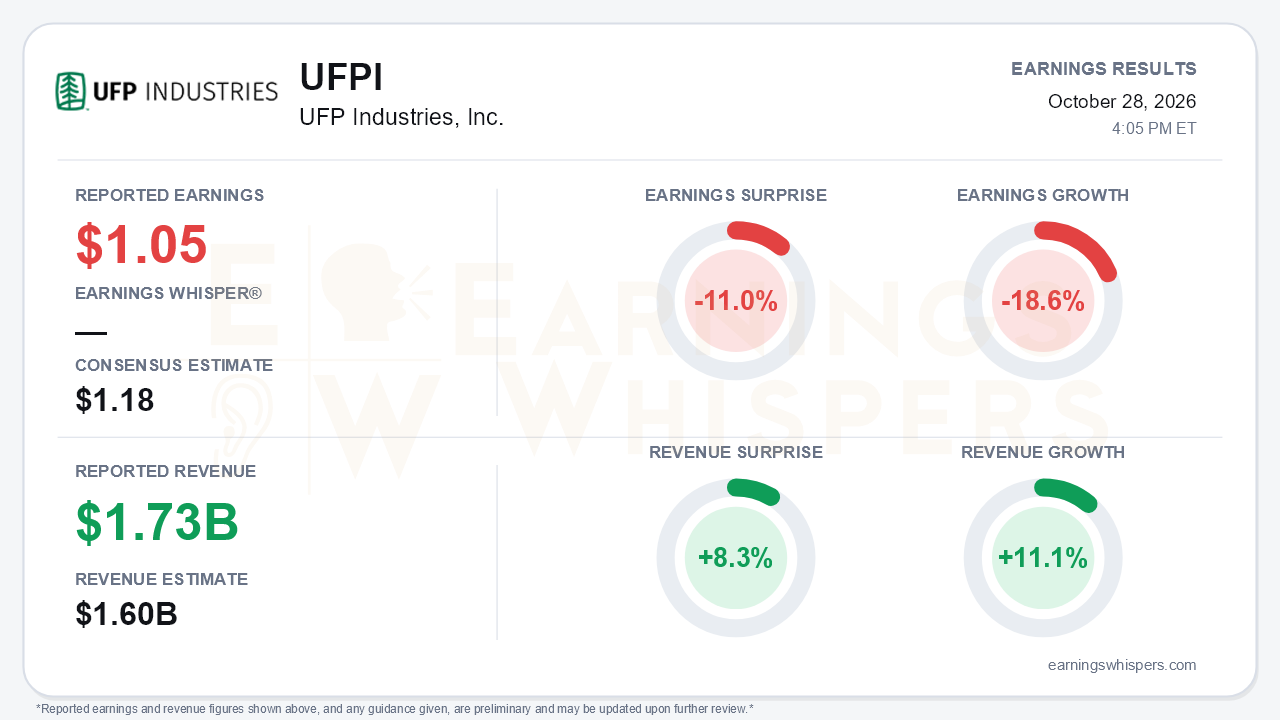
UFP Industries delivered its strongest top-line quarter of the year and still missed on earnings, and that gap between sales and profit is the story of the third quarter. Earnings of $1.05 per share fell 11.0% short of the $1.18 consensus and declined 18.6% from a year ago. Revenue of $1.733 billion beat expectations by 8.3% and grew 11.1% year over year, a sharp acceleration from roughly 3% growth in the second quarter and an 8% decline in the first. Sales growth improved, but the company is keeping less of each dollar it sells.
The composition of the beat shows the problem. Of the 11% sales gain, 5 points came from higher selling prices, 4 points from organic units and 2 points from acquisitions. Despite that pricing, gross margin fell to 14.1% from 16.8%, and adjusted EBITDA dropped to $119.3 million, a 6.9% margin, from $140.0 million and 9.0% a year ago. Margin also fell from 8.2% in the second quarter. Net freight costs rose $19 million, or 1.3 points of sales, as spot rates excluding fuel climbed about 30% before leveling off at elevated levels. Adjusted EBITDA declined in every segment. Packaging fell hardest, with sales up 18% but EBITDA down 21% on transportation and material costs. GAAP earnings also got some help from a $3.2 million net gain on asset dispositions, compared with a loss a year ago, so the operating decline was somewhat worse than the bottom line suggests.
The volume story is real. Organic units grew 4%, versus 1% in the second quarter and a 7% decline in the first. Management called it the first positive organic quarter since 2022. Site Built units swung to +12% from -3% in the prior quarter. Management attributed that to its Frame Forward systems-selling approach rather than a housing recovery. Structural Packaging volumes rose 14%, and packaging national-account sales grew about 35%. Commercial units rose 20%. Deckorators remained the standout, with decking up 69% and Surestone up 70%, and new products reached 8.7% of sales. Weak spots remain, though. ProWood units fell 4% on soft consumer demand, Factory Built units fell 10%, and new operations lost about $3 million.
The call added several new negatives on top of the reported numbers:
- **Freight:** Management now describes freight as structural. Full-year net transportation costs are quantified at roughly $65 million, with about $16 million more year-over-year pressure expected in the fourth quarter. Last quarter, management had hoped freight would stop being a margin headwind by 2027.
- **Decking and railing:** The 2026 growth target was cut to about $80 million from the $100 million reaffirmed on every prior call, partly because of a lost railing customer.
- **Capex:** The capital spending plan was trimmed again to $150-175 million, down from $300-325 million at the start of the year.
- **2027:** The preliminary view expects current challenges to persist, with the cycle described as "more prolonged."
This creates a conflict with the release. Management said profitability remains "meaningfully stronger" than in 2019. However, the trailing EBITDA margin cushion over 2019 has narrowed to about 50 basis points, from 100 at the second quarter and 170 at the end of fiscal 2025. That claim still holds, but the margin supporting it is shrinking quickly.
There are offsets. The full-year outlook was left unchanged, and the company expects to meet or exceed its $60 million cost-savings goal. New catalysts include:
- the pending $27 million Apache Products pallet acquisition;
- an upcoming national two-step distribution partner for Deckorators;
- a first explicit 2027 goal of about $50 million in incremental decking sales;
- new CoolDeck-enabled decking lines;
- increasing inbound M&A deal flow as peers pull back.
The balance sheet is solid, with about $2 billion of liquidity and no revolver borrowings. Cash has, however, fallen to $677 million from just over $1 billion a year ago after acquisitions and buybacks. Year-to-date repurchases of $183 million were made at an average of $84.24, above the current price. Operating cash flow fell to $235 million from $399 million. Management attributed part of that to roughly $100 million of seasonal working capital expected to convert to cash in the fourth quarter.
Investors were not optimistic going in. Investor sentiment remained negative but improved modestly, rising from -0.16 to -0.06. That suggests some easing of pessimism rather than renewed conviction. The stock has fallen 15.7% since opening at $92.89 after the July report, to $78.30. It now trades about 12.8% below its 200-day moving average of $89.75. Earnings Whispers price and AVWAP trend readings are both negative. These figures were captured on the release date and may not fully reflect the reaction to the call's lower targets and cautious 2027 commentary.
The bottom line is that UFP is gaining share and has returned to volume growth, but it is not yet turning that growth into earnings. With freight now treated as a lasting cost, the decking target lowered and 2027 expected to look similar to 2026, the investment case depends on cost actions and mix improvement offsetting a headwind management no longer expects to fade. Until margins stop falling, revenue beats like this one will likely do little to change the stock's setup.
Read our earnings preview for UFP Industries, Inc.: https://www.earningswhispers.com/article/UFPI/21013
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-13 | |
| Oct-13 | |
| Oct-06 | |
| Sep-25 | |
| Sep-09 | |
| Aug-18 | |
| Aug-13 | |
| Jul-29 |
