Landmark Bancorp Matches Estimates As A 4.35% Margin Offsets Shrinking Loans, Softer Fees And A Book-Value Hit
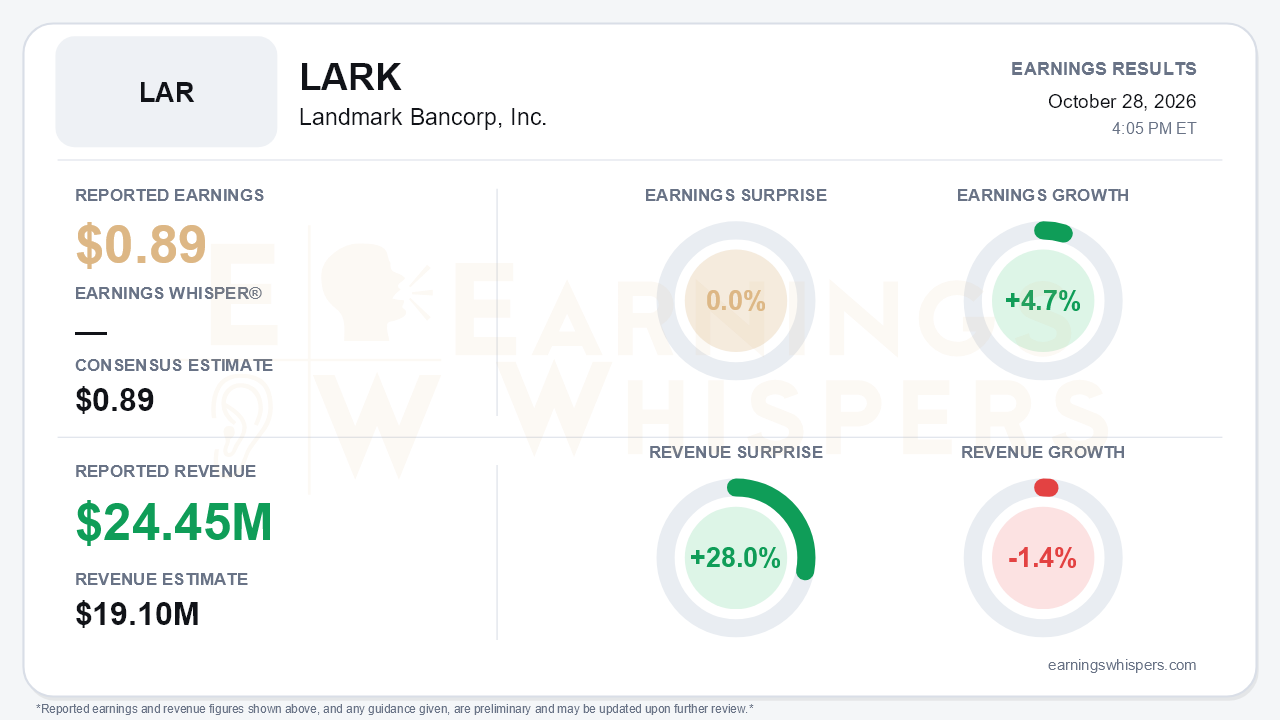
Landmark Bancorp delivered exactly what was expected on the bottom line. Diluted EPS of $0.89 matched the $0.89 consensus, and earnings grew 4.7% year over year. The more important story is how the bank got there. The net interest margin jumped 13 basis points to 4.35%, which carried the quarter. Nearly everything tied to balance-sheet growth and fee generation moved the other way: loans shrank, deposits fell, mortgage banking income dropped and book value declined. That is the central tension. Profitability per dollar of assets is improving, but the franchise is not growing, and rising rates are cutting both ways.
Earnings growth is also slowing. Diluted EPS climbed from $0.77 in the fourth quarter of 2025 to $0.83, then $0.88, and now only $0.89. Net earnings for the first nine months rose 13.5%, while the third quarter alone grew 4.7%. That gap shows a decelerating trajectory even as the absolute numbers keep inching higher.
The revenue comparison needs a caveat. Earnings Whispers recorded revenue of $24.45 million against a $19.1 million consensus, a 28.0% surprise, with revenue down 1.4% year over year. That figure appears to include gross interest income. On the bank's own measure of net interest income plus non-interest income, revenue was $19.2 million. That is roughly in line with the consensus, up from $19.2 million last quarter and $18.2 million a year ago. Investors should read the headline revenue beat as a basis difference, not a genuine top-line blowout.
The quality of the quarter is mixed. Net interest income rose 3.7% sequentially and 11.0% year over year to $15.6 million. The drivers were:
- loan yields up 15 basis points to 6.46%;
- maturing securities yielding below 3% reinvested at higher rates, lifting the portfolio yield to 3.80%;
- deposit costs edging down to 1.29%.
Management said the margin expansion was entirely core, with no prepayment fees. The margin also beat the CFO's second-quarter expectation that it would hold near 4.20%. The weaker spots:
- Non-interest income fell to $3.6 million from $4.1 million as higher rates cut mortgage gain-on-sale income by $593,000.
- Expenses rose 2.4% sequentially to $12.3 million on compensation, technology upgrades, and deposit fraud and captive insurance losses.
- The efficiency ratio worsened to 63.0% from 61.7%.
- A lighter provision of $205,000, versus $500,000 in the prior quarter, helped the bottom line hold flat-to-up.
The balance sheet is where bears have legitimate ammunition. Gross loans fell $22.2 million, reversing the modest $4.4 million of growth in the second quarter that management had hoped to build on. Management cited lumpy payoffs, including a participation absorbed by a larger bank, and lender turnover in one market. Deposits dropped $59.0 million, largely from a $61.7 million seasonal outflow of public funds. The bank backfilled that with $49.5 million of FHLB borrowings, pushing the loan-to-deposit ratio to 85.6%.
Rising rates also widened unrealized securities losses by $10.9 million. As a result:
- book value per share fell to $26.24 from $27.35;
- tangible book value fell to $20.68 from $21.76;
- tangible common equity to assets slipped to 8.09%.
Credit is a split picture. Net charge-offs were just 0.01%, non-performing loans eased to $12.5 million, and reserve coverage rose to 1.19%. Against that, 30-89 day delinquencies climbed to 0.77% from 0.57%, tied to a single commercial real estate borrower. The CEO acknowledged there is still work to do on credit culture.
On the call, management offered a constructive margin narrative. The CFO now describes the balance sheet as slightly asset sensitive and expects the margin to increase over the next year as rates rise following the Fed's recent move. Other forward-looking points included:
- the addition of experienced credit and risk executives;
- a possible re-entry into the paid-off participation credit;
- the 26th consecutive annual 5% stock dividend and the 101st consecutive cash dividend.
No formal numeric guidance changed. Demand signals, notably loan production and mortgage activity, weakened rather than improved.
The market has been unmoved. Shares at $32.09 are up just 0.3% from the $32.00 opening price after the July report. Investor sentiment sits mildly negative at -0.29, which suggests some caution despite the steady earnings climb. Earnings Whispers trend readings are balanced, with price trend neutral and AVWAP positive. That fits a stock moving sideways while fundamentals pull in opposite directions.
The bottom line is that Landmark's margin story remains credible and may strengthen if rates keep rising. However, that same rate backdrop is eroding book value and mortgage income while loan balances contract. An in-line quarter built almost entirely on spread expansion leaves the investment case dependent on the bank restarting loan growth and keeping the early-stage delinquency uptick isolated.
Read our earnings preview for Landmark Bancorp, Inc.: https://www.earningswhispers.com/article/LARK/21319
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Apr-29 | |
| Apr-29 | |
| Apr-16 | |
| Feb-11 | |
| Feb-03 | |
| Jan-29 |
