Murphy USA Beats By 18.5% On A Fuel-Supply Windfall, But The Retail Core Is Flat To Softer
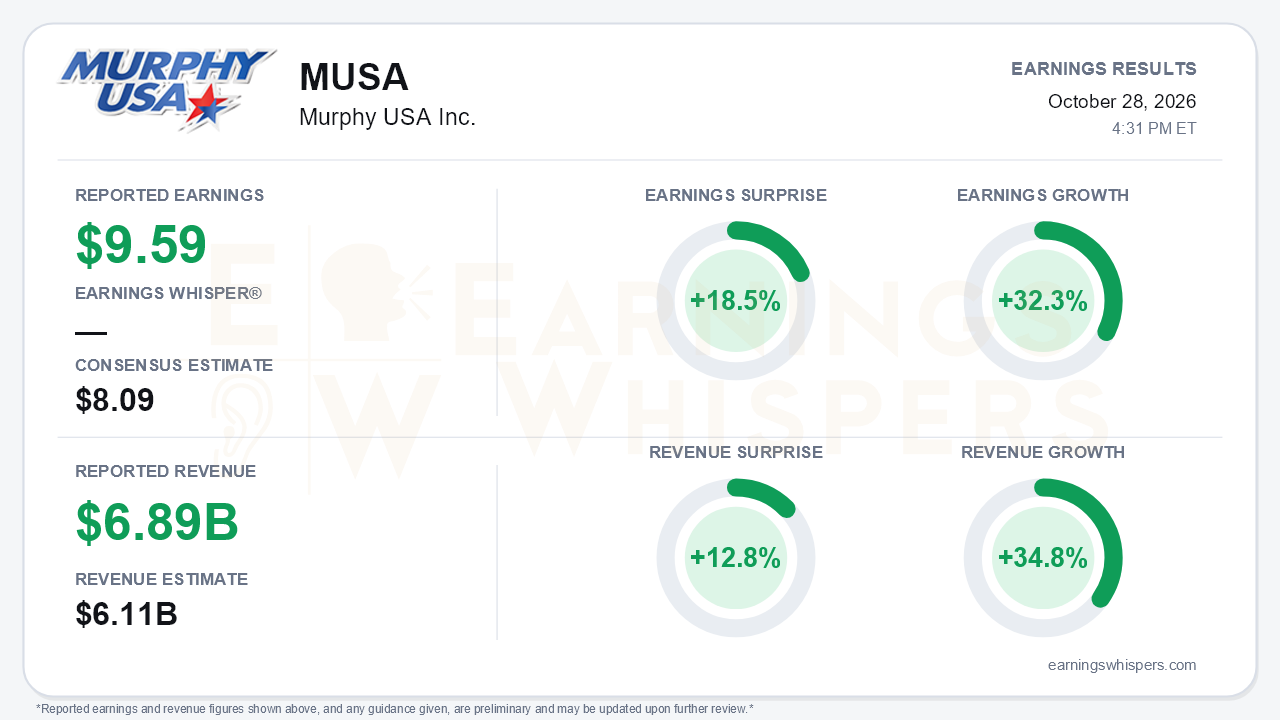
Murphy USA delivered a decisive third-quarter beat. It earned $9.59 per share against a $8.09 consensus, an 18.5% surprise, and earnings grew 32.3% year over year. Revenue of $6.89 billion topped the $6.11 billion estimate by 12.8% and rose 34.8%. The headline is strong. The source of the strength is the central tension. Nearly all of the profit improvement came from the fuel supply and RINs operation, which monetizes market volatility. The traditional retail engine, by contrast, was flat to modestly weaker.
The fuel table makes the point plainly. Total fuel contribution rose $94.6 million, or 24.6%, to $479.4 million. Fuel supply including RINs accounted for $94.1 million of that increase, jumping to 9.6 cents per gallon from 2.4 cents a year ago. RIN revenue alone more than doubled to $134.5 million. Retail fuel contribution rose just $0.5 million. Chain gallons grew 3.3%, but retail margin slipped to 27.4 cpg from 28.3 cpg, and same-store volume rose only 0.1%.
The revenue beat is largely a price story rather than a volume story. Petroleum product sales climbed to $5.6 billion from $3.9 billion. Merchandise weakened against last year's heavily promoted nicotine pouch quarter:
- Merchandise contribution fell 2.8% to $234.5 million.
- Unit margin slipped to 20.3% from 21.5%.
- Nicotine contribution dollars fell 8.0%.
Several other items flattered the bottom line:
- **No restructuring charge** this year, versus $12.6 million a year ago.
- **A smaller share count.** Diluted shares fell to 18.36 million from 19.23 million.
- **A working-capital release.** Operating cash flow nearly doubled to $348.1 million, helped by an $85.6 million inflow.
The quality of the beat therefore deserves scrutiny, even if the cash generation is real.
The call preserved a credible operating story beneath the windfall. Management argued that holding retail margin within roughly a penny of last year during a rising-price quarter supports its structural-margin thesis. It said same-store gallons beat OPIS industry data by about six points, and that October volumes ran at 100% of the prior year despite hurricane closures.
Full-year volume is tracking toward the high end of the -1% to -3% guide. Operating expenses are expected to land below the already-low guidance. Store opex excluding payment fees and rent fell 0.8% per store, and payment fees driven by higher fuel prices explained about three-fourths of the $32 million rise in store costs.
On growth, management now frames 45 to 50 openings this year, up from the low end of roughly 45, and 50-plus annually in 2027. The call cited 18 openings year to date and 55 stores under construction. Those figures run slightly ahead of the release's quarter-end count of 16 new-to-industry openings and 53 stores under construction, likely reflecting activity after September. The tone grew more confident and leaned on 2027 earnings power, though no formal guidance was raised.
The forward debate centers on durability. Management expects tight supply and volatility to persist well into 2027, even if the war ends. That view underpins expectations that fuel supply profitability will stay above the normal 2 to 3 cpg. Bears have legitimate ammunition, however:
- **Fuel supply is already fading.** Controllable supply profits fell sequentially from the second-quarter peak.
- **The windfall can reverse.** Supply normalization or a sustained price decline would undo the benefit.
- **QuickChek has deteriorated again.** Second-quarter commentary called it 'stabilizing'; it now 'continues to face pressure.'
- **Discretionary categories are weak.** Non-nicotine same-store sales are negative on lottery and beer, and high gas prices are hurting discretionary spending.
- **Newer stores are slow.** The 2024 and 2025 build classes are ramping slower on fuel.
- **Competition persists** in Colorado and Florida.
- **Q4 is a harder setup.** It brings tough November-December volume comparisons and an opex catch-up.
Against those risks, the company has several optional upside levers:
- The White Castle automated-kitchen test, now at 100-plus units.
- Legal vape products re-entering the channel.
- An 11% dividend increase to $0.72.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive but weakened sharply, falling from 0.43 to 0.15. That suggests expectations had already cooled before the report. Shares trade at $515.28, down 4.6% since the opening after the prior report, and sit essentially on the 200-day moving average of $515.18. The company repurchased stock at an average of $549.22 during the quarter, above where shares now trade. Price trend readings are neutral and AVWAP remains negative, consistent with a stock the market has been reluctant to reward for windfall-driven earnings.
The bottom line is that Murphy USA posted an impressive beat with strong cash flow, rising returns to shareholders, and a firming store pipeline. The upside was powered overwhelmingly by volatile fuel supply and RIN gains rather than retail margin or merchandise growth. Investors who accept management's view that tight supply persists into 2027 have a case for elevated earnings power. Those focused on QuickChek, softer merchandise margins, and the cyclicality of supply profits will see a quarter whose headline outran its core.
Read our earnings preview for Murphy USA Inc.: https://www.earningswhispers.com/article/MUSA/20963
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-13 | |
| Sep-17 | |
| Sep-11 | |
| Aug-31 | |
| Aug-31 | |
| Aug-24 | |
| Aug-20 | |
| Aug-13 | |
| Aug-06 |
