Meritage Homes Misses, Pulls Guidance And Shifts Into Liquidity-Defense Mode As Demand Slides
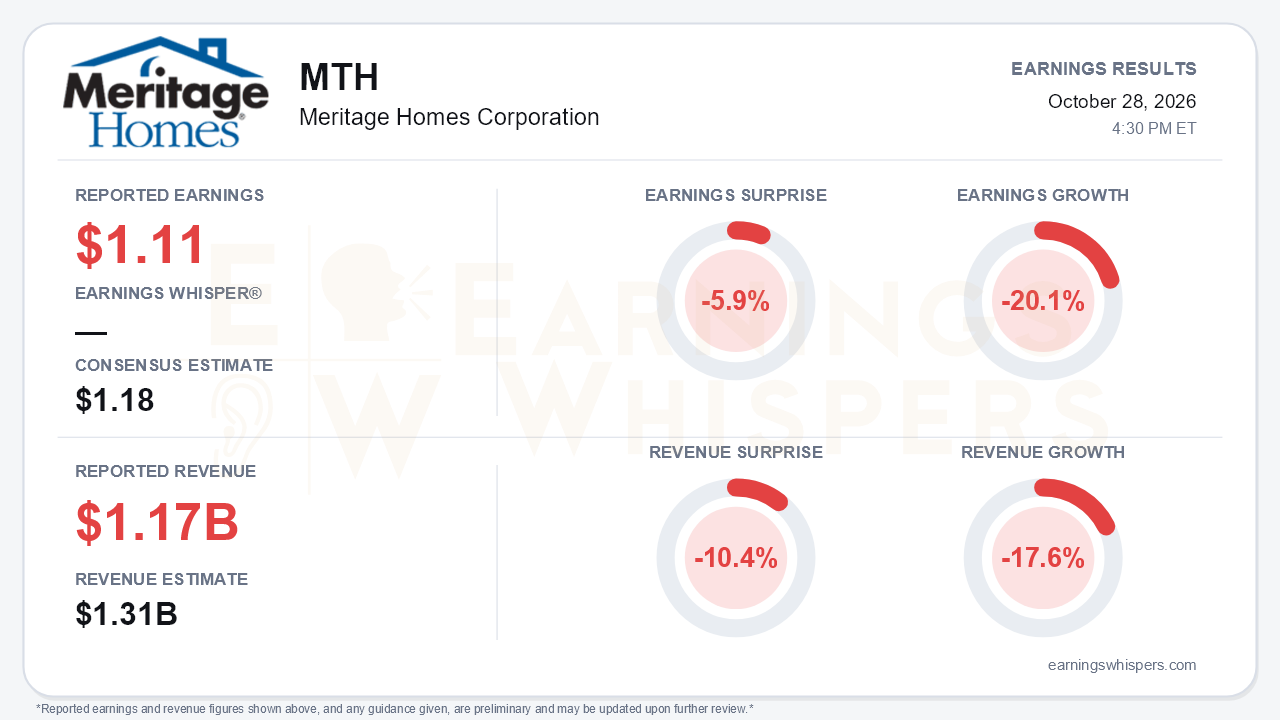
Meritage Homes delivered a third quarter that was less about a modest earnings miss than about a company changing posture. Adjusted EPS of $1.11 fell short of the $1.18 consensus by 5.9% and declined 20.1% year over year. Revenue of $1.173 billion missed the $1.31 billion estimate by a wider 10.4% and fell 17.6%. GAAP diluted EPS was $1.04 versus $1.39 a year ago. The more consequential development came alongside the numbers. Management withdrew its fourth-quarter and preliminary 2027 guidance, citing week-to-week volatility, and cut land spending and buyback commitments. A builder that spent the first half defending its outlook is now explicitly prioritizing liquidity. That is the central takeaway.
The quality of the quarter deserves scrutiny because it fell short of management's own targets, not just the Street's. Closings of 3,187 homes came in below the 3,300-3,600 range issued in the second quarter. Home closing revenue of $1.2 billion missed the $1.26-1.35 billion guide. Adjusted EPS landed only at the low end of the $1.10-1.30 range. Adjusted home closing gross margin was 17.9%, down from 18.6% in Q2 and 20.1% a year earlier, and slightly below the roughly 18% guide. GAAP margin was 17.4% after $6.6 million of impairments. Two items helped hold up the bottom line:
- A 20.1% tax rate, aided by purchased clean fuel production credits, versus 22.6% a year ago.
- A 9% lower diluted share count following heavy repurchases earlier in the year.
Without those supports, the earnings decline would have looked worse.
The operating trend is unambiguously decelerating:
- Orders fell 5% year over year in Q1, 9% in Q2 and 15% in Q3, to 3,083.
- Absorption dropped to about 3.0 net sales per community per month, from 3.5 in Q2 and 3.8 a year ago. A 7% larger average community count only partially offset the slowdown.
- Mortgage rates climbed from roughly 6.6% to 7.5% during the quarter, and management said the weakness carried into October.
- Incentive and rate buy-down costs rose notably.
The source material is inconsistent on pricing. The press release puts Q3 order ASP at $383,000, down just 2% year over year. The call analysis cites $330,000 versus $385,000 in Q2. Either way, the direction is lower prices driven by incentives. Management also said it chose margin preservation over pace, yet margins still slipped. That combination suggests limited pricing power.
The forward risks have multiplied:
- **Land costs:** Management now expects higher-cost 2022-2025 land vintages to weigh on margins "through at least 2027." That is later than the "tail end of 2027/early 2028" recovery framing offered on the Q2 call.
- **Further charges:** A fourth-quarter land portfolio review could bring additional walkaways and impairments.
- **Spec inventory:** Specs are running at about 5,500 homes, roughly five months of supply and up 7% sequentially, so starts will be cut.
- **2027 pace:** The 2027 plan now assumes absorption at the low end of the 3-4 range.
On the capital side, FY26 land and development spend was cut to below $1.5 billion from $1.7-2.0 billion. Buybacks have gone from a $100 million-per-quarter plan to $55 million to no commitment at all. Cash fell to $677 million from $807 million in Q2, and net debt-to-capital rose to 18.9% from 17.1%.
There are offsets. The balance sheet remains sound, with no revolver borrowings and leverage well below the mid-20s ceiling management references. SG&A held at 11.0% of revenue, with absolute dollars down, and further savings are targeted for 2027. Cancellations were steady at 13%, and completed specs fell by about 1,100 units year over year. The sale of five communities to build-for-rent partners accelerates the return of capital. However, those homes will close at roughly zero margin through the first half of 2027. The shift toward first move-up product is a genuine longer-term lever, but management does not expect it to show up in orders and closings until the second half of 2028 and 2029.
Investors had already been leaning away from the stock, and the report deepened that. Earnings Whispers investor sentiment swung from a roughly neutral 0.03 at the prior report to -0.30, a meaningful turn negative. Shares have fallen 20.5% since opening at $78.06 after the July report, to $62.02. They sit about 10% below the 200-day moving average of $69.07. Price and AVWAP trend readings both remain negative. The market has been discounting deterioration for a full quarter, but withdrawn guidance gives bears legitimate ammunition that estimates have further to fall.
The bottom line is that Meritage's quarter marked a shift from managing a soft patch to bracing for a prolonged one. The headline miss was moderate. The bigger signals were accelerating order declines, a miss against its own guidance, a delayed margin recovery and the retreat from guidance and buybacks. The balance sheet gives the company room to wait out higher rates, but until absorption stabilizes and visibility returns, the earnings trajectory points lower rather than toward a trough.
Read our earnings preview for Meritage Homes Corporation: https://www.earningswhispers.com/article/MTH/20962
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-06 | |
| Sep-21 | |
| Sep-21 | |
| Sep-16 | |
| Sep-16 | |
| Sep-11 | |
| Sep-10 | |
| Sep-03 | |
| Aug-27 | |
| Aug-25 | |
| Aug-20 |
