Medical Properties Trust Misses As HSA Rent Stoppage Undercuts A Balance-Sheet Repair Quarter
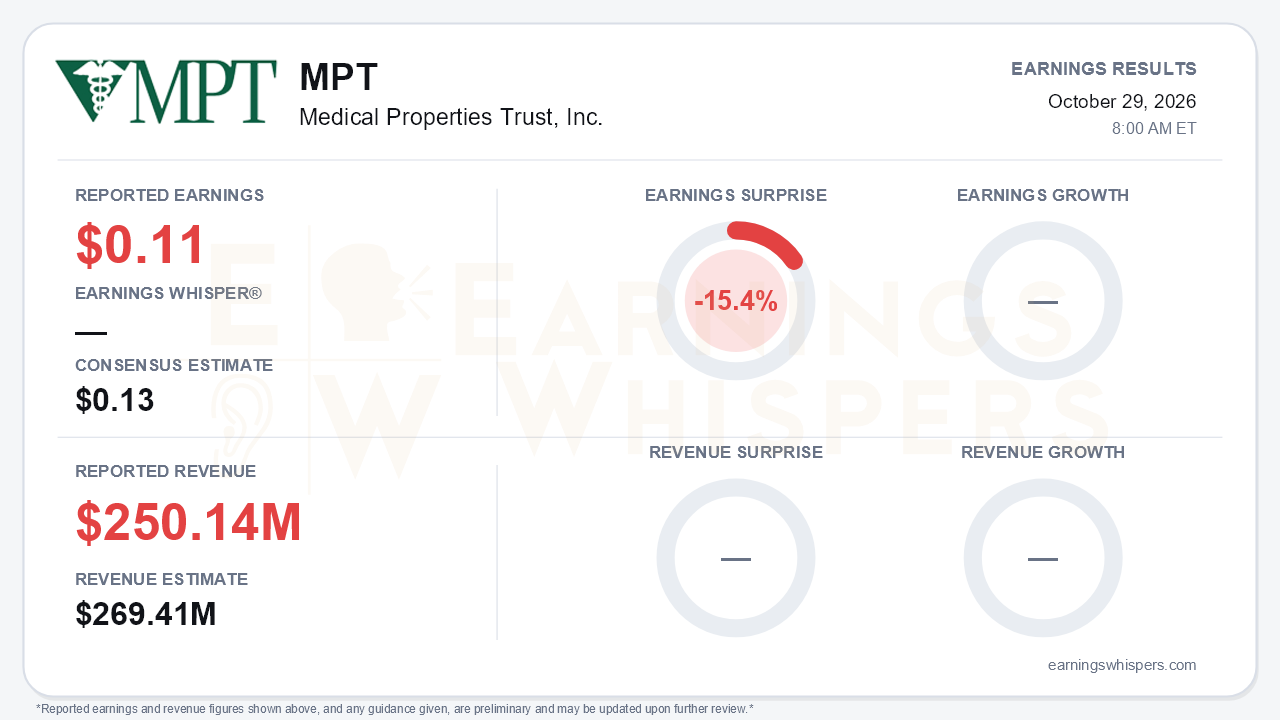
Medical Properties Trust delivered a quarter of two very different stories, and the weaker one showed up in the numbers investors care about most. Normalized FFO of $0.11 per share missed the $0.13 consensus by 15.4%, and revenue of $250.14 million fell 7.2% short of the $269.41 million estimate. GAAP net income looked far better at $202 million, or $0.34 per share, a swing from a $0.13 loss a year earlier. That figure reflects transactions rather than recurring operations: $158 million of gains on asset sales and a $70 million gain from repurchasing debt at a discount. The central tension is plain. MPT made real progress on its balance sheet, but its tenant base deteriorated in ways that cut directly into recurring earnings.
The miss deserves scrutiny because it was not a one-off. Normalized FFO fell from $0.13 in the year-ago quarter and from $0.14 in the first quarter, although the first-quarter figure included three to four cents of one-time items. Several pressures came together this quarter:
- **HSA rent.** HSA's failure to pay September rent cost about two cents.
- **Interest expense.** It climbed to $153 million from $132 million a year earlier, as the new secured debt carries a heavier cost.
- **Joint-venture earnings.** Earnings from equity interests collapsed to $7 million from $34 million, partly reflecting interests that were sold.
Rent billed did rise to $195 million from $181 million year over year. Even so, the recurring earnings base is shrinking just as the company sells assets to pay down debt. The $0.09 quarterly dividend, raised from $0.08 a year ago, now sits uncomfortably close to $0.11 of normalized FFO. Analysts raised dividend sustainability on the call.
The call marked a clear retreat from the confident rent-ramp narrative of the first quarter.
- **HSA.** In the first quarter, management expected HSA to reach 100% of contractual rent by October. Instead, HSA missed September rent and management offered no timeline for resumption. MPT now has roughly $150 million in working capital loans outstanding to the tenant. A dispute among HSA's principals forced a change in the tenant entity to Ardonis, and Ovation Healthcare has effectively replaced Conifer in overseeing operations.
- **Priory.** Management had hoped 1.6x coverage was near the bottom. Priory instead took an approximately 18% rent cut, about £11 million a year, with only contingent, revenue-based recapture.
- **Colombia.** MPT recorded an impairment of about $24 million on its Colombian investments after the August earthquake.
The pool of Steward-replacement rent that management had expected to approach its $160 million target in the fourth quarter is now at risk.
The balance-sheet side is where bulls have legitimate ammunition.
- **Refinancing.** MPT closed its $2.4 billion secured notes offering. It redeemed the October 2026 euro notes and roughly half of the 2027 notes, and captured about $123 million of discount in total.
- **Maturities.** A new revolver expected within weeks would eliminate the secured leverage covenant. Management says the company would then have no maturities until June 2028.
- **Asset sales.** Third-quarter sales generated about $680 million, including the Idaho hospitals sold to Intermountain at sub-7% cap rates. That pricing again suggests the hospital real estate is worth more than the equity implies.
- **Healthy operators.** NOR steps up to full contractual rent in December with 2.4x coverage. IMED surgeries rose 11%. Management still expects 2027 cash rent above $1.0 billion despite roughly $600 million of property sales.
That guidance now leans heavily on assumptions about cash-basis tenants like HSA. About $665 million of 2027 notes and a $200 million term loan also remain to be refinanced.
The market had already turned decisively against the stock before the report. Shares fell 38.9% from the $4.50 open after the August release to $2.75. They trade 46.3% below the 200-day moving average and just 5.4% above the 52-week low of $2.61, set on October 21. Earnings Whispers investor sentiment shifted from a modestly positive 0.197 to a negative -0.287, a meaningful change that reflects growing skepticism about tenant credit and the dividend. The AVWAP trend reading is negative, consistent with sustained selling pressure through the quarter.
The bottom line is that MPT bought itself time but not earnings visibility. Refinancing and asset sales at strong valuations have largely removed the near-term maturity overhang. However, the HSA rent stoppage, the Priory rent cut, and a third straight step down in normalized FFO undermine the recovery narrative management offered six months ago. Until HSA resumes paying rent and the remaining 2027 debt is addressed, the dividend and the $1 billion cash-rent target will face hard questions.
Read our earnings preview for Medical Properties Trust, Inc.: https://www.earningswhispers.com/article/MPT/21312
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Sep-23 | |
| Sep-17 | |
| Sep-16 | |
| Sep-10 |
