TPG Beats On Earnings And Lifts Fundraising Guidance, But Vanishing Carry And A Smaller Dividend Cloud The Picture
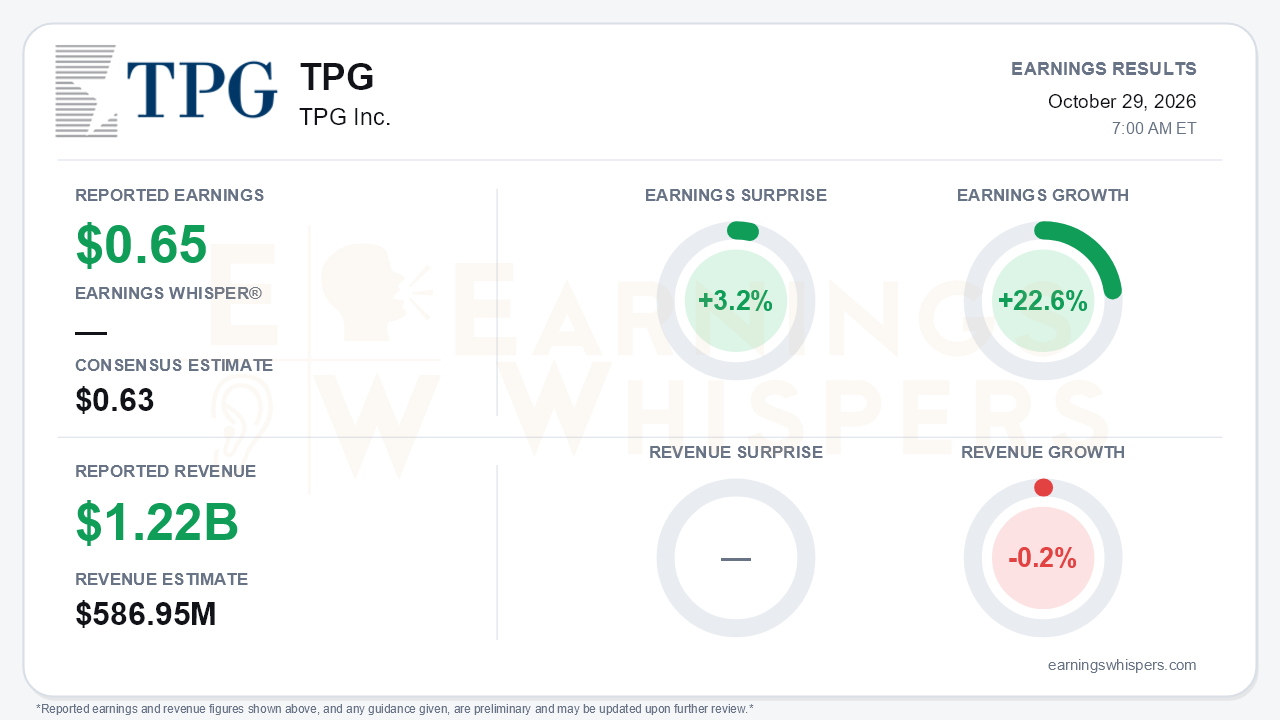
TPG Inc. reported third-quarter earnings of $0.65 per share, beating the $0.63 consensus by 3.2% and rising 22.6% from a year ago. Revenue of $1.221 billion was 108.0% above the $586.95 million consensus, yet it fell 0.2% year over year. A revenue surprise that large next to flat growth suggests the consensus and the reported figure may not measure the same thing. The beat looks like a measurement artifact more than a sign of operating outperformance. The quarter's central tension sits elsewhere. TPG is raising capital faster than at any point in its recent history, while the earnings that reach shareholders keep slipping.
The earnings line deserves scrutiny. The year-over-year comparison is flattering, but the sequential trend is not. After-tax distributable earnings per share have now declined for three straight quarters, from $0.71 to $0.70, then $0.69, and now $0.65. The board declared a $0.55 quarterly dividend, down from $0.59 last quarter and $0.61 three quarters ago. The main cause is realized performance allocations, which fell to just $7 million from $35 million in the second quarter and $68 million in the first. Exit proceeds went toward returning invested cost and absorbing markdowns in TPG Capital 8 software holdings exposed to AI disruption, so very little became carry. The fee engine looked healthier. The fee-related earnings margin was 50%, but about 47% excluding $62 million of catch-up fees, so roughly three points came from one-time items. Transaction fees also fell from the second-quarter record to $55 million, a decline management had flagged in advance.
The call kept a credible growth story intact, and the forward metrics moved decisively higher. The press release language, attributed to CEO Jon Winkelried, says TPG expects to exceed its $50 billion fundraising target. On the call, management went further and lifted full-year 2026 guidance to more than $55 billion. The firm has raised nearly $42 billion year-to-date, up from $26 billion at mid-year. Management also raised its 2026 fee-related earnings margin outlook to about 48% from 47%, a figure that had been unchanged on the prior three calls. Several funds drove the fundraising gains:
- TREP 5 opportunistic real estate opened with a roughly $5 billion first close.
- Rise Climate 2 finished at $10.4 billion, up 44% from its predecessor.
- TPG Capital 10 and HCP3 reached about $16 billion, above the prior vintage.
- TICA closed above target at $1.3 billion.
The balance sheet also hit records. Assets under management rose to $346 billion from $303 billion three quarters ago, dry powder reached $86 billion, fee-earning AUM grew 16% to $190 billion, and net accrued carry hit $1.5 billion. Management added a new long-term goal of doubling credit AUM to $200 billion by the end of 2029. Credit deployment of $7.7 billion was the strongest of the year, and software portfolio bookings growth accelerated to more than 25%.
Bears have legitimate ammunition, though. Part of the higher fundraising guidance reflects capital pulled forward from 2027, and management gave no 2027 outlook. That makes next year's comparison harder. Private equity deployment fell to $2 billion from $7.2 billion, and total deployment dropped to about $11 billion from roughly $14 billion. Management cited higher-for-longer rates as a drag on transactions. Retail flows cooled: TPOP inflows fell from $545 million in the first quarter to about $400 million, and TCAP gross inflows fell from $193 million to $134 million. Other pressures include:
- Middle-market credit non-accruals edged up to 1.6% from 1.4%.
- The fourth-quarter tax rate is set to rise to the high teens or low 20s.
- AI and data-center financing structures carry concentration and repricing risk.
Most important, the realization pickup management again promised for the fourth quarter and 2027 has been promised before without yet showing up in carry.
Investors appear to have grown wary ahead of the report. Earnings Whispers sentiment moved from slightly positive (0.053) to clearly negative (-0.185), a meaningful deterioration. The stock has behaved accordingly. At $44.59 heading into the release, shares were 5.1% below the $47.00 open after the August report and about 3% below their 200-day moving average. They were nearly 20% below the inter-earnings high of $55.50 set in mid-August, after giving back that entire post-report rally. Shares had recovered about 8% from the October 14 low of $41.24. The trend readings are mixed: price and AVWAP trends are negative, while momentum is positive.
The bottom line is that TPG delivered a quarter of two ledgers. On fundraising, dry powder, fee margins and AUM, the franchise is clearly getting stronger, and management raised guidance to match. Shareholders, however, are paid from realized earnings, and that line has drifted lower for three quarters, now with a smaller dividend. Until exits produce carry and the 2027 pull-forward question is answered, the stock's discount to its summer high reflects real uncertainty rather than simple oversight.
Read our earnings preview for TPG Inc.: https://www.earningswhispers.com/article/TPG/21138
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 12 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-01 |
TPGs $10B Climate Fund Shows Investors Arent Giving Up on the Energy Transition
TPG
Benzinga Private Markets
|
| Sep-29 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Sep-09 |
