Portland General Electric Cuts 2026 Outlook As Mild Weather And A Holdco Impasse Overshadow A Stronger Large-Load Pipeline
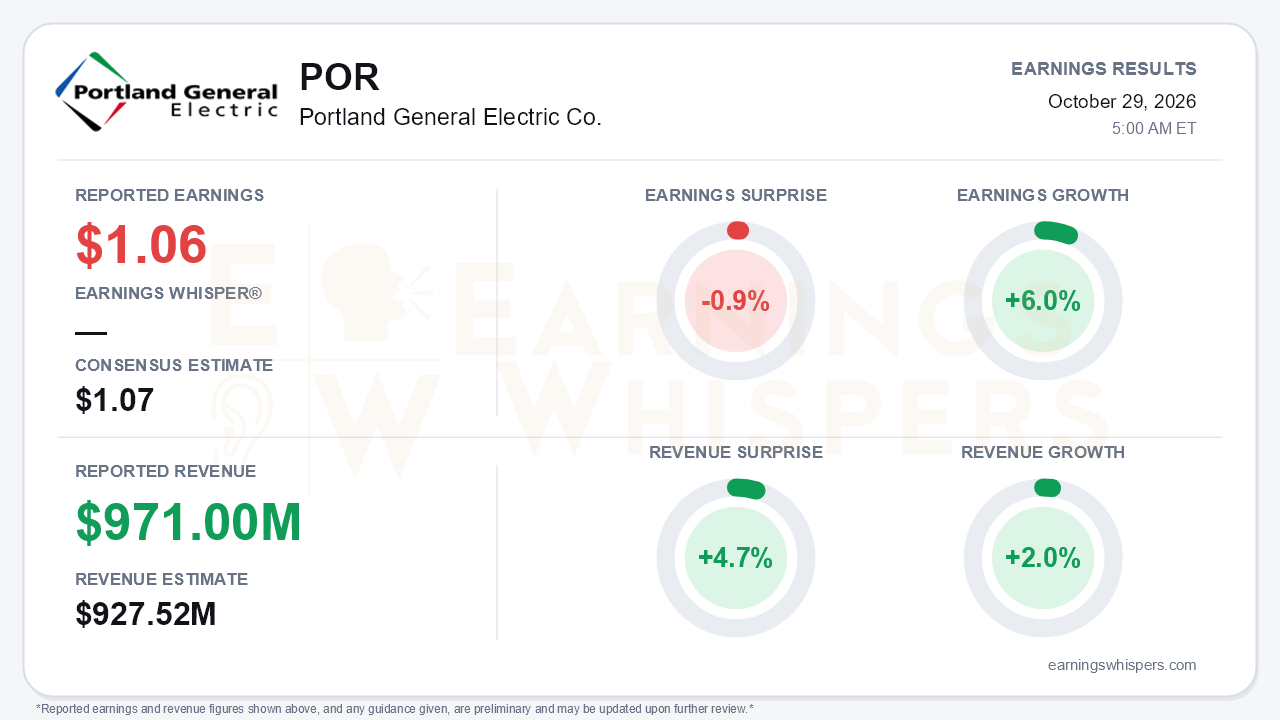
Portland General Electric's third quarter looked close to consensus on the surface, but the guidance cut was the real story. Adjusted EPS of $1.06 missed the $1.07 consensus by 0.9% and rose 6.0% from a year ago. Revenue of $971.0 million beat expectations by 4.7% and grew 2.0%. The more consequential number was the full-year outlook. PGE cut 2026 adjusted EPS guidance to $3.18-$3.28 from $3.33-$3.53, a range management had reaffirmed in each of the prior three reports, including after a $0.25 first-quarter miss. The call also showed that third-quarter results fell well short of the company's own $1.20-$1.32 quarterly guide. The near-miss against Street estimates therefore understates how much the year has slipped from management's plan.
The quality of the quarter deserves scrutiny in both directions. Weather was a real and quantifiable drag. The third quarter was the mildest in a decade, with cooling degree-days of 415 versus a 15-year average of 540. Management put the year-over-year EPS headwind at $0.15 and the year-to-date shortfall against normal weather at $0.20. Residential deliveries fell 8.9% and total retail deliveries dropped 3.0%. Two other forces shaped the result. Cost control helped, with operating and maintenance expense contributing an $0.11 EPS tailwind (versus $0.06 in the second quarter) and administrative expense falling to $86 million from $99 million. Dilution hurt: adjusted net income rose to $125 million from $110 million, but diluted shares climbed to 118.7 million from 110.4 million, which held per-share growth to 6.0%. GAAP EPS was $1.00, compared with $0.94 a year ago. The nine-month picture is weaker, with GAAP EPS of $1.98 versus $2.41.
Beneath the weather noise, the demand story is mixed rather than uniformly strong. Management cited 9% weather-adjusted industrial growth. That figure is still healthy, but it has decelerated from 11% in the second quarter, 10% in the first and 14% for 2025. The supplemental tables show cost-of-service industrial deliveries up a more modest 6.4% on a weather-adjusted basis. PGE also cut its 2026 weather-adjusted load growth assumption again, to 1%-2% from 1.5%-2.5%, and the original target was 2.5%-3.5%. Management attributed the reduction to slower industrial ramp timing and acknowledged that data center usage has been choppy. The longer-range view moved the other way:
- PGE raised its large-load capacity growth outlook to roughly 12% annually through 2030, up from about 10%.
- It added a Verus data center agreement for up to 420 MW, energizing in 2028 and fully ramped by 2033.
- The new large-load tariff, which includes take-or-pay protections, contributed about $4 million of margin in its first quarter in effect.
That is the central tension: near-term load conversion keeps disappointing while the long-dated pipeline keeps growing.
The capital program reinforces that long-term case. PGE signed build-transfer agreements for the Biglow solar-plus-storage project (about $900 million) and Salmonfly (about $853 million). Together they push 2027 capex to roughly $2.5 billion. Management said the resource-procurement years support EPS growth at or above the midpoint of its 5%-7% long-term target. Separately, the 2027 rate case seeks an approximately 4.8% overall increase, and Extended Day-Ahead Market participation is expected to deliver about $14 million in customer savings in 2027. Salmonfly, however, still needs regulatory sign-off on a waiver from competitive bidding rules.
Financing is where bears have legitimate ammunition. The Oregon commission's September 25 holding-company order included conditions management called red lines, such as a dividend restriction triggered by a one-notch credit downgrade. PGE has asked for changes and may not proceed, with a decision expected by December 7. The fallout is already visible:
- $398 million of forward equity has been deferred into 2027.
- 2027 equity guidance rose about $50 million to $150-$200 million.
- The Washington acquisition is now framed as breakeven to slightly accretive in its first full year without a holdco, versus accretive previously.
Management openly linked the current stock price and the holdco uncertainty to financing challenges. Its tone was noticeably more defensive than in prior quarters. Cash pressure adds weight to that concern. Nine-month operating cash flow fell to $811 million from $970 million, largely on lower tax credit sales, while capex rose to $1,085 million and long-term debt climbed to $5.0 billion.
The market had largely priced in trouble before the report. Shares fell 10.0% from the open after the July report to $44.27. That leaves the stock 11.5% below its 200-day moving average and just 2.3% above the 52-week low of $43.26 set on September 28, well off the August high of $51.58. Investor sentiment was already negative and weakened modestly, moving from -0.20 to -0.25. The Earnings Whispers trend signals lean negative, with price, sequential growth and AVWAP readings all pointing lower.
The bottom line is that PGE delivered a weather-dented quarter, but the guidance cut, slower industrial ramps and the holdco standoff matter more than the one-cent miss. The long-term growth story arguably got stronger, with faster large-load growth, a major data center contract and roughly $1.75 billion of new projects. The cost of funding that growth also rose. Until the December holdco decision clarifies the equity and credit path, investors are likely to weigh financing risk as heavily as the expanding pipeline.
Read our earnings preview for Portland General Electric Co.: https://www.earningswhispers.com/article/POR/21120
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 17 hours | |
| 18 hours | |
| Oct-23 | |
| Oct-21 | |
| Oct-02 | |
| Oct-01 | |
| Sep-25 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-24 | |
| Jul-08 | |
| Jul-08 | |
| Jul-01 |
