OneSpan Beats Big And Raises Again, But Timing Help And A Slower ARR Exit Rate Temper The Acceleration
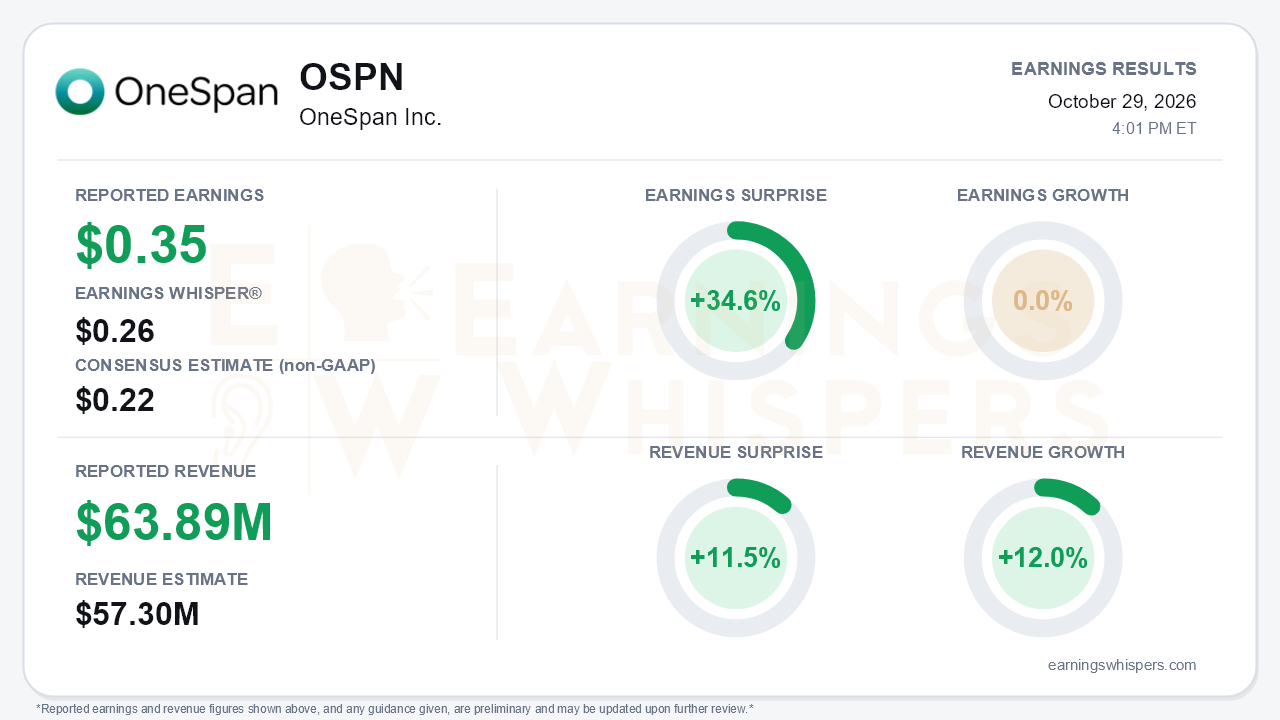
OneSpan delivered the kind of quarter that changes a narrative. Third-quarter non-GAAP earnings of $0.35 per share beat the $0.22 consensus by 34.6% and cleared the $0.26 Earnings Whisper number. Revenue of $63.89 million topped the $57.3 million estimate by 11.5% and grew 12.0% year over year, a sharp acceleration from roughly 1% growth in the second quarter and 4% in the first. Management also raised full-year guidance for the second straight quarter. Earnings growth was flat year over year on Earnings Whispers' basis, though, and parts of the top-line surge came from timing. The central tension is whether this was a genuine inflection or a strong quarter flattered by pull-forwards.
The release supports both readings. Subscription revenue rose 16% to $51.5 million, up from 11% growth in Q2 and 8% in Q1. Cybersecurity revenue grew 11% after shrinking about 7.5% in the prior quarter. Digital Agreements revenue climbed 14%, and its segment operating income jumped to $6.9 million from $4.2 million. Gross margin expanded to 76% from 74%. GAAP diluted EPS improved to $0.20 from $0.17.
The quality of the beat still deserves scrutiny. Total operating costs rose about 17%, faster than revenue, as sales and marketing, G&A and corporate costs all climbed. Long-term incentive compensation, which is excluded from non-GAAP results, jumped to $5.5 million from $3.6 million. Adjusted EBITDA grew 10%, slower than revenue, and the call put adjusted EBITDA margin at 30.1%, down from 30.7%, citing Build38 integration and go-to-market spending. Nine-month operating income remains below last year's level.
The balance sheet also shifted. Cash fell to $51.4 million from $70.5 million at year-end after $34.6 million in acquisition spending, and goodwill rose by roughly $24 million. The release does not isolate Build38's contribution to growth.
The call explained how the business is changing, and the operating metrics improved broadly:
- **ARR:** reached $195.5 million, up 8.5% year over year and up $5.9 million sequentially.
- **Retention:** net retention improved to 105% from 103% in Q2, and gross retention ticked up to 91%.
- **Tone:** management shifted from foundation-building language to saying it feels better than it did six to twelve months ago.
The call was also candid about what flattered the quarter:
- **Hardware timing:** hardware grew 7%, but that reflected shipments pulled in from Q4, and the full-year hardware guide was left unchanged at $46-48 million.
- **Lumpy cyber revenue:** some cybersecurity subscription strength came from variable multi-year term licenses and past-due catch-up revenue.
- **Digital Agreements overages:** overage revenue is declining sequentially after a large banking customer moved to a larger ratable multi-year contract. That is healthier long term but a near-term headwind.
- **Slower ARR exit rate:** the Q4 ARR guide midpoint implies only about 6.5% growth, as legacy churn lingers for a couple more quarters.
The guidance raise is the strongest evidence that the improvement is not purely timing. Full-year revenue guidance moved to $254-258 million from $248-252 million, and the entire increase sits in software and services. Adjusted EBITDA guidance rose to $72-76 million, well above the original $64-68 million. ARR guidance rose to $197-201 million.
On the product side, DigipassONE launched in July. Verify is slated for general availability in early 2027, ahead of EU digital identity wallet requirements, and an Authenticate free trial arrives in November. Management said FIDO2 security keys are picking up speed and sees hardware approaching flattish. Bears have legitimate ammunition, however. Growth is still driven mostly by legacy-product expansion, and long bank sales cycles will delay meaningful revenue from the new platforms.
The market had already moved ahead of the report. Shares rose 14.3% from the opening price after the August report to $20.08 as of the October 28 snapshot. That left them about 44% above the 200-day moving average and just 3.6% below the $20.82 52-week high set on October 26. Investor sentiment swung from slightly negative (-0.05) to moderately positive (+0.23), a meaningful improvement but well short of euphoric. The Earnings Whispers price, momentum and AVWAP trends are all positive, consistent with a stock that rallied into earnings rather than one that was overlooked. The market setup is therefore more complicated than the surprise implies: much of the good news was partly anticipated, and the slower Q4 ARR trajectory is the kind of detail a stock near its highs can be sensitive to.
The bottom line is that OneSpan produced a clear beat, a real acceleration in subscription and cybersecurity revenue, improving retention and a second consecutive guidance raise. Together, these preserve a credible growth story. Investors should still separate the durable gains from the help provided by hardware pull-ins, catch-up revenue and lumpy term licenses. Rising costs, a slightly lower adjusted EBITDA margin and a decelerating ARR exit rate show the turnaround is progressing but not yet self-sustaining. The next proof points are ARR growth stabilizing above the implied Q4 level and early traction from DigipassONE.
Read our earnings preview for OneSpan Inc.: https://www.earningswhispers.com/article/OSPN/21228
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| Jul-09 | |
| Jun-24 | |
| Jun-15 |
